
INSURANCE GUIDE → LIFE INSURANCE
Life Insurance Singapore 2026: Complete Guide to Term, Whole Life & Universal
Everything you need to choose the right life insurance — coverage calculations, provider comparisons, and the term vs whole life decision explained with real numbers.
Last updated: May 2026 · 20 min read · By The Kopi Notes
📍 Start Here
Jump to the guide most relevant to your situation.
Life Insurance Overview
Life insurance in Singapore exists for one core purpose: replacing your income if you die or become totally and permanently disabled. If you have dependants — a spouse, children, or elderly parents who rely on your income — life insurance is non-negotiable financial planning.
Singapore’s life insurance market offers three main product types, each suited to different needs and budgets. Term life provides pure protection at the lowest cost. Whole life adds a forced savings element with lifetime coverage. Universal life offers flexible premiums and adjustable coverage — typically for higher-net-worth individuals.
The most common mistake: buying too little coverage of an expensive type. A 30-year-old paying $300/month for whole life might only get $200,000 in coverage — when they actually need $800,000+. The same budget in term life could provide $2,000,000 in protection.
Not financial advice. All figures are for educational reference only. Data as at May 2026 unless noted.
Term vs Whole Life vs Universal: Comparison
Term Life Insurance
Term life insurance provides a death benefit for a fixed period — typically until age 65 or 70. If you die during the term, your beneficiaries receive the payout. If you outlive the term, coverage ends and no money is returned. This “use it or lose it” structure makes term life the cheapest form of life insurance by far.
For a healthy 30-year-old male non-smoker, $500,000 of term life coverage costs roughly $25–45/month — compared to $250–400/month for equivalent whole life coverage. The premium savings can be invested in ETFs or robo-advisors, which historically deliver far better long-term returns than a whole life policy’s cash value.
Our detailed term life guide covers DPI options, provider comparisons with actual quotes, rider considerations, and a step-by-step framework for calculating your coverage needs.
Whole Life Insurance
Whole life insurance provides coverage for your entire lifetime (typically to age 99 or 100) and builds a guaranteed cash value over time. Premiums are fixed and significantly higher than term life — you’re paying for both the insurance protection and a forced savings component.
The cash value grows at a guaranteed rate (typically 1–2% p.a.) plus non-guaranteed bonuses (potentially bringing total returns to 3–4% p.a.). However, it takes 15–25 years for the cash value to exceed total premiums paid — the early years see heavy allocation to mortality charges and distribution costs.
Whole life makes most sense for estate planning (ensuring a payout regardless of when you die), legacy goals, or people who genuinely cannot discipline themselves to save. For pure income replacement, term life is almost always more cost-effective.
Universal Life Insurance
Universal life insurance offers flexible premiums and adjustable death benefits — you can increase or decrease coverage and premium payments within limits. The cash value earns a crediting rate that varies with market conditions, typically with a minimum guaranteed floor.
In Singapore, universal life is primarily marketed to high-net-worth individuals for estate planning and wealth transfer. Minimum premiums are often $50,000+ annually. The flexibility can be an advantage, but the complexity and variable returns mean this is rarely appropriate for the average consumer.
Unless you have specific estate planning needs and a substantial budget, term life (or a combination of term and whole life) is more straightforward and cost-effective.
How Much Coverage Do You Need?
Coverage Calculation Checklist
1. Income replacement: Annual income × years until youngest child is independent (typically 9–12x)
2. Outstanding debts: Mortgage balance + car loan + other liabilities
3. Children’s education: $50,000–$300,000 per child (depending on local vs overseas)
4. Minus existing resources: CPF savings, existing insurance, investments, spouse’s income
= Your coverage gap — this is how much life insurance you need
All Life Insurance Articles
Browse our detailed guides on each life insurance type.
Life Insurance Articles
Term life, whole life, and other life insurance guides for Singapore.
Data verified as at 26 Sep 2026 | Life Insurance | 8 min read
Read article
No employer group CI. No paid sick leave. No employer CPF during recovery. Here is how to close all three gaps.
Read article
Term life insurance laddering is a strategy where you buy two or three smaller policies with different coverage periods — instead of one large single policy.
Read article
Self-employed Singaporeans have no employer sick leave — DI insurance fills the gap. Learn the MAS 75% cap, best deferment periods for freelancers, and how AIA, Singlife, and GE plans compare in 2026.
Read article
Whole life insurance premiums cost 6-7x more than term life. In a high-rate environment, the opportunity cost of that gap has never been higher. This article breaks down the real numbers.
Read article
Critical illness insurance pays you a tax-free lump sum if you are diagnosed with cancer, heart attack, stroke, or any of 36 other major illnesses under the LIA CI Framework 2024.
Read article
The waiting period on your disability income insurance is the one variable that can cut your annual premium by 30 to 45 percent — or leave you scrambling for cash when you need it most.
Read article
Most CI insurance in Singapore has a 90-day waiting period. Claims for cancer, heart attack, or stroke within the first 90 days will be rejected. Here is what to know before you buy.
Read article
Coverage from S$413/yr · Fed at 3.75–4.00% · Compare AIA, Prudential, Singlife, FWD
Read article
With the Fed at 3.75–4.00%, the buy-term-invest-the-rest math now strongly favours term + standalone CI over whole life CI riders. Here’s what changed and how to decide.
Read article
6 clauses that can void your payout — and how to make sure your family is actually protected.
Read article
Critical illness insurance claims in Singapore get rejected for 6 key reasons. Learn how to avoid CI claim rejection with this evidence-based guide for Singapore policyholders.
Read article
Multi-pay CI insurance pays out for each new critical illness diagnosis — not just the first. Compare top Singapore plans from Singlife, Tokio Marine and AIA, and find out if paying 30–50% more is worth it for your situation.
Read article
Your base term life plan covers death and terminal illness. Riders extend that coverage for a price. Some are worth every cent. Others duplicate what you already have. This guide covers the five most common riders in Singapore and when to add them.
Read article
Standard CI plans only pay for late-stage diagnoses. Early stage CI covers cancer at Stage 1, carcinoma in situ, and mild heart attacks. Here is what the coverage gap means in practice.
Read article
Data verified as at 9 Sep 2026 | Sources: MOH, LIA
Read article
Use the LIA income multiplier formula to find your exact sum assured — with worked SGD examples and 2026 premium data.
Read article
The Life Insurance Association's updated CI definitions have been in force since 1 October 2025. Here is what the 37 standardised conditions actually require for a payout — and the common reasons claims fail.
Read article
ⓘ Data verified as at 6 September 2026. Premiums and product details change — confirm with your insurer before buying.
Read article
LIFE INSURANCE · 2026 GUIDE
Read article
A step-by-step coverage calculator guide for Singapore residents — LIA benchmarks verified
Read article
Your complete guide to all four types — and which combination you actually need.
Read article
A data-backed breakdown for Singapore policyholders
Read article
If you pay S$1,200 a year in CI insurance premiums and expect a tax deduction at year-end, you may be in for a surprise.
Read article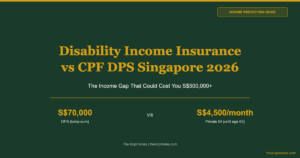
The complete guide to plugging Singapore's income protection gap — with real numbers
Read article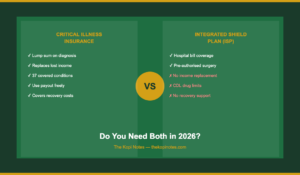
Data verified as at 30 August 2026 | Category: Life Insurance
Read article
Data verified as at 29 August 2026. Premium figures are indicative benchmarks based on published market data — always obtain a personal quote directly from your insurer or licensed adviser before making any decision.
Read article
Is the Extra Premium Worth It?
Read article
A plain-English guide to term life insurance riders in Singapore 2026 — CI rider, TPD, waiver of premium, disability income, and accidental death. Find out which add-ons are worth paying for.
Read article
LIFE INSURANCE · THE KOPI NOTES
Read article
Data verified as at 25 August 2026. Term life insurance is the most cost-effective way to protect your family's financial future in Singapore — but many buyers get the sum assured wrong.
Read article
Data verified as at 23 August 2026. This article covers the LIA CI Framework 2024 changes, what the 37 standard critical illness conditions cover, and how to assess your coverage needs.
Read article
A plain-English review of all three China Life term life plans - who can buy each one, what they cover, and where the benefit limits sit.
Read article
i-Protect, i-Care & DIRECT–Term compared — sum assured, riders, real premiums, and SDIC protection
Read article
HSBC Life Term Protector is HSBC Life Singapore's flagship term insurance plan, covering death and terminal illness from S$100,000 up to age 99, with a higher-tier Term Protector Prime version starting at S$2,000,000 for high-net-worth buyers.
Read article
DPS is not compulsory — here's the real trade-off between cancelling it and keeping it, with 2026 premiums straight from CPF Board.
Read article
Standard CI plans only pay for major-stage cancer. Compare Income Lady 360, HSBC CritiCare for Her and AIA Glow of Life for early-stage female cancer cover in Singapore.
Read article
Conversion Privilege Explained, Insurer Comparison & A Worked Example
Read article
Self-employed and freelance in Singapore? Here's how much critical illness insurance you actually need, real 2026 premium ranges, and what MediSave doesn't cover.
Read article
Singlife's flagship term life plan now comes in two flavours — Regular Pay and Limited Pay. Here's what each actually costs, and whether the "get your premiums back" promise is as good as it sounds.
Read article
HPS, MRTA and level term life insurance all protect your mortgage — but they work very differently. Here's how to pick the right one.
Read article
If nobody relies on your income, life insurance can feel pointless. But "single" doesn't always mean "no financial risk.
Read article
Documents, timelines, and payout rules straight from LIA's official claims guidelines
Read article
7 major insurers' whole life plans compared side by side — features, riders, and the real cost vs term life, plus how LIA's illustrated rate caps affect your projected returns.
Read article
Two Singapore insurers let you get something back if you outlive your term policy — but they don't pay back the same thing. Here's the difference, with real product terms.
Read article
What keeps your life insurance policy alive if you're diagnosed with a critical illness and can't pay the premiums yourself.
Read article
A plain-English guide to how TPD riders really work — the age-based definitions, the accelerated payout structure, and what it costs in 2026.
Read article
How to buy up to S$400,000 of term life cover directly from an insurer — no adviser, no commission
Read article
AIA's newest critical illness plan launched in May 2026 — here's what it covers, what it costs, and why it isn't open to everyone.
Read article
Singapore 2026 — the three fine-print rules that decide if your CI claim actually gets paid
Read article
TPD protection to age 84, four different term plans for four different budgets — here's how Singapore's largest home-grown insurer's term life lineup stacks up.
Read article
Your DPS baseline, the DIME method, and Singapore's S$373 billion protection gap — a step-by-step way to find your real number.
Read article
TPD protection to age 86, renewal to 90, and a rider suite that covers early and severe-stage critical illness — here's what Etiqa's flagship term plan gets right, and where it doesn't fit.
Read article
GREAT Term 2's real cost vs 4 other insurers, its critical illness rider, and why Singapore's oldest life insurer isn't the cheapest — but might still be worth it.
Read article
A real 2026 premium comparison, and what actually drives the price
Read article
The LIA's 4x-income rule, real SGD treatment costs, and a step-by-step framework to find your number.
Read article
LIA Singapore's Q1 2026 results reveal the highest first-quarter payout in six years — here's what it means for your coverage
Read article
How April 2026’s Integrated Shield Plan rider overhaul shifts your out-of-pocket risk — and what it means for your critical illness coverage.
Read article
PRUActive Term's real cost vs 6 other insurers, its critical illness riders, and when PRUVital Cover or the DIY DIRECT plan beats it on price.
Read article
CPF's Dependants' Protection Scheme gives you free term life cover — but for most working adults, it covers only a fraction of what their family actually needs.
Read article
A plain-English look at PRUActive Protect and Prudential's five other critical illness plans — coverage, riders, and who each one actually fits.
Read article
Real premium comparisons, the DPI shortcut, and the exact moves that lower your quote — without cutting the coverage you actually need.
Read article
A complete breakdown of AIA's flagship term life plan — premiums, riders, AIA Vitality discounts, and how it stacks up against FWD, Singlife and Manulife.
Read article
A 2026 employer's guide to group medical insurance in Singapore — costs, top providers, and how it fits with IRAS tax rules and MOM requirements.
Read article
What's compulsory, what's optional, and how SME owners and HR teams should set up employee cover in 2026.
Read article
Manulife term life insurance in Singapore centres on the ManuProtect Term (II) — a flexible plan covering death and terminal illness for 5 to 40 years, renewable to age 85 without a medical examination.
Read article
From $16/month for $500,000 coverage — our honest assessment of FWD's term life plans, premiums, and claims service.
Read article
A practical side-by-side comparison to help you choose the right life insurance in Singapore.
Read article
Term insurance covers you for a fixed period — typically 10 to 30 years — and pays a lump sum only if you die within that term. Whole life insurance covers you for your entire life and builds a cash value you can access later.
Read article
Most Singapore employees have group term life insurance through work — but many do not know the coverage limits, portability risks, or when they need their own individual policy.
Read article
Your complete guide to LIA Singapore — the industry body that voices the interests of members, addresses industry issues through engagement with stakeholders, and works with members to develop guidelines and codes of practice.
Read article
An honest, data-driven look at Singlife — MAS-licensed, digitally-native, and growing fast. Here's everything Singaporeans need to know before buying a policy.
Read article
Compare the right plan for your stage of life — clear premiums, payouts, and honest trade-offs.
Read article
Compare term CI, whole life CI, and multipay critical illness plans from AIA, Prudential, Great Eastern, and Singlife — with real premium data for Singapore residents.
Read article
Compare term CI, whole life CI, and multipay critical illness plans from AIA, Prudential, Great Eastern, and Singlife — with real premium data for Singapore residents.
Read article
Singlife Multipay Critical Illness II covers 135 conditions with up to 900% payout. Here's how it compares to AIA, Manulife, Prudential and FWD multi-pay CI plans.
Read article
A complete guide to buying and selling pre-owned insurance policies on Singapore's secondary market — how it works, what it costs, and whether it makes financial sense for you.
Read article
Complete guide to insurance nominations in Singapore. Learn the difference between revocable and trust nominations, how to nominate online since 2024, and why every policyholder needs one.
Read article
A plain-English comparison of every CI plan type available in Singapore — with real premium estimates, worked examples, and a decision framework.
Read article
Compare FWD, Singlife, Manulife, AIA, Prudential & NTUC Income — side by side, with real 2026 premium data.
Read article
6 Insurers • Term, Whole Life & Critical Illness • CPF Medisave Tips
Read article
Term, Whole Life, Critical Illness & DPS — What You Need, How Much Cover, and How to Buy
Read article
Compare AIA, Manulife, Singlife, Prudential and Great Eastern — prices, coverage, and our verdict for each type of buyer.
Read article
Get paid at diagnosis — not just at the final stage.
Read article
How multi-pay CI works, what stages are covered, and whether the higher premium makes sense for you.
Read article
Whole life premiums, cash value, best plans and the honest verdict — for Singapore residents in 2026.
Read article
TM Term Assure II, FlexiAssurance & FlexiCover compared — with real premium data and a plain-English verdict
Read article
Compare the best critical illness insurance plans in Singapore 2026. FWD Big 3 CI from S$198/yr, Manulife multi-pay, AIA Power Critical Care — premiums, conditions covered, and who should buy each plan.
Read article
Protect up to 75% of your salary if illness or injury stops you working — here's everything you need to know about DI insurance in Singapore.
Read article
Compare the best term life insurance plans in Singapore 2026. Real premium tables by age and insurer, how much cover you need, and a step-by-step buyer's guide.
Read article
A critical illness diagnosis can derail your finances in weeks. Critical illness insurance Singapore pays a tax-free lump sum on diagnosis — giving you cash to cover treatment…
Read article
A complete guide to the Dependants' Protection Scheme (DPS) — Singapore's CPF-linked group term life insurance covering millions of working Singaporeans.
Read article
Critical illness insurance Singapore is one of the most important financial safety nets you can have — yet most Singaporeans are dangerously underinsured.
Read article
The most cost-effective way to protect your family’s financial future — how term life works, how much coverage you need, and the best options available in Singapore.
Read articleFrequently Asked Questions
Is term life or whole life better in Singapore?
For most working adults, term life is better value — it provides 5–10x more coverage per dollar spent. Whole life only makes sense if you need permanent coverage (estate planning) or want a forced savings mechanism. The “buy term invest the rest” strategy historically outperforms whole life cash values over 20+ years.
How much does term life insurance cost in Singapore?
For a healthy 30-year-old male non-smoker, $500,000 of term life coverage (to age 65) typically costs $25–45/month depending on the insurer. Female rates are 15–20% lower. Smokers pay 2–3x more. DPI products on compareFIRST.sg are often the cheapest as they exclude agent commissions.
Should I cancel my whole life policy and switch to term?
This depends on how long you’ve held the policy. If you’re within the first 2–3 years, surrender charges are high but the sunk cost is small. If you’ve held it 10+ years, a significant cash value has built up. Run the numbers: compare remaining premiums vs current cash value vs your actual coverage needs. Never cancel existing coverage before new coverage is in force.
What riders should I add to my life insurance?
Consider Total Permanent Disability (TPD) and Critical Illness (CI) riders, as these cover scenarios where you can’t work but haven’t died. Early Critical Illness riders cover early-stage conditions. Waiver of Premium riders ensure your policy continues if you become disabled. Avoid accidental death riders — they only add limited value.
Part of the Insurance Singapore Guide
Also explore: Investment Insurance
Understand ILPs, endowments, and when direct investing beats insurance products.