Mapletree Pan Asia Commercial Trust (MPACT) 2026: Complete Investor Guide — N2IU DPU, Yield & Portfolio
SGX: N2IU | Sponsor: Mapletree Investments (Temasek) | Commercial & Retail REIT
Mapletree Pan Asia Commercial Trust (MPACT), formerly Mapletree Commercial Trust, is Singapore’s fifth-largest S-REIT by market capitalisation. Listed on SGX as N2IU, MPACT owns 18+ commercial and retail properties across Singapore, Hong Kong, Japan, South Korea, and China. It offers retail investors a quarterly distribution yield of approximately 6–7% (as at November 2026), CPF and SRS eligibility, and backing by Temasek-linked sponsor Mapletree Investments.
Not financial advice. All figures are for educational reference only. Data as at November 2026 unless noted. Past distributions do not guarantee future payouts.
Table of Contents
What Is MPACT (Mapletree Pan Asia Commercial Trust)?
Mapletree Pan Asia Commercial Trust — commonly known as MPACT — was formed on 3 August 2022 through the merger of Mapletree Commercial Trust (MCT) and Mapletree North Asia Commercial Trust (MNACT). The merger created one of the largest diversified commercial S-REITs in Asia, combining MCT’s premium Singapore office and retail portfolio with MNACT’s overseas commercial exposure across Hong Kong, China, Japan, and South Korea.
MPACT is managed by MPACT Management Ltd and sponsored by Mapletree Investments Pte Ltd, a wholly-owned subsidiary of Temasek Holdings. This blue-chip sponsorship provides MPACT with a right of first refusal (ROFR) over Mapletree’s pipeline of commercial properties across Asia — a meaningful competitive advantage for future acquisitions.
For Singapore investors, MPACT is best known for its crown jewel asset: VivoCity, the largest shopping mall in Singapore by net lettable area, located at HarbourFront. VivoCity consistently delivers strong shopper traffic and rental income, anchoring MPACT’s Singapore distribution. The REIT is eligible for CPF investment via CPFIS and SRS, making it accessible for Singaporean retirement planning.
Investors seeking broader S-REIT exposure can also consider the Singapore REIT ETF guide for a diversified basket approach.
Key Facts at a Glance
| Metric | Detail |
|---|---|
| SGX Ticker | N2IU |
| REIT Type | Commercial (Office & Retail) |
| Sponsor | Mapletree Investments (Temasek Holdings) |
| Approx. Share Price (Nov 2026) | S$1.20–S$1.35 |
| Estimated Annual DPU | ~7.4–7.7 Singapore cents/unit |
| Forward Distribution Yield | ~6.0–7.0% |
| Distribution Frequency | Quarterly |
| Financial Year End | 31 March |
| Approx. Gearing | ~39–41% (MAS 50% limit) |
| Number of Properties | 18+ properties |
| Countries | Singapore, Hong Kong, Japan, South Korea, China |
| CPF/SRS Eligible? | Yes (CPFIS-OA and SRS) |
| Approx. Market Cap | S$9–11 billion |
Source: SGX, MPACT announcements, company data | Figures approximate as at November 2026. Verify current figures on SGX.com before investing.
MPACT DPU History & Distribution Yield
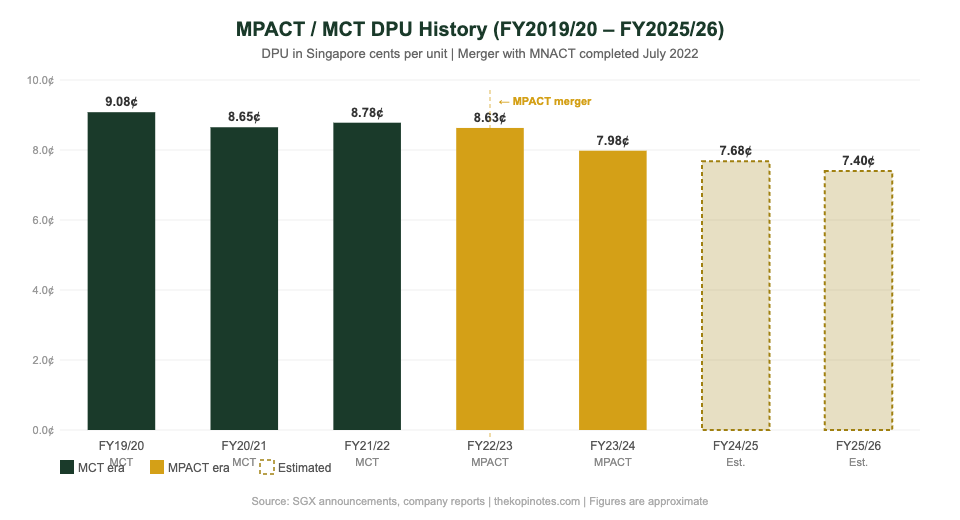
MPACT’s DPU trend reflects two distinct chapters: the MCT era (pre-merger) characterised by stable Singapore-focused income, and the post-merger MPACT era where rising interest rates and weaker overseas markets have compressed distributions. For detailed quarterly breakdowns, see the MPACT dividend history article.
| Financial Year | Annual DPU (cents) | YoY Change | Notes |
|---|---|---|---|
| FY2019/20 | 9.08¢ | — | MCT era |
| FY2020/21 | 8.65¢ | ▼ 4.7% | COVID impact |
| FY2021/22 | 8.78¢ | ▲ 1.5% | Recovery; last MCT year |
| FY2022/23 | 8.63¢ | ▼ 1.7% | MPACT post-merger |
| FY2023/24 | 7.98¢ | ▼ 7.5% | Rate pressure, FX drag |
| FY2024/25 (est.) | ~7.68¢ | ▼ 3.8% | Continued pressure |
| FY2025/26 (est.) | ~7.40¢ | ▼ ~3.6% | Rate cuts may stabilise |
Source: SGX announcements, MPACT/MCT annual reports | Estimates are indicative only and not forward guidance. Verify on MPACT’s investor relations page.
Why Has MPACT’s DPU Declined?
Three structural headwinds have weighed on MPACT’s DPU since the 2022 merger. First, rising global interest rates dramatically increased the REIT’s financing costs — MPACT carries significant debt to fund its 18+ property portfolio, and each 50 basis point rate increase eats into distributable income. Second, the overseas portfolio (particularly Festival Walk in Hong Kong and the China assets) has underperformed due to weaker consumer sentiment and unfavourable FX movements — the HKD, CNY, JPY, and KRW have all weakened against the SGD, reducing the SGD value of overseas distributions. Third, the Singapore office market faced softer demand from flexible work arrangements, though VivoCity’s retail performance has remained resilient.
The MPACT share price analysis provides a detailed look at how these factors have influenced unit price performance.
MPACT Portfolio: Properties & Geography
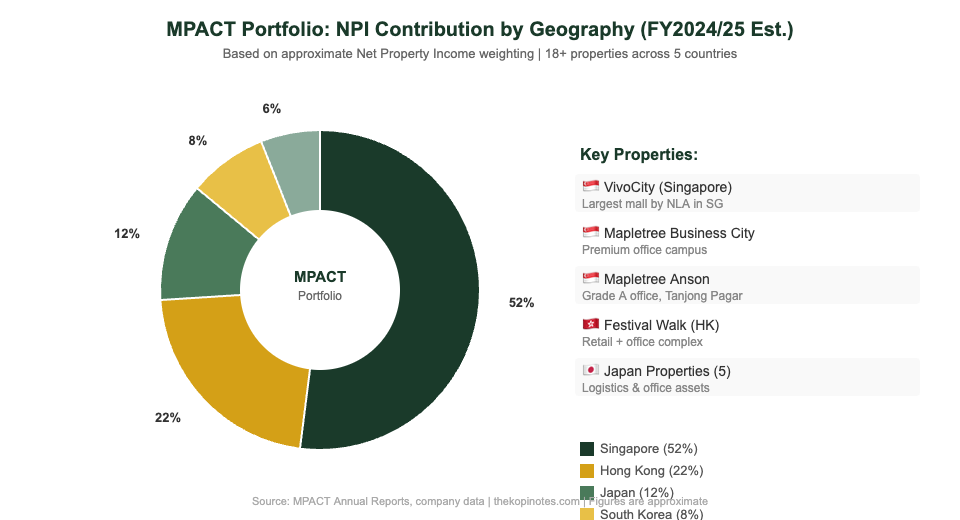
MPACT’s 18+ properties span five countries, covering approximately 11.4 million square feet of gross floor area. The portfolio is split between Singapore (~52% of NPI) and overseas markets (~48%). This pan-Asian diversification was the central rationale for the MCT/MNACT merger, though it has also introduced FX and geopolitical risk that pure Singapore REITs avoid.
Singapore Portfolio (Core Income Driver)
| Property | Type | Location | Highlight |
|---|---|---|---|
| VivoCity | Retail mall | HarbourFront | Largest mall in SG by NLA; ~1M sqft; 300+ tenants |
| Mapletree Business City I & II | Business park | Alexandra | ~2.4M sqft campus; Grade A tenants |
| Mapletree Anson | Grade A office | CBD / Tanjong Pagar | 178,000 sqft; premium CBD office |
| PSA Building | Office | Tanjong Pagar | Anchor tenants: PSA Corp |
| BMLH | Office | HarbourFront | Bank of America Merrill Lynch HarbourFront |
Overseas Portfolio (Growth Optionality)
The overseas portfolio covers 13+ properties: Festival Walk (HK — a premium retail/office complex), Gateway Plaza and Sandhill Plaza (Beijing and Shanghai, China), five Japanese properties (offices and business parks), and two South Korean assets. The HK and China assets have been the primary source of DPU drag since 2022 due to weaker consumption and FX headwinds, though Japan’s hospitality recovery has provided a partial offset.
Investors interested in broader S-REIT exposure can explore the best S-REITs in Singapore 2026 comparison to see how MPACT stacks up against peers.
Financial Analysis: Gearing, NPI & NAV
Understanding MPACT’s balance sheet is critical for assessing distribution sustainability and growth capacity. Here are the key financial metrics Singapore investors should track:
| Financial Metric | Approximate Value | What It Means |
|---|---|---|
| Aggregate Leverage (Gearing) | ~39–41% | Below MAS 50% limit; moderate headroom for acquisitions |
| Approx. NAV per Unit | ~S$1.65–1.75 | Units trade at ~25% discount to NAV — potential value |
| Price-to-NAV | ~0.73–0.78x | Historically attractive for long-term investors |
| Weighted Avg. All-In Cost of Debt | ~3.8–4.2% | Rising debt costs squeezing distributable income |
| Interest Cover Ratio | ~3.0–3.5x | Comfortable; NPI covers interest ~3x over |
| Total Assets (approx.) | ~S$17–19 billion | One of Asia’s largest commercial REIT portfolios |
Source: MPACT quarterly results, SGX filings | Figures approximate as at November 2026
MPACT vs Peers: A Quick Comparison
Compared to pure-play Singapore commercial REITs like CapitaLand Integrated Commercial Trust (CICT) and Frasers Centrepoint Trust (FCT), MPACT’s overseas exposure introduces both opportunity and risk. CICT trades closer to NAV due to its pure Singapore focus, while MPACT’s pan-Asian diversification has historically traded at a wider discount. If interest rates moderate and Festival Walk recovers, MPACT’s discount could narrow — rewarding patient investors with both yield and capital appreciation. For passive income planning, see our passive income Singapore 2026 guide.
Investment Case: Pros & Cons
| Bull Case (Reasons to Buy) | Bear Case (Risks to Watch) |
|---|---|
| VivoCity dominance: Singapore’s most visited mall with consistent footfall — the retail anchor that keeps distributions stable regardless of overseas weakness. | DPU compression: Annual DPU has declined from 9.08c (FY2019/20) to an estimated ~7.4c (FY2025/26) — a 19% fall over six years that reflects structural headwinds. |
| Deep discount to NAV: Trading ~25% below NAV (~S$1.65–1.75/unit) offers capital appreciation potential if sentiment improves or rates fall. | FX headwinds: ~48% overseas portfolio means HKD, CNY, JPY, KRW weakness directly erodes SGD-denominated DPU — difficult to hedge cheaply at REIT level. |
| Temasek-linked sponsor: Mapletree Investments pipeline provides high-quality ROFR assets; sponsor credibility reduces governance risk vs smaller REITs. | Office softness: MBC and Mapletree Anson face headwinds from hybrid work trends and slower global business expansion into Singapore. |
| Rate cut tailwind: MPACT is a beneficiary of falling global interest rates — every 50 bps cut reduces interest expense and can directly lift DPU by ~0.2–0.3c. | Geopolitical risk: HK and China asset values could face further pressure from US-China trade tensions and local economic policy changes. |
| CPF/SRS eligibility: One of the few large-cap S-REITs where you can invest using CPF OA funds — reduces out-of-pocket cost and boosts effective return for CPF investors. | High gearing: At ~40% gearing, acquisition headroom is limited. Any material increase in interest rates or property value write-downs could push leverage higher. |
MPACT is best suited for investors with a 3–5 year time horizon who can tolerate short-term DPU volatility in exchange for a discounted entry into a blue-chip commercial portfolio. If you prefer a purely Singapore-focused commercial REIT, CICT may be a more defensive choice.
How to Buy MPACT (N2IU) in Singapore
MPACT (N2IU) trades on the Singapore Exchange (SGX) and can be purchased through any SGX-connected brokerage. It is eligible for CPF Investment Scheme (Ordinary Account) and Supplementary Retirement Scheme (SRS) purchases. Here are the main platforms Singapore investors use:
| Platform | Commission | Best For |
|---|---|---|
| moomoo SG | From 0.03% (min S$0.99) | Low-cost SGX trading, real-time data |
| FSMOne | 0.08% (min S$10) | CPF/SRS, dividend reinvestment |
| Syfe Trade | From S$0.99 flat | Beginner-friendly, low minimums |
| Endowus | Fund-based access | CPF/SRS REIT fund exposure, hands-off |
For referral bonuses: use the FSMOne referral code for CPF/SRS investing, or the Syfe referral code and sign-up bonus for Syfe Trade access. For hands-off REIT fund investing via CPF, consider the Endowus referral code.
Step-by-Step: Buying MPACT via CPF (CPFIS-OA)
To invest your CPF OA funds in MPACT, you first need to set up a CPF Investment Account through a CPFIS-authorised agent bank (DBS, OCBC, or UOB). Once linked, transfer your CPF-OA investible savings to your brokerage’s CPF investment account and place a buy order for N2IU on SGX. Note that you must retain at least S$20,000 in your OA before investing, and distributions from MPACT bought via CPF are credited back to your CPF OA.
Frequently Asked Questions (FAQ)
What is Mapletree Pan Asia Commercial Trust (MPACT)?
What is MPACT's current dividend yield (N2IU yield)?
Is MPACT eligible for CPF and SRS investments?
Why has MPACT's DPU declined since the 2022 merger?
How does MPACT compare to CapitaLand Integrated Commercial Trust (CICT)?
What is MPACT's gearing and what does it mean for investors?
Where can I find MPACT's latest share price and announcements?
Start Investing in S-REITs Today
Whether you’re buying MPACT for yield, diversification, or CPF income — the right brokerage makes a difference. Use these referral codes from The Kopi Notes for exclusive sign-up bonuses:
Not financial advice. The Kopi Notes may earn referral commissions. Always do your own research before investing.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.