Mapletree Logistics Trust Dividend (M44U): DPU History, Yield & Payment Dates 2026
Mapletree Logistics Trust (SGX: M44U), Singapore’s first and largest pan-Asia logistics REIT, has paid uninterrupted semi-annual distributions since its 2005 IPO. With a DPU of approximately 8.15 cents for FY2026 (year ending March 2026) and a trailing yield of around 5.3% at current prices, MLT remains one of the most consistent dividend payers in the S-REIT space. This guide covers the complete DPU history, upcoming payment dates, and what investors need to know.
Not financial advice. All figures are for educational reference only. Data as at November 2026 unless noted. Always verify DPU and yield figures from official SGX announcements before investing.
MLT Dividend Overview & Key Stats
Mapletree Logistics Trust listed on SGX in April 2005, making it one of Singapore’s most established REITs. It owns industrial and logistics properties across nine markets: Singapore, Hong Kong, China, Japan, South Korea, Australia, Malaysia, Vietnam, and India. As at the latest reporting period, MLT manages approximately 190 properties with a total AUM of around S$13–14 billion.
The trust distributes income semi-annually — an interim distribution (covering April–September) paid in November/December, and a final distribution (covering October–March) paid in May/June. This twice-yearly cadence suits income investors seeking predictable cash flow from their passive income Singapore strategy.
| Metric | Value (Nov 2026) |
|---|---|
| SGX Ticker | M44U |
| ISIN | SG1S55021927 |
| Sponsor | Mapletree Investments Pte Ltd |
| FY2026 DPU (est.) | ~8.15 Singapore cents |
| Distribution Frequency | Semi-annual |
| Approx. Trailing Yield | ~5.3% (at ~S$1.52) |
| Gearing Ratio | ~37–39% |
| No. of Properties | ~190 |
| Total AUM | ~S$13–14 billion |
| Fiscal Year End | 31 March |
Source: Mapletree Logistics Trust SGX announcements; share price indicative. Verify at SGX.com before investing.
MLT is managed by Mapletree Logistics Trust Management Ltd, a wholly owned subsidiary of Mapletree Investments — the same sponsor behind Mapletree Industrial Trust (ME8U), Mapletree Commercial Trust (now MPACT, N2IU), and Mapletree Pan Asia Commercial Trust (N2IU). This strong sponsor backing provides access to a deep pipeline of logistics assets across Asia-Pacific.
DPU History FY2015–FY2026
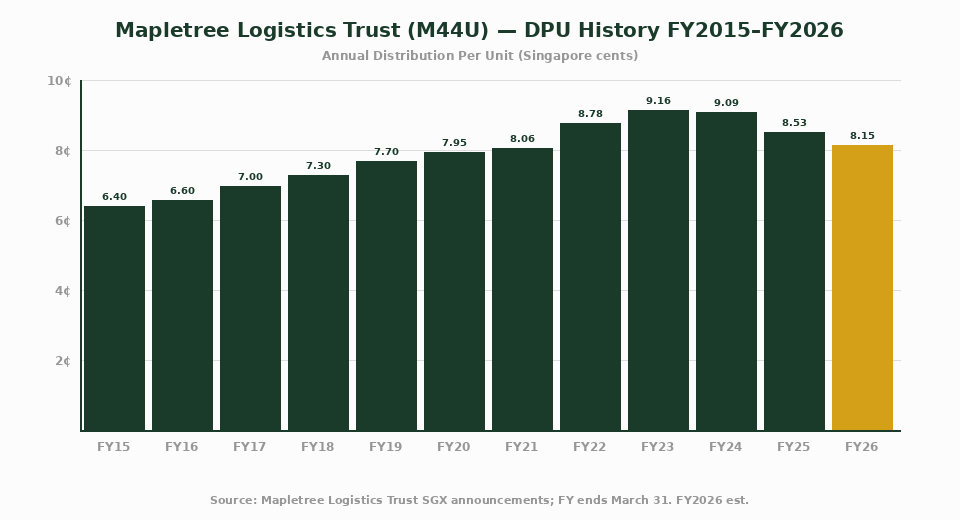
MLT’s distribution per unit grew steadily from FY2015 through FY2023, driven by asset acquisitions, occupancy improvements, and rental reversions. FY2024 and FY2025 saw modest DPU compression as rising interest rates increased borrowing costs and some markets (particularly China) faced leasing headwinds. Here is the full DPU history (fiscal year ending March 31):
| Fiscal Year | Period | 1H DPU (¢) | 2H DPU (¢) | Full Year DPU (¢) | YoY Change |
|---|---|---|---|---|---|
| FY2015 | Apr 14–Mar 15 | 3.20 | 3.20 | 6.40 | — |
| FY2016 | Apr 15–Mar 16 | 3.30 | 3.30 | 6.60 | +3.1% |
| FY2017 | Apr 16–Mar 17 | 3.50 | 3.50 | 7.00 | +6.1% |
| FY2018 | Apr 17–Mar 18 | 3.60 | 3.70 | 7.30 | +4.3% |
| FY2019 | Apr 18–Mar 19 | 3.80 | 3.90 | 7.70 | +5.5% |
| FY2020 | Apr 19–Mar 20 | 4.14 | 3.81 | 7.95 | +3.2% |
| FY2021 | Apr 20–Mar 21 | 3.99 | 4.07 | 8.06 | +1.4% |
| FY2022 | Apr 21–Mar 22 | 4.25 | 4.53 | 8.78 | +8.9% |
| FY2023 | Apr 22–Mar 23 | 4.55 | 4.61 | 9.16 | +4.3% |
| FY2024 | Apr 23–Mar 24 | 4.57 | 4.52 | 9.09 | −0.8% |
| FY2025 | Apr 24–Mar 25 | 4.27 | 4.26 | 8.53 | −6.2% |
| FY2026 (est.) | Apr 25–Mar 26 | 4.07 | 4.08 | ~8.15 | ~−4.5% |
Source: Mapletree Logistics Trust SGX announcements & investor relations. FY2026 figures are estimates pending final announcement. All DPUs in Singapore cents per unit. Verify figures at investor.mapletree.com.sg before making investment decisions.
Key observation: MLT delivered uninterrupted DPU growth from FY2015 through FY2023 — a remarkable 9-year growth streak through COVID-19 and multiple market cycles. The DPU decline since FY2024 reflects higher interest costs (as interest rate hedges rolled off at higher rates) and leasing challenges in China, rather than fundamental asset deterioration. For the FY2027 outlook, see our detailed Mapletree Logistics Trust FY2027 DPU forecast.
Dividend Yield Analysis
MLT’s dividend yield fluctuates with both changes in DPU and movements in the unit price. At the current share price of approximately S$1.52 (as at November 2026), the trailing yield based on the estimated FY2026 DPU of ~8.15 cents is approximately 5.3–5.4%. This represents a meaningful discount to the REIT’s historical price-to-NAV ratio.
| Share Price (S$) | Yield on FY2026 DPU (~8.15¢) | Yield on FY2025 DPU (~8.53¢) | Yield on FY2023 Peak DPU (~9.16¢) |
|---|---|---|---|
| S$1.35 | 6.04% | 6.32% | 6.78% |
| S$1.45 | 5.62% | 5.88% | 6.32% |
| S$1.52 | 5.36% | 5.61% | 6.03% |
| S$1.60 | 5.09% | 5.33% | 5.73% |
| S$1.75 | 4.66% | 4.87% | 5.23% |
Source: TKN calculations based on estimated/reported DPU data. Share price as at November 2026 (indicative). Not investment advice.
MLT currently trades at approximately 0.78–0.82x NAV (net asset value per unit ~S$1.85–1.90), reflecting broader S-REIT valuation compression since 2022 when interest rates rose sharply. For income investors buying at current levels, the yield-on-cost is locked in at ~5.3–5.4% on FY2026 DPU. If rates normalise and unit prices recover toward NAV, total returns would be enhanced. For more context on how MLT compares on a share price basis, see our Mapletree Logistics Trust share price analysis.
Payment Schedule & Ex-Dividend Dates
MLT announces distributions twice per fiscal year. The typical annual calendar follows this pattern:
| Distribution | Results Period | Results Announced | Ex-Dividend Date | Payment Date |
|---|---|---|---|---|
| 1H Interim (FY2026) | Apr–Sep 2025 | Oct/Nov 2025 | Nov 2025 | Nov/Dec 2025 |
| 2H Final (FY2026) | Oct 2025–Mar 2026 | Apr/May 2026 | May 2026 | May/Jun 2026 |
| 1H Interim (FY2027) | Apr–Sep 2026 | Oct/Nov 2026 | Nov 2026 | Nov/Dec 2026 |
| 2H Final (FY2027) | Oct 2026–Mar 2027 | Apr/May 2027 | May 2027 | May/Jun 2027 |
Source: Mapletree Logistics Trust SGX announcements. Exact dates vary; check the latest SGX announcements for confirmed ex-dividend and payment dates.
Important: To qualify for a distribution, you must hold M44U units before the ex-dividend date. Purchasing on or after the ex-dividend date means you will not receive that particular payout. SGX trades settle on a T+2 basis, so you need to buy at least 2 business days before the ex-dividend date to be on the register.
MLT announces results and distributions via SGXNet. Investors can track upcoming announcements on the official Mapletree Logistics Trust investor relations page or the SGX M44U page.
What Drives MLT’s Dividend
Understanding the key drivers of MLT’s DPU helps investors assess whether the distribution is likely to grow, stabilise, or decline over the medium term.
1. Rental Income from Logistics Properties
MLT’s income is anchored by long-term leases across its ~190 logistics properties. Singapore properties (around 15–20% of AUM) provide the most stable income given prime land scarcity and high demand from e-commerce and third-party logistics (3PL) operators. Japan and Australia have contributed positively with favourable rental reversions. The largest drag in recent years has come from China, where supply surplus and slower economic growth have pressured occupancy and rents.
2. Interest Rate & Debt Management
MLT’s borrowing costs are a primary DPU driver. With a gearing ratio of approximately 37–39% and total borrowings of around S$5–6 billion, even a 1% rise in average financing costs reduces annual DPU by roughly 0.5–0.8 cents. During FY2024–FY2026, the trust faced headwinds as interest rate hedges rolled off at higher prevailing rates. As rates normalise — particularly if the US Federal Reserve continues its easing cycle — refinancing at lower costs could add meaningfully to DPU.
3. Foreign Currency Exposure
MLT generates income in JPY (Japan), AUD (Australia), HKD (Hong Kong), CNY (China), KRW (South Korea), MYR (Malaysia), and VND (Vietnam). These are translated back to SGD for distribution. MLT hedges a significant portion of its distributions, but residual FX exposure means a weakening JPY or AUD can modestly reduce reported DPU even if underlying rents are stable.
4. Asset Recycling & Acquisitions
MLT regularly acquires yield-accretive assets from its sponsor pipeline and disposes of non-core properties. Acquisitions that are funded prudently (at or below NAV) and are earnings-accretive contribute positively to DPU over time. The trust’s rights issues (including the 2023 preferential offering) expanded its portfolio but diluted per-unit distributions in the short term while growing total distributable income.
MLT vs Peer S-REIT Yields
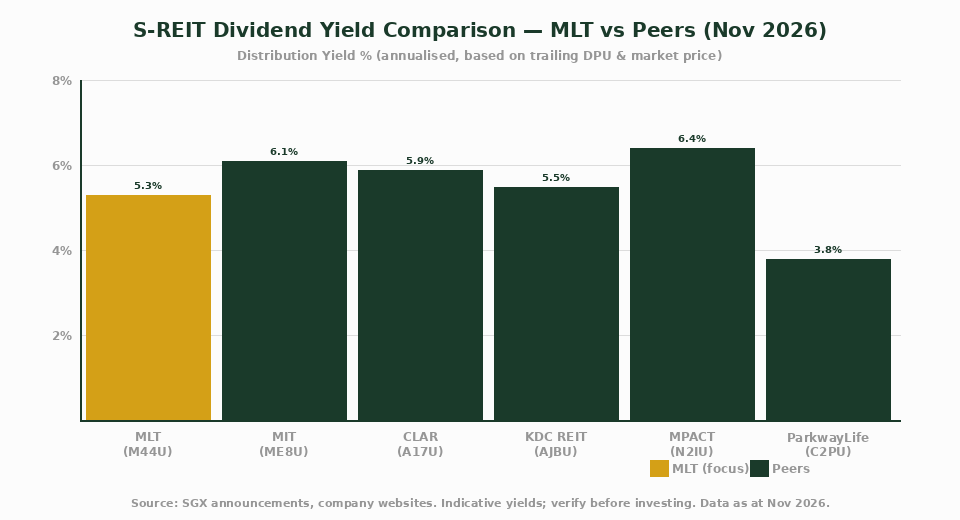
How does MLT’s ~5.3% yield compare with other S-REITs? The chart below shows indicative trailing yields across six major S-REITs as at November 2026. MLT’s yield sits in the middle of the pack — lower than office/commercial/hospitality REITs with higher risk premiums, but above the more defensive healthcare REIT (ParkwayLife).
| REIT | SGX Ticker | Sub-sector | Approx. Yield (Nov 2026) | Gearing |
|---|---|---|---|---|
| Mapletree Logistics Trust | M44U | Logistics / Industrial | ~5.3% | ~38% |
| Mapletree Industrial Trust | ME8U | Industrial / Data Centres | ~6.1% | ~38% |
| CapitaLand Ascendas REIT | A17U | Industrial / Logistics | ~5.9% | ~37% |
| Keppel DC REIT | AJBU | Data Centres | ~5.5% | ~34% |
| MPACT (Mapletree Pan Asia) | N2IU | Commercial / Office | ~6.4% | ~40% |
| ParkwayLife REIT | C2PU | Healthcare | ~3.8% | ~35% |
Source: SGX announcements & company websites. Indicative trailing yields; verify at time of investment. Data as at November 2026. Gearing ratios approximate.
MLT’s lower yield relative to MIT and MPACT reflects its more defensive logistics sub-sector — logistics assets benefit from structural e-commerce tailwinds and tend to have strong tenant retention. For a broader view of the highest-yielding S-REITs, see our best S-REITs in Singapore 2026 guide.
Is the MLT Dividend Sustainable?
Investors naturally ask whether MLT’s current DPU level (~8.15 cents estimated for FY2026) can be maintained or whether further cuts are on the horizon. Here is an honest assessment of the factors:
Bull Case: DPU Stabilisation & Recovery
- Interest rate tailwind: As global central banks (including the US Federal Reserve) continue easing, MLT’s refinancing costs should decline, adding back ~0.3–0.6 cents to DPU over 2–3 years as hedges roll at lower rates.
- China bottoming: Occupancy in China has shown early signs of stabilisation. Any improvement in Chinese logistics demand — driven by domestic consumption growth or further stimulus — would be a direct positive for MLT’s DPU.
- Sponsor pipeline: Mapletree Investments has a large pipeline of logistics assets in Japan, Australia, and Southeast Asia that could be injected at accretive valuations.
- 19-year track record: MLT has never cut its dividend to zero and has demonstrated resilience through the Global Financial Crisis (2008–09), the Singapore property cooling measures, and COVID-19.
Bear Case: Risks to Watch
- China exposure: Approximately 25–30% of MLT’s AUM is in China. Prolonged weakness in Chinese logistics rents or occupancy remains the key downside risk.
- Gearing: At ~38% gearing, MLT has limited debt headroom before approaching MAS’s 50% regulatory limit. Any significant new acquisition would likely require equity fundraising (dilutive to per-unit metrics).
- FX risk: A materially weaker JPY or AUD could reduce translated DPU even if underlying assets perform well.
- Refinancing at higher rates: While the direction of rates is downward, any prolonged “higher for longer” scenario would delay DPU recovery.
Overall assessment: MLT’s distribution appears broadly sustainable at current levels. The ~8 cents per year DPU floor looks well-supported by MLT’s high-quality, diversified portfolio, strong sponsor, and proven management track record. DPU growth back toward the ~9 cents peak depends on China recovery and interest rate normalisation. For the detailed 3-scenario DPU model, see our dedicated MLT FY2027 DPU forecast article.
How to Buy M44U in Singapore
M44U trades on the Singapore Exchange (SGX) in SGD. Singapore retail investors can purchase MLT units through any SGX-licensed broker. The process is straightforward:
- Open a brokerage account and CDP (Central Depository) account (or use a custodian account)
- Fund your account in SGD
- Search for “M44U” on your broker’s platform
- Place a buy order (consider limit orders during volatile sessions)
- Units settle on T+2 basis
Popular platforms for buying S-REITs:
- FSMOne — competitive commissions for SGX trades (FSMOne referral code P0544985 for new accounts)
- moomoo Singapore — attractive first-year commissions and real-time SGX data (moomoo referral code)
- Endowus — if you prefer a managed approach using CPF OA funds, Endowus offers S-REIT exposure via curated portfolios (Endowus referral code 2V343)
For a comparison of the Singapore REIT ETF options (such as the Lion-Phillip S-REIT ETF) vs buying individual REITs like MLT, see our dedicated guide. ETFs offer instant diversification but dilute concentration in strong individual REITs like MLT.
Frequently Asked Questions
What is Mapletree Logistics Trust's current dividend yield?
When does Mapletree Logistics Trust pay dividends?
Has Mapletree Logistics Trust ever cut its dividend?
Is Mapletree Logistics Trust dividend tax-free for Singaporeans?
How does MLT's DPU compare to Mapletree Industrial Trust?
Can I use CPF to invest in Mapletree Logistics Trust?
What is MLT's distribution per unit for FY2027?
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.