iREIT Global Complete Guide 2026 (SGX: UD1U): European REIT, Yield & Analysis
Singapore's only pure-play European REIT — office parks, logistics, and light industrial assets across Germany, Netherlands, Spain, and France, sponsored by Tikehau Capital.
iREIT Global (SGX: UD1U) is Singapore's only pure-play European REIT, providing access to office parks, light industrial, and logistics assets across Germany, the Netherlands, Spain, and France — all sponsored by French alternative asset manager Tikehau Capital. Offering a distribution yield of approximately 8–9% in SGD terms, it gives Singapore investors European real estate diversification through a familiar SGX-listed vehicle, albeit with higher currency and gearing risk than most S-REITs.
Not financial advice. All figures are for educational reference only. Data as at November 2026 unless noted.
What Is iREIT Global?
iREIT Global (SGX: UD1U) was listed on the Singapore Exchange in October 2014, making it Singapore's first — and to date only — REIT focused exclusively on European commercial real estate. Sponsored by Tikehau Capital, one of Europe's largest alternative asset management groups with over €40 billion in assets under management, iREIT Global is externally managed by IREIT Global Group Pte. Ltd.
Unlike most S-REITs that derive rental income in SGD or other Asian currencies, iREIT Global's income streams are entirely denominated in Euros (EUR). This means that while distributions are paid out in SGD, the actual SGD amount received fluctuates with the EUR/SGD exchange rate — a critical dynamic that every Singapore investor must factor into their analysis.
The REIT's portfolio spans office parks, light industrial facilities, and logistics centres in Western Europe. Its primary markets are Germany (the largest single-country allocation), the Netherlands, Spain, and France. Most assets are freehold or long-leasehold, underpinned by institutional-quality tenants on relatively long lease terms. As part of the broader best S-REITs in Singapore 2026 landscape, iREIT Global occupies a distinctive niche as the European diversifier.
Portfolio Overview
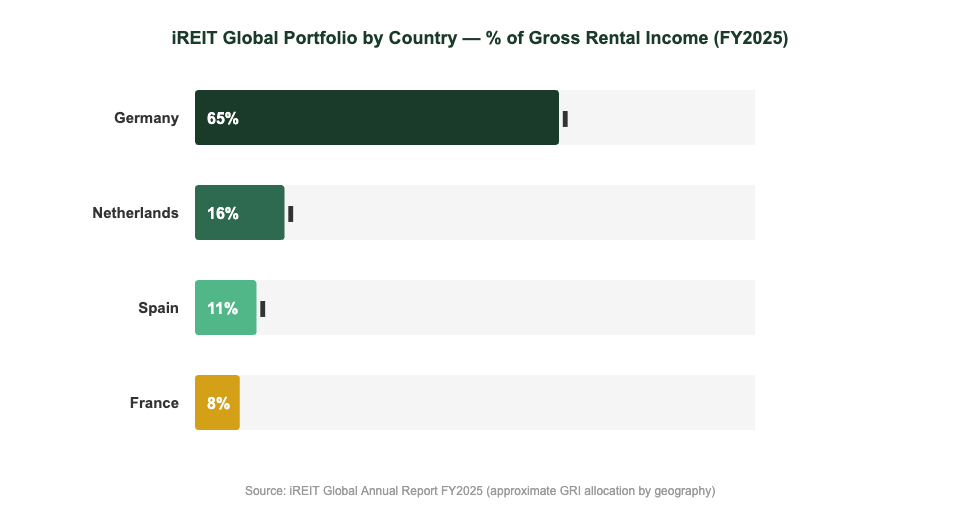
As at FY2025, iREIT Global's portfolio comprises approximately 11 properties across four European countries. Germany remains the dominant market, contributing roughly 65% of gross rental income (GRI), anchored by well-located office parks in cities including Bonn, Darmstadt, Berlin, and Hamburg. The Netherlands and Spain each contribute a meaningful share of GRI through modern logistics and office assets respectively, while France rounds out the European diversification with assets in the Greater Paris area.
The portfolio is weighted towards quality, long-term leases with creditworthy tenants — including German telecommunications group Deutsche Telekom and several large-cap European corporates. The Weighted Average Lease Expiry (WALE) has historically been maintained above 4 years, providing reasonable near-term income visibility.
| Country | Key Cities | Asset Type | Approx. % of GRI |
|---|---|---|---|
| Germany | Bonn, Darmstadt, Berlin, Hamburg | Office Parks, Light Industrial | ~65% |
| Netherlands | Amsterdam Region | Logistics, Office | ~16% |
| Spain | Seville, Madrid | Office Parks | ~11% |
| France | Greater Paris | Office, Mixed Use | ~8% |
Source: iREIT Global Annual Report FY2025 (approximate GRI allocation by geography). Figures are rounded.
Yield & DPU Analysis
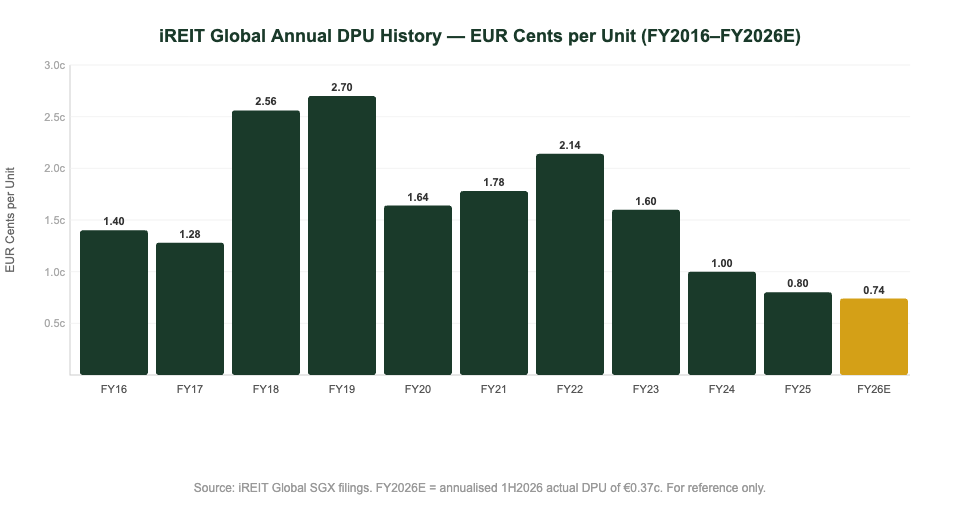
iREIT Global's distribution history tells the story of a REIT navigating both macro headwinds and structural challenges. DPU peaked at approximately EUR 2.70 cents per unit in FY2019, before the COVID-19 pandemic reduced income in FY2020. DPU recovered partially in FY2021–FY2022, then declined sharply as European office market conditions softened, interest rates rose, and elevated gearing amplified the impact on distributable income.
As at 1H2026, iREIT Global declared a DPU of EUR 0.37 cents — representing a 48% decline year-on-year as leverage rose to 45.5% and financing costs increased. On an annualised basis, the FY2026E DPU is approximately EUR 0.74 cents per unit.
At the prevailing EUR/SGD exchange rate of approximately 1.49–1.52, an annual DPU of EUR 0.74 cents translates to approximately SGD 1.10–1.13 cents per unit. At a share price of around SGD 0.13–0.14 per unit (as at November 2026), the implied distribution yield is approximately 8–9%. For the complete dividend track record from 2014 to 2026, refer to the iREIT Global dividend history article, and for forward scenarios, see the iREIT Global FY2027 DPU forecast.
Financial Metrics at a Glance
| Metric | Value (as at November 2026) |
|---|---|
| SGX Ticker | UD1U |
| Share Price | ~SGD 0.13–0.14 |
| Distribution Yield | ~8–9% |
| Annualised DPU (FY2026E) | ~EUR 0.74¢ per unit |
| Gearing Ratio | 45.5% (high — approaching regulatory cap) |
| NAV per Unit | ~SGD 0.19–0.21 |
| Price-to-NAV | ~0.65–0.70x (significant discount) |
| Number of Properties | ~11 properties |
| WALE | ~4–5 years |
| Currency of Distributions | SGD (income earned in EUR) |
Source: iREIT Global 1H2026 SGX announcement. Share price and yield are approximate as at November 2026. All figures for reference only.
Key Risks for Singapore Investors
iREIT Global's elevated yield relative to other S-REITs reflects several genuine risks that investors must weigh carefully. This is not a low-risk dividend stock — it is a higher-yielding, higher-risk holding best suited to experienced investors with a clear view on European real estate and the EUR/SGD exchange rate.
1. EUR/SGD Currency Risk. Since all rental income is in Euros, any weakening of EUR against SGD directly reduces the SGD value of distributions. The EUR/SGD pair has declined from approximately 1.65 in 2021 to around 1.49–1.52 in late 2026, reducing distributions by over 10% in SGD terms compared to the peak rate period. If EUR weakens further, SGD DPU will fall even without any change in the underlying EUR income.
2. High Gearing Ratio. At 45.5%, iREIT Global's gearing is among the highest in the S-REIT sector. The MAS regulatory cap is 50% (for REITs with a credit rating). Elevated leverage amplifies sensitivity to both property valuation declines and interest rate movements. If European property values fall further, gearing could breach 50%, forcing the REIT to undertake a rights issue or asset disposal at potentially unfavourable prices.
3. European Office Market Headwinds. Post-pandemic structural shifts towards hybrid working have reduced demand for traditional office space, particularly in secondary European office markets. While iREIT Global's assets are mostly in well-located submarkets with established tenants, vacancy risk and downward rental reversions remain genuine concerns at lease expiry.
4. Refinancing Risk. With elevated gearing and a portion of debt maturing in coming years, refinancing at higher European interest rates could further compress distributable income and DPU.
5. Concentration Risk. Germany (~65% of GRI) means iREIT Global is significantly exposed to the German commercial real estate market, which faced sharp valuation declines in 2024–2026 as the German economy slowed and office demand softened.
How to Buy iREIT Global in Singapore
iREIT Global (UD1U) trades on the Singapore Exchange (SGX) in SGD, making it straightforward to purchase through any Singapore-based brokerage account. The minimum trading lot is 100 units.
Step-by-Step Buying Process:
- Open a brokerage account with an SGX-eligible broker (moomoo, FSMOne, IBKR, DBS Vickers, etc.)
- Fund your account in SGD
- Search for ticker UD1U on the SGX main board
- Place a buy order — minimum 1 lot (100 units); as at November 2026, 1 lot costs approximately SGD 13–14
- Distributions in SGD are credited semi-annually to your designated bank account after each ex-dividend date
Is iREIT Global SRS-eligible? Yes — iREIT Global can be purchased using SRS (Supplementary Retirement Scheme) funds via brokers that support SRS equity purchases, such as DBS Vickers, OCBC Securities, and UOB Kay Hian. This can be a tax-efficient way to access the higher yield while reducing taxable income.
Is iREIT Global CPF-investable? No — iREIT Global is not on the CPF Investment Scheme (CPFIS) approved list as at 2026. CPF funds cannot be used to purchase UD1U.
For broker sign-up promotions, use our FSMOne referral code (P0544985) for discounted brokerage fees. See our moomoo Singapore review for the latest moomoo cash voucher promotions and account opening steps. For international portfolios and larger trades, consider IBKR for its competitive SGX commissions.
Verdict: Is iREIT Global Worth Buying in 2026?
iREIT Global occupies a unique niche in the S-REIT sector: it is the only SGX-listed REIT offering exposure to European commercial real estate in a simple, SGD-denominated wrapper. The ~8–9% distribution yield looks attractive relative to most blue-chip S-REITs, and the 30–35% P/NAV discount suggests the market has priced in a lot of bad news already.
However, that yield and discount come with meaningful strings attached: a gearing ratio approaching the regulatory ceiling, persistent EUR/SGD headwinds, an European office market still navigating structural change, and a DPU trend that has been in decline since 2022. These are not abstract risks — they have already resulted in a 48% year-on-year DPU cut in 1H2026.
iREIT Global is best suited to: Income investors comfortable with higher risk who want European diversification; tactical investors with a constructive EUR/SGD view; and experienced REIT investors who closely monitor gearing and lease expiry profiles.
Consider alternatives if you: Need a stable, predictable SGD dividend (see our best S-REITs in Singapore 2026 guide for lower-risk options); have a low risk appetite; or are using CPF funds.
For modelling how iREIT Global fits into a broader passive income strategy, use the Singapore retirement calculator to project your target income. And for further diversification into the REIT space via ETFs, see the Singapore REIT ETF guide for a lower-risk, basket approach.
Disclaimer: This article is for informational and educational purposes only. It does not constitute financial advice. All investment decisions should be made based on your own research and risk tolerance. Past distributions do not guarantee future returns. Data as at November 2026.
Frequently Asked Questions
What is iREIT Global and where is it listed?
iREIT Global (SGX ticker: UD1U) is a Singapore-listed REIT that owns European commercial real estate — primarily office parks, light industrial, and logistics assets across Germany, the Netherlands, Spain, and France. It was listed on the SGX Main Board in October 2014 and is sponsored by Tikehau Capital, a French alternative asset manager. It is currently the only SGX-listed REIT with an exclusively European portfolio.
What is iREIT Global's current distribution yield?
As at November 2026, iREIT Global's distribution yield is approximately 8–9%, based on an annualised FY2026E DPU of approximately EUR 0.74 cents per unit (derived from the 1H2026 actual DPU of EUR 0.37 cents) and a share price of around SGD 0.13–0.14. Note that the SGD value of distributions varies with the EUR/SGD exchange rate. Always check the latest SGX announcements for the most current figures before investing.
Can I buy iREIT Global with CPF or SRS funds?
iREIT Global (UD1U) is not on the CPF Investment Scheme (CPFIS) approved list as at 2026, so CPF funds cannot be used to purchase it. However, iREIT Global is SRS-eligible — you can buy it using SRS (Supplementary Retirement Scheme) funds through brokers such as DBS Vickers, OCBC Securities, and UOB Kay Hian. Using SRS for iREIT Global can be tax-efficient, as SRS contributions are deductible from taxable income up to the annual cap (SGD 15,300 for Singapore citizens and PRs).
What is iREIT Global's gearing ratio and why does it matter?
As at 1H2026, iREIT Global's gearing ratio stands at 45.5% — one of the highest in the S-REIT sector. The MAS regulatory limit for a REIT with a credit rating is 50%. High gearing means the REIT has relatively little buffer if European property valuations fall further or if debt is refinanced at higher interest rates. It also limits the REIT's ability to make yield-accretive acquisitions without first raising equity or disposing of assets, which can be dilutive to unitholders.
How does the EUR/SGD exchange rate affect iREIT Global distributions?
All of iREIT Global's rental income is collected in Euros. When converting EUR income to SGD for distribution to Singapore investors, a weaker Euro directly reduces the SGD distribution amount. For example, at EUR/SGD 1.65 (the 2021 rate), EUR 0.74 cents would translate to approximately SGD 1.22 cents. At the current EUR/SGD of approximately 1.49–1.52, the same EUR 0.74 cents translates to approximately SGD 1.10–1.13 cents — roughly a 10% reduction in SGD terms. Investors with a constructive view on EUR strengthening may see a natural tailwind to future distributions.
What are the main risks of investing in iREIT Global?
The five key risks are: (1) EUR/SGD currency risk — a weaker Euro reduces SGD distributions; (2) high gearing at 45.5%, leaving little headroom before the regulatory cap; (3) European office market structural headwinds from hybrid working trends; (4) refinancing risk as debt matures at potentially higher European interest rates; and (5) Germany concentration — roughly 65% of gross rental income comes from Germany, which has faced economic and property market challenges in 2024–2026. iREIT Global is considered a higher-risk S-REIT and is best suited to investors who understand and accept these risks.
Start Investing in S-REITs Today
Open a brokerage account and buy iREIT Global or explore other S-REITs for passive income. Use our referral links for exclusive sign-up bonuses.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.