Mapletree Commercial Trust Share Price 2026: MCT Is Now MPACT (N2IU) — Full Investor Analysis
S-REIT Deep Dive · SGX: N2IU · Data as at November 2026
Searching for Mapletree Commercial Trust share price? Here is the complete 2026 picture: MCT merged with Mapletree North Asia Commercial Trust (MNACT) in August 2022 to form Mapletree Pan Asia Commercial Trust (MPACT), trading on SGX under the ticker N2IU. As at November 2026, MPACT trades at approximately S$1.38 per unit, offering a ~6.4% distribution yield and ~0.79x price-to-NAV — a meaningful discount to its book value. This guide covers the MCT-to-MPACT transition, current metrics, portfolio analysis, DPU history, and whether N2IU is worth buying today.
Not financial advice. All figures are for educational reference only. Data as at November 2026 unless noted.
Table of Contents
- What Happened to Mapletree Commercial Trust?
- MPACT (N2IU) Key Facts at a Glance
- Share Price History: From MCT to MPACT
- Portfolio Overview — VivoCity and Beyond
- DPU History and Distribution Yield
- P/NAV: Is MPACT Trading at a Discount?
- Investment Verdict: Buy, Hold or Sell?
- Where to Buy MPACT in Singapore
- FAQ
What Happened to Mapletree Commercial Trust?
Mapletree Commercial Trust (MCT) listed on the SGX in April 2011 at S$0.88 per unit. It was originally a pure-play Singapore commercial REIT focused on VivoCity, Mapletree Business City I, Mapletree Anson, and other Mapletree-branded assets in Singapore. Through the mid-2010s, MCT became one of Singapore’s most popular REITs among retail investors, peaking at approximately S$2.07 per unit in early 2020 before the COVID-19 sell-off.
In 2022, Mapletree Investments decided to merge MCT with its sister REIT — Mapletree North Asia Commercial Trust (MNACT), which held assets across Hong Kong, Japan, South Korea, and China. The rationale was portfolio diversification and cost synergies. The merger was approved by unitholders in May 2022 and completed in August 2022, creating Mapletree Pan Asia Commercial Trust (MPACT), trading under the ticker N2IU on SGX.
The merger used an exchange ratio, so existing MCT unitholders received MPACT units in exchange. If you held MCT before August 2022, your units were automatically converted to MPACT (N2IU) units. The combined entity is significantly larger, with assets spanning six markets: Singapore, Hong Kong, Japan, South Korea, China, and Australia (Festival Walk in Hong Kong is the most prominent overseas asset).
For investors searching for the “Mapletree Commercial Trust share price,” the answer is simple: there is no longer a separate MCT entity. MCT is now MPACT. To check the current share price, search for SGX ticker N2IU on any Singapore broker platform.
MPACT (N2IU) Key Facts at a Glance
Here are the essential numbers for Mapletree Pan Asia Commercial Trust as at November 2026.
| Metric | Value |
|---|---|
| Full Name | Mapletree Pan Asia Commercial Trust |
| Former Names | Mapletree Commercial Trust (MCT) + Mapletree North Asia Commercial Trust (MNACT) |
| SGX Ticker | N2IU |
| Sponsor | Mapletree Investments Pte Ltd |
| Merger Completed | August 2022 |
| Share Price (Nov 2026) | ~S$1.38 per unit |
| DPU FY2026 (est.) | ~8.80 Singapore cents |
| Distribution Yield | ~6.4% at current price |
| NAV per Unit | ~S$1.75 |
| Price-to-NAV | ~0.79x (21% discount to book) |
| Aggregate Leverage | ~41.0% |
| Total Assets | ~S$17.5 billion |
| Distribution Frequency | Quarterly |
| Markets | Singapore, Hong Kong, Japan, South Korea, China |
Source: TKN estimates based on MPACT public disclosures, SGX filings. All figures approximate and as at November 2026. Not financial advice.
Share Price History: From MCT to MPACT
Understanding the MPACT (formerly MCT) share price journey requires splitting the history into two distinct phases: the MCT years (2011–2022) and the post-merger MPACT era.
MCT Phase (2011–2022): MCT listed at S$0.88 in April 2011 and enjoyed a broadly positive trajectory through the low-interest-rate decade. The REIT peaked at approximately S$2.07 per unit in early 2020. Even after the COVID-19 sell-off, MCT recovered strongly as VivoCity’s retail operations resumed. At the time of the merger announcement in late 2021, MCT was trading around S$1.95–2.00.
MPACT Phase (2022–Present): The post-merger MPACT faced a challenging macro environment almost immediately. Rising interest rates from mid-2022 through 2023 increased MPACT’s borrowing costs (gearing of ~41% means roughly S$7 billion in debt), and the Hong Kong portfolio — particularly Festival Walk — faced headwinds from slower retail recovery and HKD volatility. By end-2024, MPACT had declined to the S$1.30–S$1.45 range, where it has broadly traded through 2026.
| Period | Price / Event | Key Driver |
|---|---|---|
| MCT IPO (Apr 2011) | S$0.88 | VivoCity anchor; pure SG commercial REIT |
| Peak (Jan 2020) | ~S$2.07 | Low rates, strong SG retail/office |
| MCT-MNACT Merger (Aug 2022) | ~S$1.80 (at merger) | MPACT formed; Fed hiking cycle begins |
| Rate cycle peak (2023) | ~S$1.45 | Higher financing costs; HK headwinds |
| November 2026 | ~S$1.38 | Rate normalisation; lingering overseas drag |
Source: TKN estimates / historical data. Approximate prices. Not financial advice.
For MCT-era investors who held at peak prices (above S$2), the merger and subsequent price decline has been disappointing. However, at ~S$1.38, MPACT now offers a yield of ~6.4% and trades at a 21% discount to its estimated NAV — a materially different risk/reward profile than it had at S$2.00.
Portfolio Overview — VivoCity and Beyond
MPACT’s portfolio spans two categories: the legacy MCT Singapore assets that most investors know, and the MNACT overseas assets added through the 2022 merger.
Singapore Assets (legacy MCT):
- VivoCity — Singapore’s largest mall by NLA, anchored to HarbourFront MRT. The crown jewel of the portfolio, contributing approximately 35–40% of MPACT’s Singapore NPI. Shopper traffic has recovered post-COVID and the asset continues to generate stable retail income.
- Mapletree Business City I (MBC I) — A large business park and office complex in Pasir Panjang. Shared anchor tenants include tech and financial services firms. MBC I is co-managed with Mapletree Industrial Trust (MIT/ME8U). Read our Mapletree Business City 2026 deep dive for the full breakdown.
- Mapletree Anson — A Grade A office tower at 60 Anson Road in Singapore’s CBD. 100% committed occupancy in recent years, with long WALE tenants. See our separate Mapletree Anson 2026 analysis.
- Mapletree MLHF (Moxy Hotel) — A hospitality asset at HarbourFront, part of the Marriott Moxy brand.
Asia-Pacific Assets (from MNACT merger): The overseas portfolio added through the MNACT merger includes Festival Walk (Hong Kong’s major retail/office complex), two properties in Japan (mTower, Sandhill Plaza), properties in South Korea, and office assets in China. These overseas assets diversify geographic risk but also introduce FX volatility — HKD, JPY, KRW, CNY, and AUD all affect MPACT’s SGD-denominated DPU.
As a rough guide, Singapore contributes approximately 55–60% of MPACT’s NPI, with the remaining 40–45% from overseas. This is a meaningful change from MCT’s days as a pure-play Singapore REIT.
DPU History and Distribution Yield
Tracking MPACT’s distribution per unit (DPU) history reveals the impact of the merger and subsequent macroeconomic headwinds. DPU declined from MCT’s pre-merger highs as higher interest rates increased financing costs and overseas FX movements reduced the SGD-equivalent distributions.
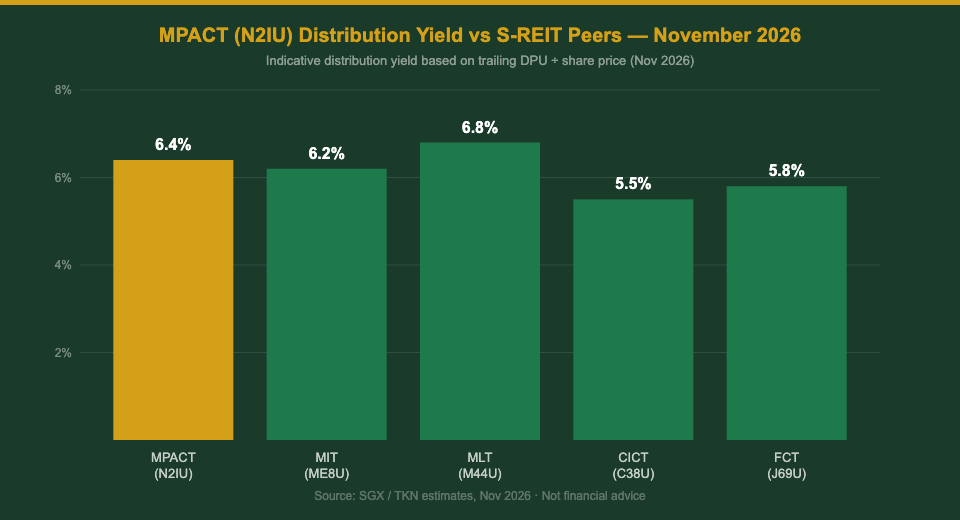
Investors seeking passive income in Singapore should note that MPACT distributes quarterly, making it a popular choice for income-focused portfolios alongside peers like MIT, MLT, and CICT.
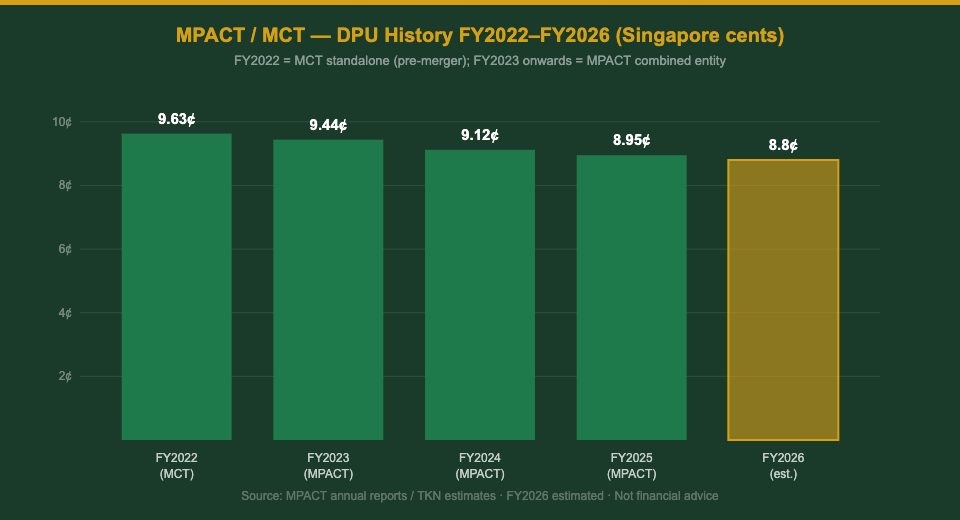
| Financial Year | DPU (SG cents) | Yield at S$1.38 | Notes |
|---|---|---|---|
| FY2022 (MCT standalone) | 9.63¢ | 7.0% | Last full year as pure SG REIT |
| FY2023 (MPACT) | 9.44¢ | 6.8% | First full year post-merger; rate hikes begin |
| FY2024 (MPACT) | 9.12¢ | 6.6% | Higher debt costs; HK retail recovery slow |
| FY2025 (MPACT) | 8.95¢ | 6.5% | Rate normalisation begins; overseas FX drag |
| FY2026 (estimated) | ~8.80¢ | ~6.4% | Modest DPU compression; rate cycle easing |
Source: TKN estimates based on MPACT public filings. FY2026 estimated. Yield calculated at ~S$1.38 share price. Not financial advice.
At ~6.4%, MPACT’s yield sits above Singapore’s 10-year government bond yield and above most bank fixed deposits, while remaining broadly in line with large-cap S-REIT peers. For investors building a best S-REITs in Singapore portfolio, MPACT represents a large, diversified commercial REIT with well-known assets.
P/NAV: Is MPACT Trading at a Discount?
At approximately S$1.38 per unit against an estimated NAV of ~S$1.75, MPACT trades at a price-to-NAV (P/NAV) ratio of roughly 0.79x — a 21% discount to its book value. This is notable because MCT historically traded at or above NAV for most of its pre-merger life, peaking at approximately 1.5x P/NAV in 2020.
The current discount reflects several factors. Higher interest rates increase the discount rate used to value real estate assets, compressing valuations. The overseas portfolio (particularly Hong Kong) faces slower-than-expected recovery in retail traffic. Additionally, Singapore office demand remains mixed following the global hybrid-work trend, creating uncertainty around MBC I and Mapletree Anson’s long-term occupancy.
A discount to NAV is not automatically a “buy” signal — REIT NAVs can decline if property values are marked down. However, at ~0.79x P/NAV, MPACT does offer some margin of safety relative to its asset base. If interest rates continue to normalise and the HK portfolio stabilises, the discount could narrow, providing capital gains on top of the ~6.4% distribution yield.
For context, Mapletree Industrial Trust (ME8U) and CapitaLand Integrated Commercial Trust (C38U) also trade at discounts to NAV in 2026, suggesting this is a sector-wide phenomenon rather than MPACT-specific.
Investment Verdict: Buy, Hold or Sell?
MPACT (formerly MCT, ticker N2IU) offers a ~6.4% yield at current prices with a 21% NAV discount, quarterly distributions, and a portfolio anchored by Singapore’s largest mall (VivoCity) and two of its strongest commercial districts (HarbourFront and Pasir Panjang). These are tangible strengths. However, the investment case is not without risks.
Bull case: Interest rates normalise further, reducing MPACT’s ~S$7 billion debt servicing costs and allowing more distributable income to flow to unitholders. The Hong Kong portfolio (Festival Walk) recovers as tourism and retail traffic normalise. The 21% NAV discount closes, delivering capital appreciation alongside 6%+ income.
Bear case: Singapore office oversupply emerges from new completions, pressuring MBC I and Mapletree Anson occupancy. HKD, JPY, and KRW FX headwinds persist, further eroding SGD-equivalent DPU. NAV is marked down in future valuations, increasing the effective P/NAV ratio even at today’s price.
Base case verdict: MPACT is a Hold/Accumulate for income-focused investors with a 3–5 year horizon who can tolerate overseas exposure. At ~6.4% yield and 0.79x P/NAV, the risk/reward is more attractive than it has been in several years — but it is not the pure, clean Singapore commercial play that MCT was. Investors who preferred MCT for its simplicity and pure-SG focus may find that the MPACT thesis requires accepting greater complexity.
If you are looking to diversify across the S-REIT sector more broadly, check out our guide to the best S-REITs in Singapore 2026. For retirement income planning, our Singapore retirement calculator can help you model REIT distributions alongside CPF as part of a broader retirement income plan.
Where to Buy MPACT (N2IU) in Singapore
MPACT is listed on the Singapore Exchange (SGX) and can be purchased through any Singapore-licensed broker. Here are the most popular options among Singapore retail investors. We describe each platform; this is not a ranking or personalised recommendation.
- FSMOne — A local broker with competitive SGX commissions starting from S$10 per trade. Supports both cash and CPF-OA purchases of SGX-listed REITs including MPACT. Use our FSMOne referral code to sign up. (Referral code: P0544985)
- IBKR (Interactive Brokers) — Low commissions at ~0.08% per trade, min S$2.50. Well-suited for active traders or those investing larger amounts. See our IBKR referral code page for details. (Referral: jianxiong368)
- Syfe — A robo-advisory platform offering curated S-REIT portfolios. If you prefer hands-off investing over picking individual REITs, Syfe’s REIT+ portfolio gives diversified S-REIT exposure. Syfe referral code and sign-up bonus. (Referral: SRPRFFFCD)
- Endowus — Another passive investing platform with CPF and cash access to diversified portfolios. Endowus referral code for new users. (Referral: 2V343)
CPF and SRS Eligibility: MPACT (N2IU) is an SGX-listed S-REIT and is included on the CPF Investment Scheme (CPFIS) approved list, meaning CPF-OA funds can be used to purchase it through an eligible broker. SRS funds can also be used for SGX-listed securities. Always verify eligibility with your CPF account and broker before transacting.
Frequently Asked Questions About Mapletree Commercial Trust (MPACT)
What happened to Mapletree Commercial Trust (MCT)?
What is the current share price of Mapletree Commercial Trust?
What is MPACT's ticker symbol on SGX?
Is MPACT (formerly MCT) a good investment in 2026?
What is MPACT's DPU and distribution yield?
Can I use CPF to invest in MPACT (N2IU)?
This article is for educational purposes only and does not constitute financial advice. REIT investments involve risk, including loss of capital. All data is approximate and as at November 2026. Consult a qualified financial adviser before making investment decisions. The Kopi Notes may earn referral fees from links to broker platforms.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.