Mapletree Anson 2026: 60 Anson Road’s Role in MPACT’s Singapore Portfolio (SGX: N2IU)
Mapletree Anson is an 18-storey Grade A office building at 60 Anson Road, Tanjong Pagar, Singapore, wholly owned by Mapletree Pan Asia Commercial Trust (MPACT, SGX: N2IU). Singapore retail investors gain exposure to Mapletree Anson’s commercial rental income by holding MPACT units, which trade at approximately 6% forward yield as at November 2026. Historically near-full occupancy (~96–99%) makes Mapletree Anson one of MPACT’s most stable Singapore income contributors.
Not financial advice. All figures are for educational reference only. Data as at November 2026 unless noted. Always verify financial data against the latest MPACT SGX filings before making investment decisions.
Table of Contents
What Is Mapletree Anson?
Mapletree Anson is a 18-storey Grade A commercial office building located at 60 Anson Road in Singapore’s Tanjong Pagar central business district. The property is 100% owned by Mapletree Pan Asia Commercial Trust (MPACT), a Singapore real estate investment trust listed on the Singapore Exchange (SGX: N2IU). MPACT is managed by Mapletree Investments Pte Ltd, a property company backed by Temasek Holdings with over S$70 billion in assets under management globally.
For retail investors, Mapletree Anson cannot be bought directly as a standalone asset. The only way to invest in this property’s rental income stream is through buying MPACT units on SGX — which entitles you to quarterly distributions derived from the full MPACT portfolio, of which Mapletree Anson is a component.
Understanding Mapletree Anson’s fundamentals helps MPACT investors assess one of the trust’s most reliable Singapore income generators, particularly at a time when MPACT’s overseas assets (especially in Japan) have faced occupancy headwinds in FY2027.
Key Facts at a Glance
| Metric | Detail |
|---|---|
| Property Name | Mapletree Anson |
| Address | 60 Anson Road, Singapore 079914 |
| Property Type | Grade A commercial office |
| Number of Floors | 18 above-ground floors |
| Net Lettable Area | ~26,200 sqm (~282,000 sq ft) |
| Tenure | 99-year leasehold |
| REIT Owner | Mapletree Pan Asia Commercial Trust (SGX: N2IU) |
| Committed Occupancy | ~96–99% (FY2024–FY2026) |
| Nearby Transport | Tanjong Pagar MRT (East-West Line) |
Source: MPACT Annual Report FY2026, SGX filings. Figures are estimates; verify against latest disclosures.
Location and Building Specifications
Tanjong Pagar is one of Singapore’s premium office submarkets. The area has undergone significant transformation over the past decade — anchored by Guoco Tower (Singapore’s tallest building), the Wallich Residence, and the expansion of the Marina Bay financial corridor.
Mapletree Anson benefits from several key location advantages:
- MRT connectivity: Direct access to Tanjong Pagar MRT station on the East-West Line, with the upcoming Cross Island Line expected to further boost commuter traffic in the district.
- CBD premium rents: Tanjong Pagar Grade A office space typically commands S$8–S$12+ per square foot per month depending on floor level and market cycle, among the highest in Singapore outside Marina Bay.
- Professional tenant profile: The building attracts law firms, financial services, and regional corporate headquarters due to its prime CBD address and efficient floor plate configuration of approximately 1,500–2,000 sqm per floor.
- Retail and F&B podium: Multiple food and beverage outlets and retail amenities serving the working population, supporting tenant retention.
The 18-storey configuration suits professional services firms and financial institutions seeking mid-to-large floor plate offices in a Class A address. As of MPACT’s latest available report, committed occupancy has remained in the 96–99% range, outperforming Singapore’s overall Grade A office vacancy rate of approximately 4–6%.
Tenants and Occupancy Track Record
MPACT does not disclose individual tenant names for Mapletree Anson, in line with standard REIT reporting practice. The property’s tenant mix has historically been anchored by professional services firms, financial institutions, and corporate regional offices — all of which are characterised by longer average lease tenures compared to typical Grade B tenants.
| Financial Year | Approximate Committed Occupancy | Singapore Office Market (est.) |
|---|---|---|
| FY2022 | ~97% | ~95% |
| FY2023 | ~96% | ~95% |
| FY2024 | ~98% | ~95% |
| FY2025 | ~97% | ~95% |
| FY2026 (est.) | ~96% | ~94–96% |
Source: MPACT Annual Reports. Historical occupancy is estimated. Verify exact figures at mapletreepanasiact.com.sg.
The consistent near-full occupancy outperforms the Singapore core CBD Grade A market average, suggesting Mapletree Anson benefits from sticky tenants, competitive rental positioning, and a prime CBD address that commands tenant loyalty.
Mapletree Anson’s Role in MPACT’s Portfolio
MPACT’s portfolio spans five markets: Singapore, Hong Kong (Festival Walk retail mall), Japan, China, and South Korea. As at FY2026, Singapore contributed approximately 42% of MPACT’s total gross revenue.
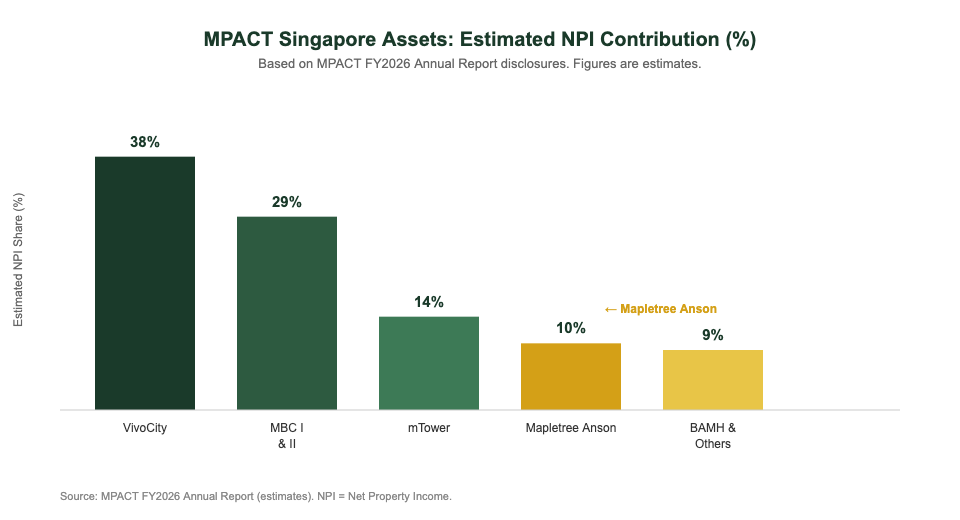
Within Singapore, MPACT’s major assets include VivoCity (retail, Harbourfront), Mapletree Business City I & II (office, Alexandra), mTower (office, Alexandra), Mapletree Anson (office, Tanjong Pagar CBD), and Bank of America Merrill Lynch HarbourFront (office). Our recent Mapletree Business City 2026 deep-dive covers the Alexandra campus in detail.
Mapletree Anson contributes an estimated 8–10% of MPACT’s total Singapore NPI (net property income), or approximately 4–5% of MPACT’s overall NPI including overseas markets. While modest in absolute terms, its value to investors lies in three areas:
- CBD premium positioning: Higher rental rates per sqm vs suburban assets generate outsized NPI per unit of floor area.
- Occupancy stability: Near-full occupancy provides a reliable income floor with minimal void periods.
- Capital value: Grade A CBD assets typically command a premium NAV multiple, supporting MPACT’s overall book value.
Important context on MPACT’s overall performance: Investors should note that MPACT’s distributions are determined by the full portfolio, not just Singapore. As of MPACT’s 1QFY2027 results, DPU fell 2.5% year-on-year, driven by Japan’s festival and convention mall occupancy dropping sharply — a major drag on distributions. Singapore assets like Mapletree Anson provide a stable floor, but Japan and China performance remains a key variable for total DPU. Singapore-focused investors should not over-weight the Singapore portfolio when evaluating the overall REIT; passive income from Singapore REITs requires monitoring all geographies in a pan-Asia trust like MPACT.
MPACT Singapore Portfolio: Estimated NPI Contribution by Asset
MPACT (N2IU): Share Price and Investment Case
To invest in Mapletree Anson’s income, you buy MPACT units on SGX. Here is a snapshot of MPACT’s key investment metrics as at November 2026:
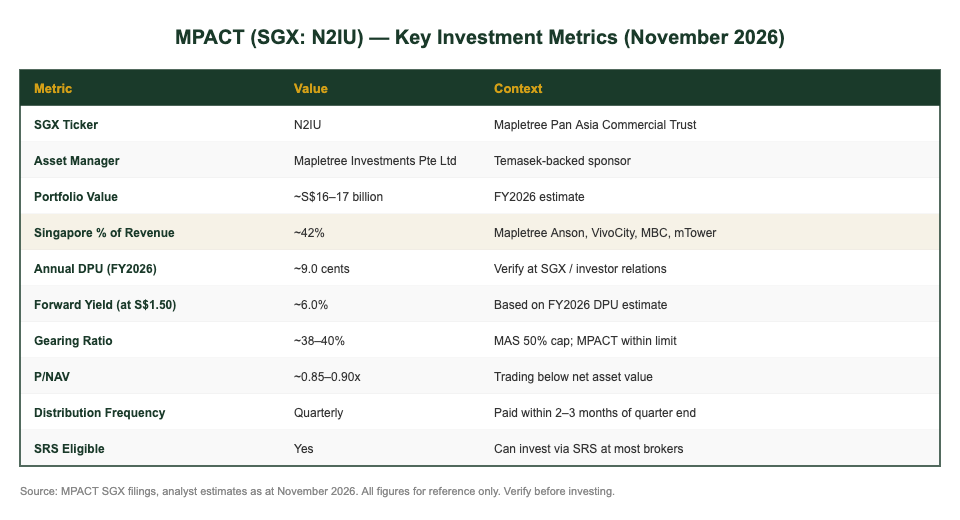
The bull case for MPACT: MPACT trades at a discount to NAV (P/NAV ~0.85–0.90x), offering a ~6% forward yield backed by Singapore’s premier retail asset (VivoCity) and a stable Grade A office portfolio including Mapletree Anson. The Temasek-backed sponsor pipeline provides a long-term growth runway via acquisitions. Rate cuts from the US Federal Reserve (ongoing in H2 2026) support REIT valuations broadly, and Singapore’s Grade A office market remains structurally undersupplied relative to demand from professional services and technology tenants.
The bear case: Japan operations remain a drag, with occupancy for MPACT’s festive retail malls in Japan recovering slowly. Currency risk (JPY, HKD depreciation vs SGD) impacts headline DPU numbers. Rising debt costs on upcoming debt refinancing cycles could compress net income margins. Investors seeking pure Singapore-CBD exposure may prefer a more concentrated S-REIT such as other best-performing S-REITs in 2026.
For income-focused Singapore investors, MPACT offers broad Asia-Pacific commercial real estate exposure through a single listed vehicle — with Mapletree Anson as one of its reliable Singapore CBD income engines. The Singapore REIT ETF guide covers alternative exposure routes for those who prefer a diversified basket over individual REIT selection.
How to Invest in Mapletree Anson’s Income
To invest in Mapletree Anson’s income stream, you buy MPACT units (SGX: N2IU) through any SGX-connected brokerage. MPACT declares distributions quarterly, typically credited to your brokerage settlement account within two to three months of each quarter end.
MPACT is eligible for SRS (Supplementary Retirement Scheme) investment via most Singapore brokerages, which provides a tax deduction on SRS contributions used to purchase units. Consider our Singapore retirement planning calculator to model how REIT income complements your CPF and SRS retirement plan.
Where to buy N2IU in Singapore — use our referral links for sign-up bonuses:
- moomoo Singapore — Competitive SGX brokerage fees, real-time SGX data included, easy to use. See current promotions via our moomoo referral code.
- FSMOne (iFAST) — Zero custody fee for SGX stocks, suitable for investors building a regular buy plan. See our FSMOne referral code P0544985 for the current bonus.
- Endowus — For CPF-OA or SRS managed portfolio exposure to Singapore REITs. Use referral code 2V343 for fee savings. Note: MPACT direct purchase via CPF-OA has limited eligibility; verify at cpf.gov.sg before investing.
- Syfe — Syfe’s REIT+ portfolio includes MPACT alongside other major S-REITs, ideal for hands-off investors. Use referral code SRPRFFFCD.
Frequently Asked Questions
What is Mapletree Anson and how can I invest in it?
Mapletree Anson is a 18-storey Grade A office building at 60 Anson Road, Tanjong Pagar, Singapore. It is wholly owned by Mapletree Pan Asia Commercial Trust (MPACT, SGX: N2IU). You cannot buy Mapletree Anson directly as a retail investor. To gain exposure to its rental income, purchase MPACT units on the Singapore Exchange through any SGX-connected brokerage such as moomoo, FSMOne, or IBKR.
Is Mapletree Anson part of Mapletree Industrial Trust (MIT) or MPACT?
Mapletree Anson is part of Mapletree Pan Asia Commercial Trust (MPACT, SGX: N2IU), not Mapletree Industrial Trust (MIT, SGX: ME8U). MPACT focuses on commercial (retail and office) properties across Asia Pacific, while MIT focuses on industrial and data centre assets. Both are managed by Mapletree Investments, the same Temasek-backed sponsor.
What is the MPACT (N2IU) dividend yield in 2026?
As at November 2026, MPACT’s estimated forward yield is approximately 5.5–6.5% based on analyst estimates for FY2026–FY2027 DPU. The actual yield depends on MPACT’s quarterly DPU declarations and the market price at the time of purchase. Always verify the latest DPU figures from MPACT’s SGX announcements at sgxnet.sgx.com before making any investment decision.
Is MPACT a good buy for Singapore income investors in November 2026?
MPACT offers a ~6% forward yield and trades below NAV (P/NAV ~0.85–0.90x as at H2 2026), which is attractive for income investors. However, Japan operations remain a drag on overall DPU (1QFY2027 DPU fell ~2.5% YoY). Investors seeking stable income should weigh MPACT’s strong Singapore portfolio (which includes Mapletree Anson, VivoCity, MBC) against the ongoing headwinds in Japan. This is not financial advice; consult a licensed financial advisor before investing.
Can I use CPF or SRS to invest in MPACT?
MPACT (N2IU) may be eligible for CPF Investment Scheme (CPFIS) investment via CPF-OA, subject to MAS and CPF Board eligibility rules — verify at cpf.gov.sg before investing, as eligibility can change. MPACT is eligible for SRS investment via most Singapore brokerages, with the SRS contribution providing a tax deduction. Endowus and Syfe also offer REIT portfolio exposure via SRS and CPF for investors preferring a managed approach.
What is the typical occupancy rate of Mapletree Anson?
Mapletree Anson has historically maintained committed occupancy in the 96–99% range, based on MPACT’s quarterly and annual report disclosures. This is at or above Singapore’s core CBD Grade A office market average occupancy of approximately 94–96%. The property’s prime Tanjong Pagar location and professional-services tenant mix contribute to strong tenant retention.
How does Mapletree Anson compare to other MPACT Singapore assets?
Within MPACT’s Singapore portfolio, VivoCity (retail) is the largest NPI contributor (~38% of Singapore NPI), followed by Mapletree Business City I & II (~29%) and mTower (~14%). Mapletree Anson contributes an estimated 8–10% of Singapore NPI, making it a mid-tier but high-quality asset. Its value lies in CBD premium positioning and occupancy stability rather than pure NPI scale. See our Mapletree Business City 2026 guide for a comparison of MPACT’s Alexandra campus.
Start Investing in MPACT and Singapore REITs
Gain exposure to Mapletree Anson’s Grade A office income through MPACT (SGX: N2IU). Open a brokerage account and start building your Singapore REIT income portfolio today.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.