ParkwayLife REIT Dividend History 2007–2026: 19-Year DPU Track Record & Yield-on-Cost Analysis (SGX: C2PU)
ParkwayLife REIT (SGX: C2PU) has delivered 19 consecutive years of distribution per unit (DPU) growth since its IPO in August 2007, growing from 6.83 cents in FY2008 to 15.29 cents in FY2025 — a 123.9% increase. As Asia’s largest listed healthcare REIT, it owns Singapore hospitals and Japan nursing homes, making it one of the most defensive income assets on the SGX.
Not financial advice. All figures are for educational reference only. Data as at November 2026 unless noted. Past performance is not indicative of future results.
ParkwayLife REIT DPU History 2007–2026
ParkwayLife REIT listed on the SGX on 23 August 2007 at an IPO price of S$1.28 per unit. The initial portfolio comprised three Singapore private hospitals — Mount Elizabeth, Gleneagles, and Parkway East — leased to IHH Healthcare under long-term triple-net leases with built-in rental escalators tied to the Singapore Consumer Price Index (CPI).
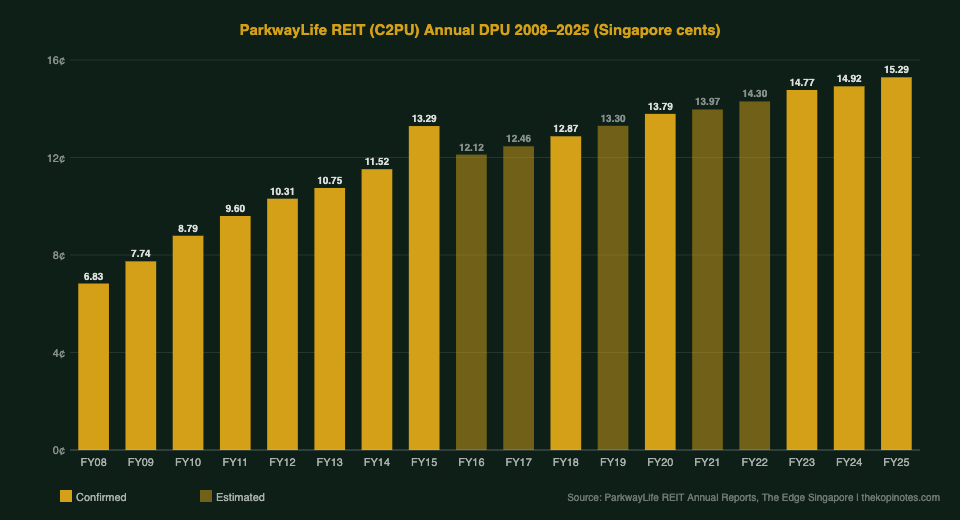
That inflation-linkage is the structural engine behind one of the most consistent DPU growth records among Singapore REITs. The table below presents the full distribution history from FY2008 to FY2025, plus a FY2026 estimate based on 1Q2026 results.
| Financial Year | DPU (cents) | YoY Growth | Key Event |
|---|---|---|---|
| FY2008 | 6.83 | — | First full financial year post-IPO |
| FY2009 | 7.74 | +13.3% | CPI escalation; Japan expansion begins |
| FY2010 | 8.79 | +13.6% | Japan nursing home portfolio grows |
| FY2011 | 9.60 | +9.2% | Stable organic growth |
| FY2012 | 10.31 | +7.4% | Continuing Japan acquisitions |
| FY2013 | 10.75 | +4.3% | Portfolio at 23 properties |
| FY2014 | 11.52 | +7.2% | SGD/JPY stability supported DPU |
| FY2015 | 13.29 | +15.4% | Includes one-off divestment gain |
| FY2016 | 12.12 | -8.8% | Normalised post one-off; JPY drag |
| FY2017 | 12.46 | +2.8% | Recovery; new Japan acquisitions |
| FY2018 | 12.87 | +3.3% | Stable; SGD/JPY managed via hedging |
| FY2019 | 13.30 | +3.3% | Pre-COVID steady growth |
| FY2020 | 13.79 | +3.7% | COVID resilience; hospitals essential |
| FY2021 | 13.97 | +1.3% | Post-COVID normalisation |
| FY2022 | 14.30 | +2.4% | Higher rates environment |
| FY2023 | 14.77 | +3.3% | CPI-linked rent revision upward |
| FY2024 | 14.92 | +1.0% | Moderated growth; stable hospitals |
| FY2025 | 15.29 | +2.5% | 19th consecutive growth year |
| FY2026E | ~17.0E | +11%E | Based on 1Q DPU 4.42¢ (+15.1% YoY) |
Source: ParkwayLife REIT annual reports, SGX filings, management announcements. FY2016–2017, FY2019, FY2021–2022 figures are estimates based on half-year results and analyst consensus. FY2026E = forward estimate based on 1Q2026 results (Aug 2026). Data as at November 2026.
The 19-year track record is extraordinary by REIT standards globally. From FY2008 to FY2025, DPU grew 123.9%. For investors building a passive income Singapore portfolio, this consistency is a core attraction of ParkwayLife REIT.
19-Year DPU Growth Chart
Yield-on-Cost: What Long-Term Holders Actually Earn
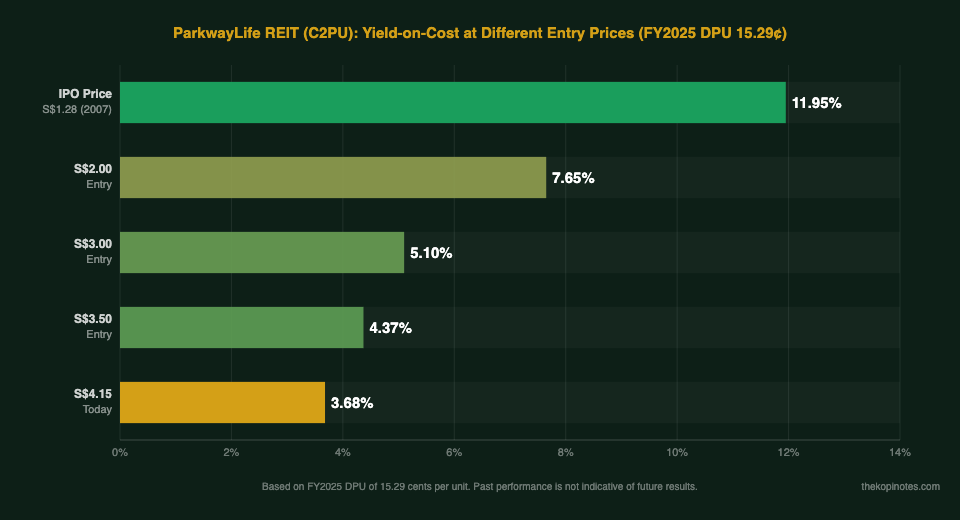
Yield-on-cost (YoC) is the annual distribution you receive as a percentage of what you originally paid. Because ParkwayLife REIT’s DPU has grown consistently, early investors enjoy dramatically higher effective yields than the headline current yield of ~3.68% (based on FY2025 DPU and S$4.15 unit price in Nov 2026) suggests.
| Entry Price | Entry Period | FY2025 DPU | Yield-on-Cost |
|---|---|---|---|
| S$1.28 (IPO) | Aug 2007 | 15.29¢ | 11.95% |
| S$2.00 | ~2009–2011 | 15.29¢ | 7.65% |
| S$3.00 | ~2015–2017 | 15.29¢ | 5.10% |
| S$3.50 | ~2019–2021 | 15.29¢ | 4.37% |
| S$4.15 (Nov 2026) | Current | 15.29¢ | 3.68% |
Source: SGX historical prices, ParkwayLife REIT annual reports. YoC = FY2025 DPU ÷ historical entry price. Entry periods are approximate. Data as at November 2026.
An investor who bought at the IPO price of S$1.28 and held through to today is now earning an 11.95% yield-on-cost. For long-term wealth building and Singapore retirement planning, compounding yield-on-cost from quality REITs is a powerful strategy.
Why ParkwayLife’s Healthcare Model Sustains DPU Growth
ParkwayLife REIT’s exceptional DPU consistency is structurally embedded in its portfolio design and lease architecture.
Singapore Hospitals: CPI-Linked Triple-Net Leases
The three Singapore hospitals (Mount Elizabeth, Gleneagles, Parkway East) contribute approximately 60% of net property income. These are leased to IHH Healthcare on 15-year triple-net leases. The annual rental is revised upward each year based on the higher of 1% or the percentage change in Singapore CPI. With Singapore CPI running at 2–4% over most of this period, the hospitals have delivered reliable annual rental growth with zero capital expenditure risk on ParkwayLife’s side.
Japan Nursing Homes: Ageing Demographics Tailwind
Japan’s 50-property nursing home portfolio (as at 2026) contributes ~40% of NPI. Japan has the world’s oldest population — over 29% are aged 65 or above — and demand for quality eldercare facilities structurally outpaces supply. The Master Lease structure gives ParkwayLife predictable rent income regardless of individual facility occupancy. Currency risk (JPY/SGD) is managed through rolling hedges.
Zero Commercial Real Estate Exposure
Unlike diversified S-REITs, ParkwayLife has never owned retail malls, suburban offices, or industrial parks. This hyper-specialisation means its cash flows are uncorrelated with economic cycles that pressure commercial real estate. During COVID-19, while most REITs cut distributions, ParkwayLife grew its DPU by 3.7% in FY2020. When reviewing the best S-REITs in Singapore 2026, ParkwayLife consistently ranks among the top for income stability.
FY2026 DPU Outlook
ParkwayLife REIT’s 1Q2026 results (released August 2026) reported DPU of 4.42 Singapore cents — a 15.1% increase year-on-year. This was driven by a significant positive CPI revision on the Singapore hospitals’ rents, as Singapore’s core CPI remained elevated at around 2.8–3.2% through 2025 and early 2026.
If this run-rate continues, full-year FY2026 DPU would be approximately S$0.17–0.175, implying a yield of about 4.1–4.2% at the current unit price of S$4.15. That would mark the 20th consecutive year of DPU growth.
Key risks to this outlook: (1) A sharp strengthening of SGD against JPY reduces the SGD value of Japan distributions; (2) Singapore CPI falling to near-zero reduces the annual hospital rent escalation; (3) Any adverse change to the IHH lease terms or credit quality; (4) Interest rate increases raising financing costs on Japan properties.
Where to Buy ParkwayLife REIT (SGX: C2PU)
ParkwayLife REIT trades on the SGX Mainboard under ticker C2PU in SGD. You can buy it through any SGX-authorised brokerage.
moomoo Singapore
moomoo offers competitive brokerage fees for SGX trades. Check the latest moomoo Singapore referral code and bonus before opening an account.
FSMOne (Fundsupermart)
FSMOne is a one-stop investment platform for Singapore investors, offering access to SGX stocks, REITs, unit trusts, bonds, and ETFs. Use FSMOne referral code P0544985 when signing up.
Robo-Advisors with S-REIT Exposure
If you prefer a managed approach, both Syfe and Endowus offer S-REIT portfolio options. Use the Syfe referral code SRPRFFFCD for a fee waiver bonus, or the Endowus referral code 2V343 for a cash reward on your first investment.
Frequently Asked Questions
What is ParkwayLife REIT's current dividend yield?
At a unit price of approximately S$4.15 (November 2026) and FY2025 DPU of 15.29 cents, ParkwayLife REIT’s trailing dividend yield is approximately 3.68%. If FY2026 DPU reaches the estimated 17.0 cents, the forward yield would be approximately 4.1% at the same price. ParkwayLife’s yield is typically lower than other S-REITs because investors pay a premium for its exceptional growth consistency and defensive healthcare income.
Has ParkwayLife REIT ever cut its dividend?
ParkwayLife REIT has not cut its annual DPU in any year since its IPO in 2007. The only apparent decline was FY2016 versus FY2015 — but FY2015 included a one-time divestment gain. On a recurring basis, underlying DPU has grown every single year for 19 consecutive years through FY2025. This is one of the longest unbroken DPU growth streaks among Singapore-listed REITs.
How often does ParkwayLife REIT pay dividends?
ParkwayLife REIT distributes to unitholders twice a year — an interim distribution (typically around August–September) and a final distribution (typically around February–March). The REIT’s distribution policy is to pay out at least 90% of its distributable income, which qualifies it for REIT tax transparency under Singapore income tax rules.
Is ParkwayLife REIT's dividend sustainable?
ParkwayLife REIT’s income is backed by long-term triple-net leases with IHH Healthcare (a BBB-rated global hospital operator) for its Singapore hospitals, and master leases for its Japan nursing homes. The CPI-linked rental escalation provides inflation protection. These structural features make the distributions among the most defensible in the Singapore REIT sector. Key risks are JPY/SGD currency movements, Singapore CPI trends, and interest rate changes affecting Japan property financing costs.
What is ParkwayLife REIT's DPU growth CAGR?
From FY2008 (the first full financial year) to FY2025, ParkwayLife REIT’s DPU grew from 6.83 cents to 15.29 cents — a compound annual growth rate (CAGR) of approximately 4.6% per year over 17 years. For the period FY2018 to FY2025, the CAGR was approximately 2.5% per year — consistent with moderate inflation and Singapore CPI escalation trends.
How does ParkwayLife REIT compare to other healthcare REITs?
ParkwayLife REIT (C2PU) is the only pure-play healthcare REIT listed on the SGX and Asia’s largest listed healthcare REIT by assets. Most other S-REITs experienced distribution cuts during COVID-19 or the global financial crisis, while ParkwayLife grew its DPU throughout both periods. For a full comparison with other top income REITs, see our guide to the best S-REITs in Singapore 2026.
Can I use CPF to buy ParkwayLife REIT?
Yes. ParkwayLife REIT (SGX: C2PU) is eligible for investment using CPF Ordinary Account (OA) funds via the CPF Investment Scheme (CPFIS-OA). Note that CPFIS-OA investments must be executed through a CPF-approved brokerage. Returns from CPFIS investments are not guaranteed, and the 2.5% interest rate on CPF OA funds means you need a total return above this hurdle to benefit from investing CPF savings. Consult a licensed financial adviser before making CPFIS investment decisions.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.