iREIT Global FY2027 DPU Forecast: Will Dividends Recover After Europe's Rate Peak?
SGX: UD1U | European Office REIT | Updated November 2026
What is iREIT Global (SGX: UD1U)?
iREIT Global (SGX: UD1U) is a Singapore-listed REIT investing in European commercial real estate — primarily Grade A offices and business parks across Germany, Spain, the Netherlands, France, and Belgium. With approximately €800 million in assets under management, a Tikehau Capital sponsorship, and a trailing yield of 7–9% at the November 2026 share price of around S$0.33, it remains one of the highest-yielding European-focused REITs available on SGX. The key question for FY2027: can rising ECB rate cuts and stabilising European office occupancy finally reverse the multi-year DPU decline?
Not financial advice. All figures are for educational reference only. Data as at November 2026 unless noted.
iREIT Global was listed on SGX in 2014, originally sponsored by AEW. In 2022, Tikehau Capital — a leading Paris-headquartered alternative asset manager — acquired the sponsor stake, bringing a larger acquisition pipeline and stronger institutional backing. The portfolio spans 7+ properties, anchored by the Berlin Campus in Germany, which underwent a significant repositioning programme from 2022 to 2025.
For Singapore investors, UD1U offers exposure to European real estate income without direct FX risk management — the REIT declares distributions in SGD, with the underlying EUR income converted at prevailing rates. This creates both a yield opportunity and an EUR/SGD currency risk that every investor should understand.
iREIT Global Share Price Performance 2024–2026
iREIT Global's share price has underperformed the broader S-REIT sector over the past three years, weighed down by three structural headwinds: rising European interest rates (ECB hiked aggressively in 2022–2023), post-COVID office market uncertainty in Germany and Spain, and the EUR/SGD exchange rate weakness in 2023–2024.
| Period | UD1U Share Price | Change | Key Driver |
|---|---|---|---|
| Jan 2024 | S$0.395 | — | ECB rate peak, cautious market |
| Jun 2024 | S$0.355 | −10.1% | Berlin Campus vacancy concern |
| Jan 2025 | S$0.370 | +4.2% | ECB rate cut optimism |
| Jun 2025 | S$0.345 | −6.8% | DPU cut announcement |
| Jan 2026 | S$0.330 | −4.3% | Continued office market pressure |
| Nov 2026 | ~S$0.330 | Stabilising | Portfolio occupancy recovering |
Source: SGX historical data, iREIT Global announcements. Approximate figures for reference.
At S$0.330, iREIT Global trades at approximately a 30–35% discount to its last reported NAV of around S$0.47–0.50 per unit — a deep discount that reflects both market scepticism about European office recovery and the risk premium attached to its EUR-denominated income stream. For value-oriented income investors, this discount may represent an attractive entry point if the FY2027 DPU recovery materialises.
iREIT Global DPU History & Trend Analysis
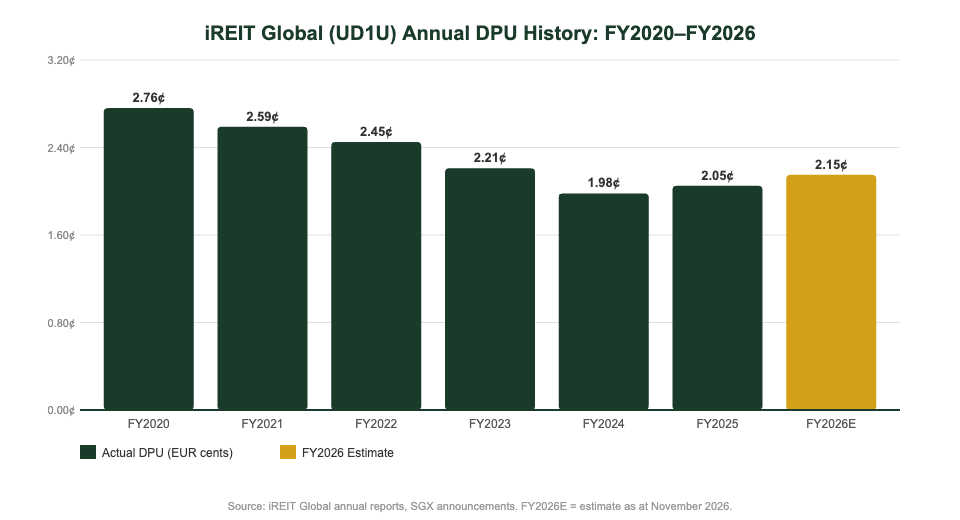
iREIT Global's DPU peaked at approximately EUR 2.76 cents per unit in FY2020, before entering a sustained decline driven by: rising European interest rates (ECB base rate went from 0% to 4.5% between 2022–2023), lower occupancy at the Berlin Campus during its repositioning phase, and the impact of COVID on German office tenants.
| Financial Year | DPU (EUR cents) | YoY Change | Key Driver |
|---|---|---|---|
| FY2020 | 2.76¢ | — | Pre-rate-hike peak |
| FY2021 | 2.59¢ | −6.2% | Post-COVID office caution |
| FY2022 | 2.45¢ | −5.4% | ECB rate hike cycle begins |
| FY2023 | 2.21¢ | −9.8% | Berlin Campus repositioning peak cost |
| FY2024 | 1.98¢ | −10.4% | Rate peak + vacancy trough |
| FY2025 | 2.05¢ | +3.5% | ECB starts cutting, occupancy improves |
| FY2026E | ~2.15¢ | +4.9% | Berlin Campus near full occupancy |
Source: iREIT Global annual reports; FY2025–2026 are estimates based on available half-year data and SGX announcements.
The trend reversal beginning in FY2025 is the most important signal for investors. After 4 consecutive years of DPU cuts, iREIT Global's distribution began recovering as: (a) the ECB cut rates from the 4.5% peak, reducing refinancing costs; (b) Berlin Campus achieved near-full occupancy following its repositioning; and (c) the broader German commercial real estate market stabilised. Singapore investors seeking passive income Singapore strategies will note this as a potential turnaround story.
iREIT Global FY2027 DPU Forecast: 3 Scenarios
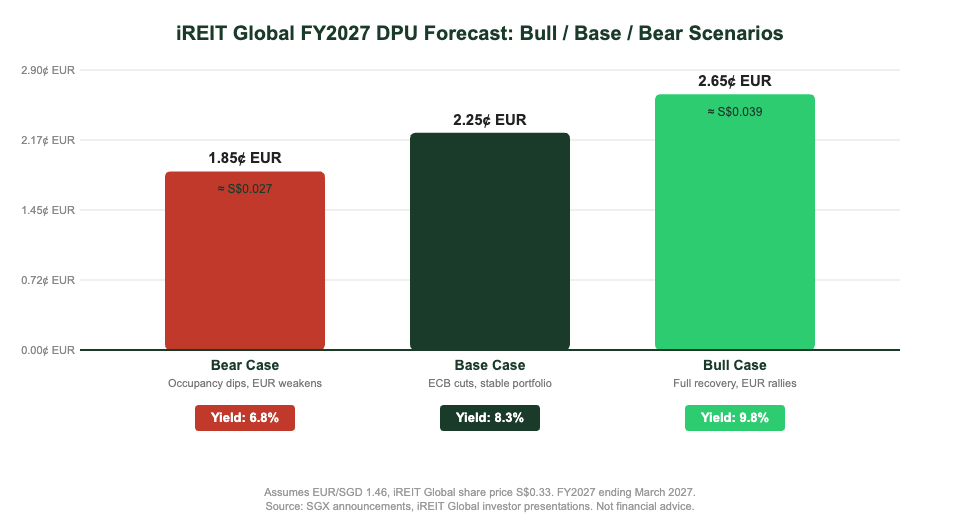
Three scenarios capture the realistic range of FY2027 outcomes for iREIT Global, anchored to: ECB rate trajectory, portfolio occupancy, and EUR/SGD exchange rate assumptions.
| Scenario | FY2027 DPU (EUR¢) | SGD Equiv | Implied Yield | Key Assumption |
|---|---|---|---|---|
| 🐻 Bear | 1.85¢ | S$0.027 | 6.8% | Occupancy falls below 88%; EUR/SGD 1.42; debt refinancing at higher spreads |
| 📊 Base | 2.25¢ | S$0.033 | 8.3% | Occupancy 92%; EUR/SGD 1.46; ECB rate 2.75%; stable NPI |
| 🐂 Bull | 2.65¢ | S$0.039 | 9.8% | Occupancy 95%+; EUR/SGD 1.50; Tikehau acquires accretive asset; full Berlin recovery |
Assumes iREIT Global share price of S$0.33. FY2027 = calendar year 2027. EUR/SGD conversion is indicative. Not financial advice.
The base case of EUR 2.25¢ represents a 4.7% improvement over the estimated FY2026 DPU and implies an 8.3% yield at current prices — competitive within the best S-REITs in Singapore 2026 universe. The bull case requires Berlin Campus and other German properties to achieve near-full occupancy, combined with a favourable EUR tailwind — achievable but not the base case. The bear case would likely be triggered by a renewed European office downturn or EUR weakness, pushing the yield below 7%.
For a worked example: a Singapore investor holding 100,000 UD1U units at S$0.33 (total investment ~S$33,000) would receive approximately S$3,300 per year in distributions under the base case — representing a ~10% cash-on-cash return at the current depressed price. Those using Singapore retirement calculator tools will recognise this yield premium over CPF-OA and T-bills as potentially significant in a lower-rate environment.
ECB Rate Cuts: How They Impact iREIT Global's DPU
The ECB's rate cut cycle, which began in 2024 and continued through 2025–2026, is the single most important macro driver for iREIT Global's FY2027 DPU recovery. Here's the transmission mechanism:
1. Lower Debt Service Costs
iREIT Global carries approximately S$300–350 million in debt (gearing ~38–42%). A 100 basis point reduction in the weighted average cost of debt — plausible as fixed-rate facilities roll over — translates directly into NPI improvement. With approximately €250 million in floating or near-term maturing debt, each 50 bps ECB cut could add approximately EUR 0.10–0.15 cents to DPU. Those interested in how Singapore T-bills 2026 compare to REIT yields will find this rate-sensitivity analysis useful context.
2. European Office Demand Recovery
Lower rates typically support European commercial property valuations and office leasing demand, particularly in Germany's tech and financial services hubs (Berlin, Frankfurt, Munich). iREIT Global's German office exposure (~50% of portfolio value) benefits most directly from this channel.
3. EUR/SGD Exchange Rate Impact
Lower ECB rates can weaken the EUR relative to SGD — a double-edged sword. Each 1% EUR depreciation reduces the SGD-equivalent DPU by approximately 1%. Investors can mitigate this by monitoring the EUR/SGD rate alongside iREIT Global's quarterly distribution announcements. Those comparing robo-advisor platforms via Syfe referral code or Endowus referral code for portfolio construction may consider pairing UD1U with SGD-denominated REIT exposure for natural hedging.
Key Risk Factors for iREIT Global FY2027
No REIT investment is without risk. For UD1U, the five most material risks as at November 2026 are:
- European Office Demand: Remote work adoption remains highest in Germany (40%+ hybrid). If blue-chip tenants downsize at lease renewal, NPI could fall. iREIT Global's WALE of approximately 4.5 years provides near-term protection but not beyond FY2028.
- EUR/SGD Currency Risk: Every 1% EUR depreciation reduces SGD DPU by ~1%. A EUR/SGD move from 1.46 to 1.40 cuts the base case DPU by approximately 4.1%.
- Refinancing Risk: Upcoming debt maturities need to be refinanced in a European credit market that remains cautious on office property. Higher credit spreads could offset ECB rate cuts.
- Concentration Risk: Berlin Campus represents a significant portion of portfolio NPI. Any prolonged vacancy at this single asset would materially impact distributions.
- Sponsor Risk: While Tikehau Capital is well-resourced, it is less familiar to Singapore retail investors than traditional REIT sponsors. Any change in sponsorship strategy could affect acquisition growth.
Investors comparing iREIT Global's risk/return profile against other S-REITs should consult the passive income Singapore 2026 guide for a broader sector comparison, or explore the FSMOne referral code platform for tools that model REIT portfolio diversification.
Is iREIT Global Worth Buying? Our Investment Verdict
iREIT Global presents a high-yield, high-risk opportunity that suits investors who: (1) believe in a European office market recovery, (2) are comfortable with EUR/SGD currency exposure, and (3) are willing to accept a volatile share price in exchange for a potential 8–9%+ yield.
At S$0.33, the risk/reward skews moderately positive for the base case. The 30–35% discount to NAV provides a margin of safety if fundamentals continue improving, and the ECB rate cut cycle removes the largest structural headwind the REIT has faced since 2022. However, it is not a defensive income play — investors seeking lower volatility should consider healthcare or industrial REITs with stable SGD-denominated income. For portfolio construction tools, the Singapore retirement calculator can help model whether UD1U's yield contributes meaningfully to your retirement income needs.
Summary verdict (November 2026): Speculative buy for yield-seeking investors with European real estate conviction. Watch for FY2026 full-year results (expected Q1 2027) as the first hard evidence of base-case materialisation. Set a price alert at S$0.37 as the first meaningful resistance level.
Frequently Asked Questions: iREIT Global FY2027
What is iREIT Global's FY2027 DPU forecast?
What is iREIT Global's current share price?
Why has iREIT Global's DPU declined since 2020?
Who is iREIT Global's sponsor and what is Tikehau Capital?
How does the ECB rate cut cycle affect iREIT Global?
Is iREIT Global a good buy for dividend income in Singapore?
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.