Critical Illness Insurance vs Health Insurance Singapore 2026
What’s the Difference — and Do You Need Both?Table of Contents
Table of Contents
Critical illness insurance and health insurance are not the same thing — and in Singapore, you almost certainly need both. Health insurance (MediShield Life and Integrated Shield Plans) reimburses hospital bills. Critical illness insurance pays you a lump sum when you are diagnosed with one of 37 covered conditions, which you can use for anything: income replacement, mortgage payments, home care, or daily expenses during recovery. The gap between these two types of coverage is where most Singaporeans are underprotected.
Not financial advice. All figures are for educational reference only. Data verified as at October 2026.
- Health insurance = pays your hospital bills (reimbursement)
- CI insurance = pays YOU a cash lump sum on diagnosis (not reimbursement)
- Both are necessary — they cover completely different financial risks
- MediShield Life is mandatory; CI insurance is optional but highly recommended
The Core Difference in One Sentence
Health insurance pays your hospital. Critical illness insurance pays you.
That single distinction explains almost everything. When you are hospitalised, MediShield Life and your Integrated Shield Plan (IP) pay the hospital directly — or reimburse you after you pay — for your ward charges, surgical fees, and treatment costs. The money flows to the medical institution, not to your bank account.
When you are diagnosed with a critical illness and have a CI policy, the insurer pays a cash lump sum directly into your account. You can do anything with it: pay your mortgage, cover three months of household expenses while you cannot work, fund home nursing care, or fly to another country for a second medical opinion. There is no receipt to submit. The cash is yours.
Cancer treatment in Singapore — including surgery, chemotherapy, and targeted therapy — can cost S$200,000 to S$400,000 over two to three years. A good Integrated Shield Plan will cover most of those hospital bills. But it will not replace your salary for the 18 months you cannot work. It will not pay your HDB loan. It will not fund your children’s school fees or cover the home care aide your family needs while you recover.
That gap is what critical illness insurance exists to fill.
What Is Health Insurance in Singapore?
Singapore’s health insurance system operates in two layers.
Layer 1: MediShield Life is the mandatory national health insurance scheme administered by the CPF Board. All Singapore Citizens and Permanent Residents are automatically enrolled. It covers inpatient hospitalisation (Class B2 and C ward) and selected outpatient treatments such as chemotherapy, dialysis, and day surgeries. MediShield Life pays a portion of your hospitalisation bill after you have met your annual deductible (S$1,500 to S$3,000 depending on ward class and age) and co-insurance (10% of the claimable amount above the deductible).
Layer 2: Integrated Shield Plans (IPs) are private insurance add-ons sold by approved insurers (AIA, Great Eastern, Income, Prudential, Raffles Health Insurance, Singlife). They upgrade your MediShield Life coverage to private hospital wards (Class A/B1 or private hospital entirely), increase the claim limits, and cover certain outpatient specialist visits. An IP rider can reduce or eliminate the deductible and co-insurance components. IPs are optional but widely held in Singapore — approximately 70% of residents have an IP.
Both layers operate on a reimbursement model. You receive money only to pay for actual medical bills, up to the policy limits.
| Layer | Product | Mandatory? | Coverage | Payout |
|---|---|---|---|---|
| Base | MediShield Life | Yes | B2/C ward, selected outpatient | Reimbursement |
| Upgrade | Integrated Shield Plan | Optional | Private hospital, A/B1 ward | Reimbursement |
| Rider | IP Rider | Optional | Reduces deductible & co-insurance | Reimbursement |
Source: CPF Board MediShield Life; AIA, Great Eastern, Income, Prudential, Singlife IP brochures; October 2026.
What Is Critical Illness Insurance?
Critical illness insurance is a standalone policy that pays a pre-agreed lump sum if you are diagnosed with one of the covered critical illnesses. The payout is not linked to your actual medical expenses. It is triggered by the diagnosis — not by the bills.
In Singapore, the Life Insurance Association (LIA) mandates a standardised list of 37 critical illnesses that all compliant CI policies must cover. These include the three most common in Singapore: cancer, heart attack, and stroke. The full list also covers conditions such as kidney failure, major organ transplant, coronary artery bypass surgery, paralysis of limbs, blindness, and more.
Two timing conditions apply:
- Waiting period: 90 days from the policy commencement date. Claims triggered by illness within the first 90 days are not paid. Accidental causes are typically exempt.
- Survival period: 14 days. You must survive at least 14 days after diagnosis to make a claim. This is a standard LIA requirement across all Singapore CI policies.
Once a claim is approved, the entire sum insured is paid out as a lump sum. A S$300,000 CI policy pays S$300,000 — regardless of whether your actual medical bills are S$50,000 or S$500,000. The surplus is yours to use as you see fit.
There are two main types: single-pay (one payout and the policy ends) and multi-pay (allows multiple claims across different critical illnesses). You can also add CI coverage as a rider on a whole life policy, or buy it as a standalone term CI plan. For a breakdown of coverage amounts, read our guide on how much critical illness insurance you need in Singapore.
Key Differences: CI Insurance vs Health Insurance
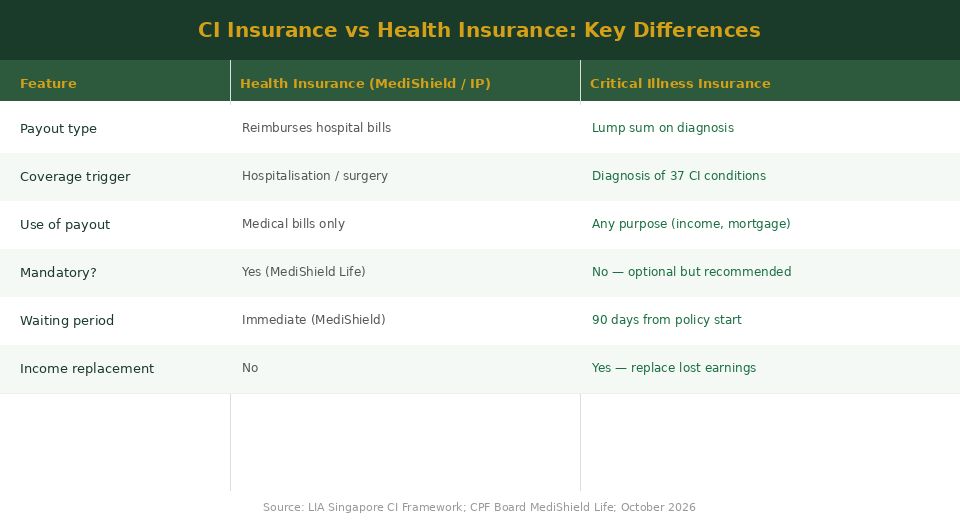
Source: LIA Singapore CI Framework; CPF Board MediShield Life; October 2026
The table above captures the headline differences. The most critical distinction: payout type. Health insurance reimburses bills — it has no use if your bills are below the deductible. CI insurance pays regardless of actual costs.
Use of funds is where CI insurance provides unique value. After a cancer diagnosis, your immediate financial shock is not necessarily the chemotherapy bill (which your IP may largely cover). It is the fact that you cannot work for the next 12 months. CI insurance bridges that income gap; health insurance does not.
The mandatory vs optional distinction leads many people to assume MediShield Life is “enough.” It is not — it was never designed to replace lost income or cover non-medical recovery costs.
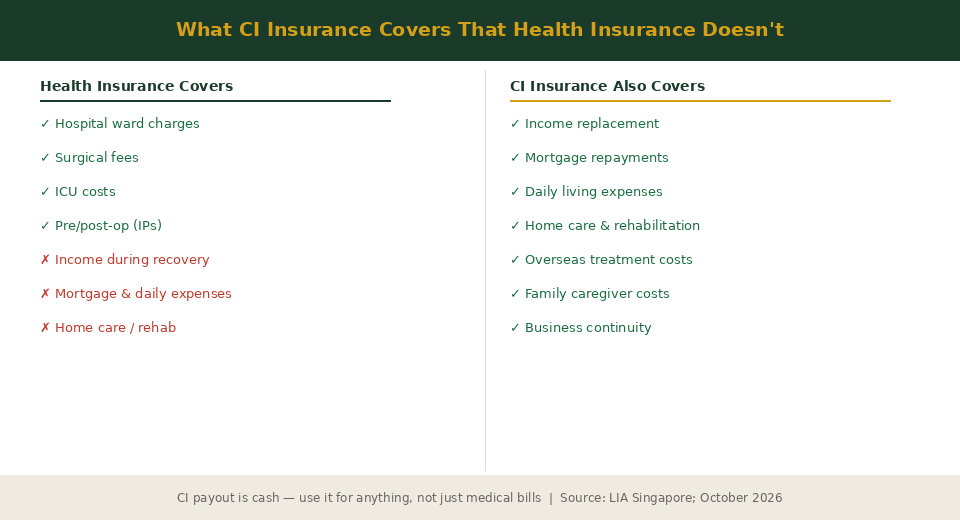
What Health Insurance Does Not Cover (The CI Gap)
Source: LIA Singapore; CPF Board; October 2026
To make the coverage gap concrete, consider a real scenario:
Example: 40-year-old Singaporean diagnosed with Stage 3 breast cancer
| Cost Item | Amount | Covered by Health Ins? |
|---|---|---|
| Hospital bills (surgery + chemo + targeted therapy) | S$280,000 | ~S$240,000 (MediShield + IP) |
| Remaining bill gap | ~S$40,000 | No |
| Lost income (18 months at S$5,000/mo) | S$90,000 | No |
| Home care aide (12 months) | S$24,000 | No |
| Home modification & travel for treatment | S$14,000 | No |
| Total uncovered exposure | ~S$168,000 | Health insurance: No |
Illustrative scenario. Actual costs vary by treatment centre, ward class and individual circumstances. October 2026.
A S$300,000 CI policy would cover this entire exposure with S$132,000 remaining as a buffer. Without CI insurance, this family would need to liquidate savings or investment assets during a period when they are least able to manage financial stress.
Do You Need Both Health Insurance and CI Insurance?
Yes — for most working Singaporeans, both are necessary. They cover fundamentally different financial risks and are not substitutes for each other.
The question is not “CI or health insurance?” It is “how much of each?”
MediShield Life you already have — it is mandatory. The first decision is whether to upgrade to an Integrated Shield Plan and, if so, which ward class to target and whether to add a rider.
The second decision is whether to buy CI insurance and, if so, how much sum insured to target. Most MAS-licensed financial advisers benchmark CI coverage at 5x annual income for working adults — enough to replace roughly five years of salary during recovery.
Health insurance covers your bills.
CI insurance covers your life.
You need both — they are not alternatives.
One practical note: you cannot use CPF MediSave to pay for standalone CI insurance premiums (MediSave can only fund MediShield Life and IP premiums). CI insurance premiums are paid in cash. To estimate how much income replacement you would need after a critical illness diagnosis, use our Singapore retirement planning calculator. For passive income strategies to support your financial resilience, see our guide to passive income in Singapore.
Which Should You Buy First?
If budget is a constraint and you can only address one type of insurance at a time, the standard sequence:
- MediShield Life — already mandatory, no action required
- Integrated Shield Plan (IP) — upgrade to at least Class A ward coverage; add a rider to reduce co-insurance if budget allows
- Term life insurance — if you have dependants who rely on your income
- Critical illness insurance — after the above, prioritise CI coverage based on your income level and family obligations
Buy CI insurance while you are young and healthy. Premium rates are set at the point of purchase based on your age and health status. A 30-year-old non-smoker buys the same S$300,000 CI sum insured for roughly half the annual premium of a 45-year-old. And conditions that develop over time — high blood pressure, diabetes, high cholesterol — can lead to permanent exclusions if they appear before you buy.
To understand when the best age is to buy, read our guide on when to buy critical illness insurance in Singapore. For term life insurance decisions alongside CI, see our guide on term life insurance vs HPS vs MRTA for Singapore homeowners.
How Much of Each Do You Need?
| Insurance Type | Benchmark Coverage | Why |
|---|---|---|
| MediShield Life | Provided at enrolment | B2/C ward baseline; no decision needed |
| Integrated Shield Plan | Class A ward or private hospital | Eliminates ward class stress during illness; rider recommended |
| CI Insurance | 5× annual income (min S$200,000) | Covers ~5 years of income replacement and recovery costs |
| Early CI rider | Optional top-up | LIA covers late stage only; early CI requires separate benefit |
Source: LIA Singapore; CPF Board; MAS guidance; illustrative benchmarks as at October 2026. Speak to a MAS-licensed adviser for personalised amounts.
One frequently overlooked point: the LIA’s 37 standard CI conditions cover late-stage critical illness by definition. Early-stage cancer (e.g. carcinoma in situ) and early-stage heart conditions are not covered under the standard framework. If you want coverage for early-stage diagnoses, you need a separate early CI benefit. Our guide on early vs late-stage CI insurance in Singapore covers this in full.
For exclusions and conditions that can void a CI claim, see our guide on what critical illness insurance does not cover in Singapore.
Disclaimer: Premium estimates and coverage benchmarks above are illustrative ranges based on market norms as at October 2026. Actual figures vary by insurer, age, health status, occupation, and plan structure. This article is for educational reference only. Speak to a MAS-licensed financial adviser for advice tailored to your situation.
Frequently Asked Questions: CI Insurance vs Health Insurance Singapore
What is the main difference between critical illness insurance and health insurance?
Can critical illness insurance replace health insurance?
Does MediShield Life cover all hospitalisation costs?
Can I use CPF MediSave to pay for critical illness insurance?
What are the 37 critical illnesses covered under the LIA framework?
How much critical illness insurance do I need in Singapore?
Does critical illness insurance pay out if health insurance already covered my bills?
Get Free Insurance Advice
Speak with a licensed insurance advisor. No obligation, no cost.
By submitting this form, you agree to our Privacy Policy.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.