Term Life Insurance Singapore 2026: Why Your Age Matters More Than Your Insurer Choice
Compare premiums by age — and see how much delaying really costs you.
Term life insurance in Singapore is one of the most price-sensitive purchases you will ever make — and the single biggest driver of your premium is not your choice of insurer, but your age at the point of entry. A 35-year-old male non-smoker can secure S$500,000 of coverage for as little as S$388 per year through FWD. Wait until 45 and the same coverage costs roughly S$950 per year — a difference that compounds to over S$14,000 in lifetime premiums for an identical 20-year policy. This guide breaks down the age-premium relationship with real 2026 data.
Not financial advice. All figures are indicative for standard health profiles and are for educational reference only. Data as at Q3 2026 unless noted. Always obtain a personalised quote before purchasing any insurance policy. Data verified as at 29 September 2026.
Table of Contents
Contents — Click to expand
- Why Age Is the #1 Premium Driver in Singapore
- 2026 Premium Comparison by Age (4 Major Insurers)
- The Real Cost of Delaying: A 20-Year Calculation
- Which Insurer Is Cheapest at Each Age?
- Women Pay Less: The Gender Premium Gap
- When Is the Right Age to Buy? (Decision Framework)
- How to Compare Plans in Singapore (Step-by-Step)
- Frequently Asked Questions
Why Age Is the #1 Premium Driver in Singapore
Most Singaporeans shopping for term life insurance spend hours comparing insurers — but the data shows that your entry age has a far greater impact on your lifetime cost than your choice of insurer. Here is why.
Term life insurance pricing is fundamentally actuarial: the older you are, the higher the statistical probability that the insurer will have to pay a claim during your policy term. Singapore’s insurers use the Singapore Standard Ordinary (SSO) mortality table, updated periodically by the Life Insurance Association Singapore (LIA Singapore), to underpin their pricing models. As mortality risk rises with age, so does the level premium charged for each new policy year of entry.
Unlike some markets where premiums increase annually, most Singapore term life plans lock in a level premium for the entire policy term — meaning the premium you pay at entry stays constant for 20, 25, or 30 years. This makes your entry age not just a pricing variable, but a decision that compounds across decades.
A useful way to think about it: for every five years you delay, your annual term life premium typically rises by 40–80% for the same coverage amount. Between ages 35 and 45 — the window when most Singaporeans are building careers, buying HDB flats, and starting families — the increase is particularly steep.
2026 Premium Comparison by Age (4 Major Insurers)
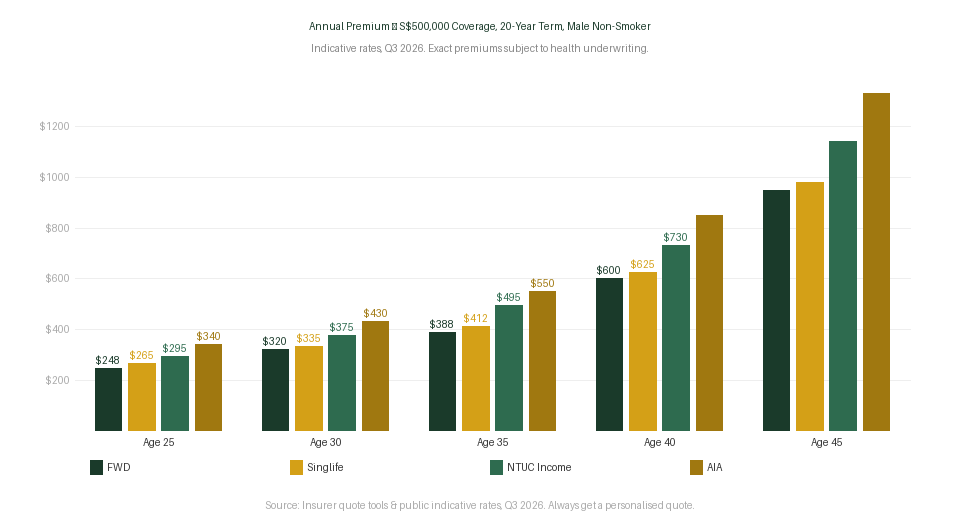
The table below shows indicative annual premiums for a male non-smoker seeking S$500,000 of death and TPD coverage on a 20-year term, across four major Singapore insurers as at Q3 2026. Female premiums are typically 30–35% lower.
| Age at Entry | FWD Term Life | Singlife Elite Term II | NTUC Income TermLife | AIA Secure Flexi Term |
|---|---|---|---|---|
| 25 | ~S$248 | ~S$265 | ~S$295 | ~S$340 |
| 30 | ~S$320 | ~S$335 | ~S$375 | ~S$430 |
| 35 | ~S$388 | ~S$412 | ~S$495 | ~S$550 |
| 40 | ~S$600 | ~S$625 | ~S$730 | ~S$850 |
| 45 | ~S$950 | ~S$980 | ~S$1,140 | ~S$1,330 |
Source: Insurer indicative quote tools and public rate comparisons, Q3 2026. Premiums are indicative for standard health profiles (non-smoker, no pre-existing conditions). Actual premiums are subject to underwriting and may differ. All figures rounded to nearest S$5.
The jump from age 35 to age 45 is striking: FWD premiums increase by 145% — from S$388 to S$950 per year. AIA’s increase over the same decade is 142% (S$550 → S$1,330). What is notable is that the percentage increase is broadly similar across insurers — the cheapest insurer at 35 (FWD) remains cheapest at 45, suggesting that mortality tables, more than insurer pricing strategy, drive the age-premium curve.
The Real Cost of Delaying: A 20-Year Calculation
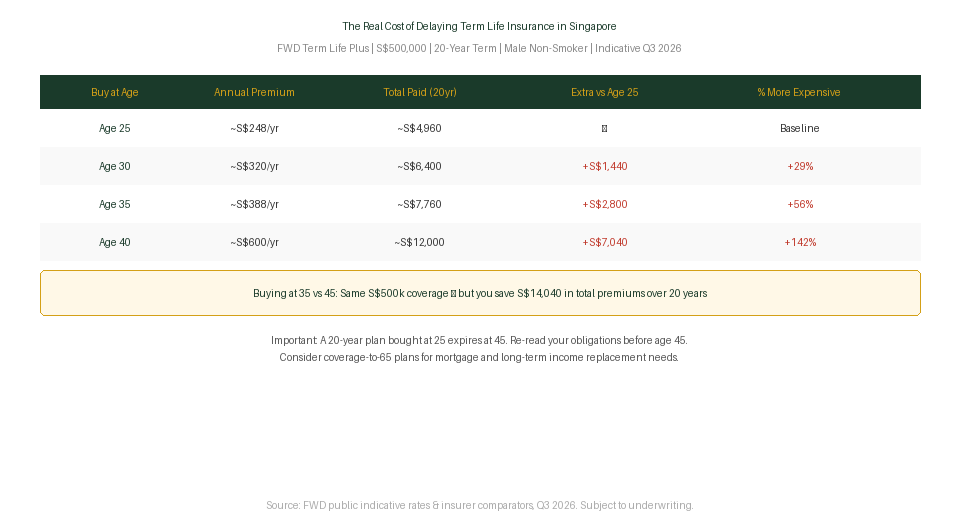
To make the impact concrete, consider a Singapore male aged 35 deciding whether to buy term life insurance now or wait five or ten years. Using FWD’s indicative premiums:
- Buy at 35: S$388/year × 20 years = S$7,760 total (coverage to age 55)
- Buy at 40: S$600/year × 20 years = S$12,000 total (coverage to age 60)
- Buy at 45: S$950/year × 20 years = S$19,000 total (coverage to age 65)
Waiting from 35 to 45 costs an additional S$11,240 in premiums for the same S$500,000 face value — money that would come out of your family’s pocket with no additional benefit. And that figure assumes you remain insurable at 45: any change in health status (common in your 40s) could result in exclusions, higher loading charges, or outright rejection.
For those who could not afford coverage at 25 or 30, the lesson is still actionable: every year you delay past 35 adds roughly S$45–S$80 per year to your annual premium for this level of coverage. Lock in your best term life insurance Singapore 2026 rate while you are in good health.
Which Insurer Is Cheapest at Each Age?
Based on Q3 2026 public indicative rates, FWD Term Life Plus consistently offers the lowest premiums across all standard age groups for S$500,000 of death and TPD cover. Singlife Elite Term II is a close second at every age. The gap between these two digital-first insurers and the traditional players (NTUC Income, AIA, Great Eastern, Prudential) typically ranges from 20–40%.
However, cheapest is not always best. The traditional insurers often include broader underwriting flexibility, stronger claims track records, and more comprehensive rider ecosystems. If you need a critical illness rider or a convertible term policy, the full term life insurance Singapore comparison with rider analysis may point you to NTUC Income TermLife Solitaire or Great Eastern GREAT Term 2 instead.
A practical rule: use FWD or Singlife as your price benchmark, then ask whether any rider you need (CI, premium waiver, accidental death benefit) changes the net cost advantage.
Women Pay Less: The Gender Premium Gap
Female applicants enjoy significantly lower term life premiums in Singapore — typically 30–35% less than equivalent male premiums for the same age, sum assured, and policy term. This reflects actuarial data showing longer female life expectancy and lower mortality rates across the policy’s active coverage period.
For a 35-year-old female non-smoker seeking S$500,000 coverage on a 20-year term, indicative premiums run from approximately S$265–S$280 per year (FWD, Singlife) to S$340–S$380 (NTUC Income, AIA). The age-sensitivity pattern is broadly similar — premiums still roughly double between 35 and 45 — but the absolute dollar amounts are lower, making the urgency to buy early slightly less acute financially, though no less important from a coverage standpoint.
Couples should note that purchasing individual plans (rather than a joint plan) typically allows each partner to optimise their own coverage amount and term length. Our couples’ term life insurance guide covers the optimal structuring for dual-income households in Singapore.
When Is the Right Age to Buy? (Decision Framework)
Rather than offering a single prescriptive answer, here is a decision framework used by Singapore fee-only financial advisers:
Buy immediately if you:
- Have dependants (spouse, children, elderly parents) who rely on your income
- Have an outstanding HDB or private property mortgage
- Are between 25–40 years old and currently healthy
- Have any business loan or personal liability that your family would inherit
Consider delaying only if:
- You are genuinely single with no dependants and no liabilities — and plan to remain so for several years
- You have sufficient liquid assets (typically 5–10× annual income) to self-insure in the short term
- You are already over 55, have no dependants, and your mortgage is paid off
The default answer for most Singaporeans between 28 and 45 is: buy now. The premium savings from acting early far outweigh any short-term cash flow concern. A S$388/year policy is less than S$33/month — roughly the cost of one hawker lunch per week.
If you are unsure how much coverage you need, use the Singapore retirement calculator to model your family’s income replacement requirement, then layer the life insurance coverage decision on top of your retirement planning numbers.
How to Compare Plans in Singapore (Step-by-Step)
Here is a practical step-by-step process for finding the right term life plan at the right age:
Step 1: Define your coverage needs. Calculate your human life value (HLV) — typically 10–15× your annual income, adjusted for outstanding debt and your spouse’s earning capacity. A household income of S$80,000/year with a S$500,000 HDB mortgage would need at least S$800,000–S$1.2M in coverage.
Step 2: Choose your policy term. Match coverage to your longest financial obligation. If your HDB loan runs until you are 65, buy a plan that covers you to 65. Don’t over-insure beyond your obligations — but don’t under-insure either.
Step 3: Get quotes from at least three insurers. Start with FWD and Singlife for price benchmarks (both offer direct online quotes). Then approach NTUC Income or Great Eastern for a comparison if you need riders. Both FWD term life insurance and AIA term life insurance are reviewed in detail on TKN.
Step 4: Check MAS licensing. All insurers offering term life in Singapore must be licensed by MAS. Verify before purchasing — especially for newer digital insurers.
Step 5: Submit your application early. Underwriting can take 2–6 weeks if medical records or a GP check is required. Apply before your next birthday to lock in the lower premium band, as most insurers use your age at the next birthday (age nearest birthday) in their calculations.
Disclaimer: The figures and comparisons in this article are for educational reference only. The Kopi Notes is not a licensed financial adviser. Always consult a qualified adviser or the insurer directly before making a purchase decision.
Frequently Asked Questions
At what age should I buy term life insurance in Singapore?
The earlier the better, but the most impactful window is between ages 25 and 35. In this range, premiums are at their lowest and your health profile is most likely to qualify you for standard rates without exclusions. Most Singapore financial planners recommend purchasing when you take on your first major financial liability — typically a BTO flat, a new job with dependants, or marriage. Every year you delay past 35 meaningfully increases your lifetime premium cost.
How much does term life insurance cost for a 30-year-old in Singapore?
For a 30-year-old male non-smoker seeking S$500,000 of coverage on a 20-year term, indicative annual premiums in Singapore range from approximately S$320 (FWD Term Life Plus) to S$430 (AIA Secure Flexi Term) as at Q3 2026. Female equivalents are typically 30–35% lower. These are indicative figures for standard health profiles — your actual premium will depend on your health history, occupation, and the specific plan selected. Always obtain a personalised quote from the insurer.
Why do term life insurance premiums double between 35 and 45?
The doubling reflects actuarial mortality data: the probability of dying during the policy term increases significantly between ages 35 and 45 due to higher incidence of cardiovascular disease, cancer, and other lifestyle-related conditions. Singapore insurers use the Singapore Standard Ordinary (SSO) mortality table to price policies. Because term life premiums are locked in at your entry age and remain level throughout the policy, the insurer charges a higher flat rate for older entrants to account for elevated risk across the policy’s entire duration.
Is FWD term life insurance actually the cheapest in Singapore?
Based on Q3 2026 indicative rates for standard health profiles, FWD Term Life Plus is consistently among the lowest-priced term life options in Singapore across age groups 25–50, closely followed by Singlife Elite Term II and Etiqa iTerm Life. However, “cheapest” depends on your specific age, sum assured, policy term, and whether you need riders (critical illness, premium waiver, etc.). For a plain death and TPD policy with no riders, FWD and Singlife are strong benchmarks. If you need a bundled critical illness rider, NTUC Income or Great Eastern may offer better overall value.
Can I buy term life insurance at age 45 or 50 in Singapore?
Yes — most Singapore insurers accept new applications up to age 65–70 (entry age varies by plan), though premiums at 45+ are significantly higher and some plans may have tighter underwriting requirements. If you have pre-existing conditions, you may face exclusions or loadings that further increase cost. At age 45 or above, it is particularly important to compare plans carefully and consider whether the premium-to-benefit ratio remains worthwhile for your specific obligations. Use a fee-only MAS-licensed financial planner to model whether self-insuring (via existing assets) is more cost-efficient at this stage.
How does age affect term life insurance premiums for women in Singapore?
Women in Singapore pay approximately 30–35% less than men of the same age for the same coverage amount and policy term, reflecting actuarial data on lower female mortality rates. The age-escalation pattern is similar: premiums still roughly double between age 35 and age 45 for women, but the absolute dollar amounts are lower. For example, a 35-year-old female non-smoker seeking S$500,000 coverage on a 20-year term might pay approximately S$265–S$280 per year (FWD, Singlife) vs S$388–S$412 for a male equivalent. Female premiums are also typically lower for critical illness and disability income riders.
Ready to Lock In Your Rate Today?
Every year you wait adds to your lifetime premium cost. Compare plans, get a personalised quote, and secure your family’s protection now.
Get Free Insurance Advice
Speak with a licensed insurance advisor. No obligation, no cost.
By submitting this form, you agree to our Privacy Policy.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.