TribeCar + FSMOne + MariBank + GXS + IBKR: Ranking Exit Friction (2026)
Opening these five accounts takes minutes. Closing them — and getting every dollar back — is a very different story.
Among TribeCar, FSMOne, MariBank, GXS and IBKR, GXS and MariBank are the easiest to exit — both close digitally in under a day once your balance is zero. TribeCar is the hardest: termination runs through a mailed physical form, and the refundable S$100 deposit can take up to 45 working days to return, plus a S$5 withdrawal charge. IBKR sits second-hardest, since every position must be sold and every cent withdrawn before the account can close at all. Ranking all five by closure method, balance prerequisites and real payout time shows which platform to think twice about before you fund it.
Not financial advice. Account closure processes, fees and processing times change as platforms update their policies — details below were verified in October 2026, so always check the current closure terms on each platform’s own help centre before you start.
Table of Contents
Contents — Click to expand
- The exit friction score, side by side
- GXS (YONG477) — close in-app, under a day
- MariBank (2DCT80WQ) — facial verification, same-day
- FSMOne (P0544985) — zero-balance rule first
- IBKR (jianxiong368) — liquidate everything, then wait
- TribeCar (zZDeg) — the hardest exit of the five
- Days until every dollar is back
- What this means before you fund any of them
- FAQ
The Exit Friction Score, Side by Side
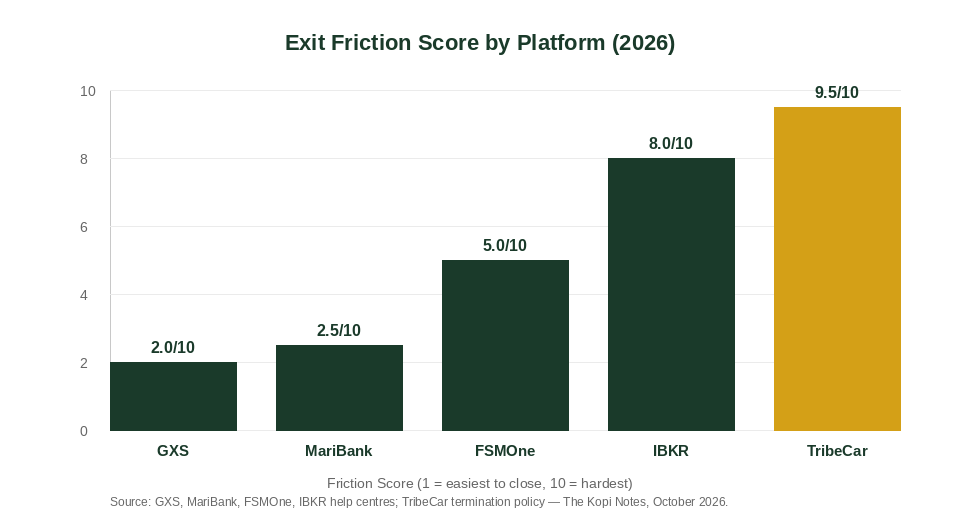
Most comparison articles rank these platforms on how fast you can join. This one ranks the opposite: how hard it is to leave. “Exit friction” combines three things — the closure method itself (app, form, mail), what has to be true about your balance before you’re even allowed to close, and how long the final payout actually takes once you’ve asked. Lower score means an easier, faster exit. Here’s the honest breakdown as at October 2026:
| Platform | Closure Method | Balance Prerequisite | Exit Friction Score |
|---|---|---|---|
| GXS | In-app chat or hotline request | Close all Saving/Boost Pockets, transfer out balance | 2.0 / 10 |
| MariBank | In-app closure form + Singpass facial verification | Transfer out balance, remove eGIRO arrangements | 2.5 / 10 |
| FSMOne | Written closure request to FSMOne | Zero account balance — sell all CDP holdings first | 5.0 / 10 |
| IBKR | Account Management closure request | Liquidate every position, withdraw all cash to $0 | 8.0 / 10 |
| TribeCar | Mailed physical termination form to support@tribecar.com | S$100 deposit refund requested separately, S$5 admin fee | 9.5 / 10 |
Source: GXS Help Centre, MariBank Help Centre, FSMOne account policies, IBKR closing-account guide, TribeCar termination policy — verified by The Kopi Notes, October 2026.
GXS (Code YONG477) — Close In-App, Under a Day
GXS is the easiest of the five to leave, which lines up with it also being one of the fastest to join in the first place. Before closing, you need to close any Saving Pocket or Boost Pocket you’ve created and transfer the remaining balance to another bank account — GXS’s help centre is explicit that recurring payment arrangements stop the moment the account closes, and once closed, you cannot reinstate or reapply for the same GXS Savings Account. The actual closure request itself is simple: raise it through GXS Chat in the app (GXS’s own recommended route) or call the hotline at 1800 866 6685. There’s no early closure penalty stated anywhere in GXS’s account terms. Enter referral code YONG477 if you haven’t opened the account yet — see our full GXS Bank review for how the Boost Pocket and Saving Pocket rates work while you’re still using it.
MariBank (Code 2DCT80WQ) — Facial Verification, Same-Day
MariBank’s closure process is almost as light as GXS’s, just with one extra identity-verification step. You submit an Account Closure Request Form in the app, then complete a Singpass Facial Verification that must finish within 10 minutes of starting it — fail that window and you’ll need to restart the request. Before you get there, MariBank requires you to transfer out any remaining balance, download any e-Statements you still need (they won’t be accessible after closure), and delete all active eGIRO arrangements. You can also initiate closure through in-app live chat or the hotline at +65 6995 8688 if you’d rather talk to someone than go through the form. Once closed, the account cannot be reinstated or used for any further banking services — a pattern consistent across every digital bank on this list. See our full MariBank review for how the savings rate and Mari Invest options work while the account is still open. Code 2DCT80WQ gets you the sign-up bonus if you’re opening fresh.
FSMOne (Code P0544985) — Zero-Balance Rule First
FSMOne’s own closure requirement is simple to state and genuinely inconvenient to execute if you’re holding investments: your account must sit at a zero balance before FSMOne will process closure. If your cash is already sitting uninvested, this is nearly instant. If you’re holding unit trusts or CDP-settled shares through FSMOne, you first have to sell everything, then wait — CDP securities sale proceeds are credited to your Cash Account on a T+2 settlement basis, meaning two business days after the trade before the money is even available to withdraw. Only once that cash clears and the account reads zero can you submit the closure request itself. That settlement wait is the entire reason FSMOne scores higher friction than GXS or MariBank — the closure request itself isn’t the bottleneck, the forced liquidation-and-settlement sequence is. See our FSMOne login walkthrough if you’re still active on the platform and want to check your current holdings before starting this process. Code P0544985 applies if you’re signing up new.
IBKR (Code jianxiong368) — Liquidate Everything, Then Wait
Interactive Brokers has the strictest prerequisite on this list: you cannot close the account at all until you’ve sold every single position and withdrawn every dollar of cash down to zero. For a Singapore investor holding a diversified VWRA/CSPX-style portfolio, that alone can take days if you’re trying to avoid dumping everything at a bad moment. Once you’re ready to withdraw, IBKR’s own processing typically takes about two business days for an electronic transfer with up-to-date banking instructions — though US-base-currency accounts with a US address may instead be issued a cheque within up to 10 business days. Add the liquidation, settlement and withdrawal stages together and IBKR’s own guidance is that the full closure process can take up to a few weeks from start to finish. One more wrinkle: IBKR keeps your account open for three months after your final withdrawal, purely to collect any trailing fees, dividends or corporate actions, before closing it permanently — you don’t need to do anything during that window, but it means “closed” isn’t instant even after your money is gone. IBKR doesn’t charge a separate account-closure fee, but liquidating or transferring positions can carry its own charges. For what you get in exchange for that exit friction, see our IBKR vs moomoo comparison. Code jianxiong368 applies on sign-up.
TribeCar (Code zZDeg) — The Hardest Exit of the Five
TribeCar is the outlier on this list, and not in a good way. Where every digital bank and broker above lets you close entirely inside an app, TribeCar’s termination process runs through a physical form: you email support@tribecar.com to request the termination form, fill it out, and mail it back before the account can be closed. The bigger friction point is your refundable S$100 security deposit — getting it back can take up to 45 working days, by far the longest payout window of any platform in this comparison, and users consistently flag it as slower and more manual than every other step in the app. On top of the wait, withdrawing the deposit itself incurs a S$5 administrative charge even if you never made a single booking, and a lost cheque requiring reissue adds a further S$20 cancellation charge. It’s a strange contrast: TribeCar was one of the fastest apps to join in our onboarding friction ranking — roughly two minutes to sign up — but it’s the single hardest one to fully leave. Code zZDeg gets you S$20 off your first booking if you’re signing up, but budget for the 45-day tail on the way out.
Days Until Every Dollar Is Back
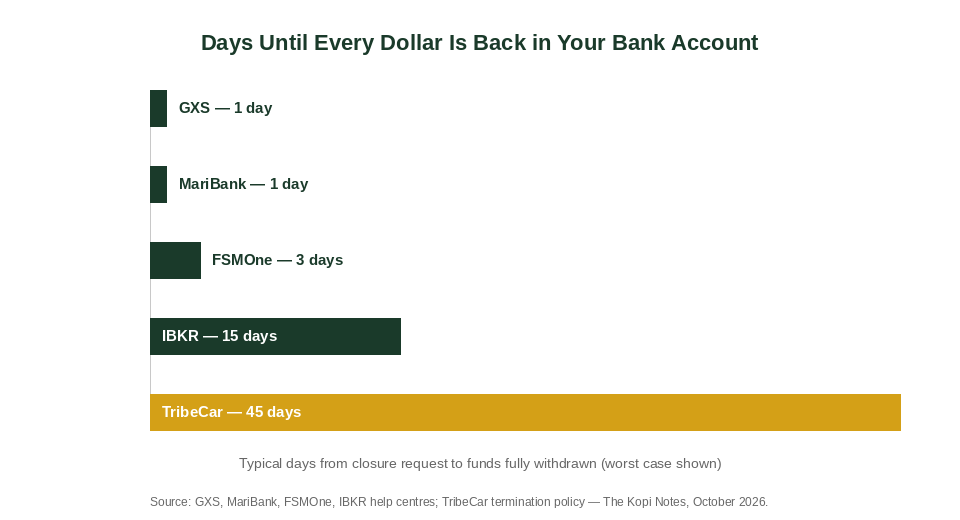
Scoring friction is useful, but what actually matters to your wallet is time: how many days pass between asking for your money and having it sit in your own bank account. Lined up this way, the gap between the top two and the bottom one is stark — GXS and MariBank return your balance same-day or next-day once the closure request is processed, while TribeCar’s deposit can take forty-five times longer.
| Rank | Platform | Typical Payout Window | Biggest Friction Point |
|---|---|---|---|
| 1 | GXS | ~1 day | Must close pockets first — otherwise none |
| 2 | MariBank | ~1 day | 10-minute facial verification window |
| 3 | FSMOne | ~3 days | T+2 settlement if holdings must be sold first |
| 4 | IBKR | Up to ~15 days (full process: weeks) | Must liquidate all positions before closure |
| 5 | TribeCar | Up to 45 working days | Mailed physical form + slow deposit refund + S$5 fee |
Source: GXS, MariBank, FSMOne and IBKR help centres; TribeCar termination policy — The Kopi Notes, October 2026.
What This Means Before You Fund Any of Them
Exit friction doesn’t mean “don’t use the platform” — it means fund it with that friction in mind:
Keep GXS and MariBank for money you might need back on short notice. Both return your balance within roughly a day of a clean closure request, so they’re the right home for an emergency buffer or short-term parking, not just a bonus-chasing account you forget about.
Treat FSMOne and IBKR as genuinely locked-in once invested. The friction isn’t in the closure request — it’s in the forced sell-everything-first rule. Don’t put money into either platform that you might need to pull out whole and fast; plan for a multi-day-to-multi-week unwind if you ever do close the account.
Size your TribeCar deposit with the 45-day tail already priced in. The S$100 deposit isn’t large, but if you’re the type who opens and closes accounts to chase referral bonuses, TribeCar is the one platform on this list where that habit gets expensive and slow. Keep the deposit in if you’ll actually use the car-sharing service; don’t open it purely for the S$20 referral credit if you plan to close it again soon after.
None of this is a reason to avoid any of the five — it’s simply the other half of the picture that a joining-speed comparison alone doesn’t show you.
Claim the Five Codes
FAQ
Which of the five is genuinely the easiest to close?
Why does TribeCar take so much longer than the digital banks and brokers?
Do I really have to sell everything before I can close my IBKR account?
Is FSMOne's zero-balance rule the same as IBKR's?
Does closing one of these accounts affect my referral bonus from the others?
Should exit friction stop me from opening any of these accounts?
The Bottom Line
GXS and MariBank are the two accounts you can treat like a true emergency buffer — closed and refunded within a day. FSMOne and IBKR need a plan: sell down before you need the cash, not after. And TribeCar’s deposit deserves real patience — budget for up to 45 working days, not 45 hours, if you ever decide to close it.
See our CPF retirement sum guide for where money freed from a closed account can go next, or read our Best Investment App Singapore comparison for how these brokerage and robo apps stack up on fees before you even open one.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.