MediSave for Hospitalisation Singapore: Step-by-Step Claim Guide (2026)
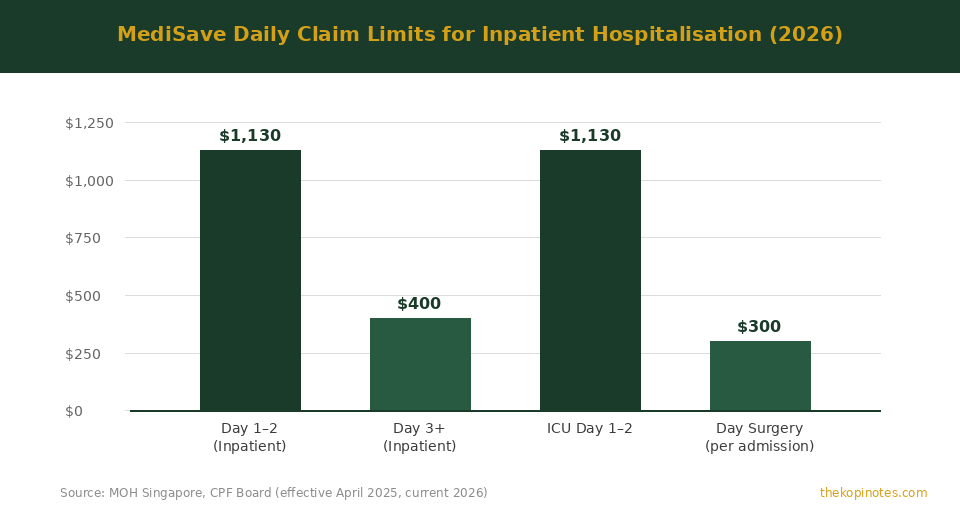
MediSave covers your hospitalisation bills up to $1,130 per day for the first two days, then $400 per day from day three onwards. This applies to all inpatient stays in Singapore public and private hospitals. For most C-class and B2 ward admissions, MediSave alone can cover a large chunk of your bill — but for higher ward classes or longer stays, an Integrated Shield Plan (ISP) bridges the gap. Data verified as at 15 September 2026.
Not financial advice. All figures are for educational reference only. Confirm current limits at CPF Board’s official MediSave page.
- MediSave pays $1,130/day for days 1–2 of inpatient stay, $400/day from day 3.
- You don’t need to do anything — your hospital claims directly from your MediSave at discharge.
- After April 2026 ISP rider changes, your out-of-pocket co-payment cap is now $6,000/year for new riders.
- What MediSave Covers for Hospitalisation
- MediSave Daily Claim Limits 2026
- Step-by-Step: How the Claim Process Works
- April 2026 ISP Rider Changes: What Changed
- MediSave vs ISP: How They Work Together
- Worked Examples: Real Hospital Bill Scenarios
- 5 Tips to Maximise Your MediSave for Hospitalisation
- Frequently Asked Questions
What MediSave Covers for Hospitalisation
Your MediSave Account (MA) is the CPF account set aside specifically for healthcare. Every working Singaporean and PR contributes a portion of their CPF monthly into MediSave.
For hospitalisation, MediSave covers a wide range of expenses. This includes inpatient ward charges, day surgery, and approved surgical procedures. It also covers certain outpatient treatments like chemotherapy, dialysis, and radiosurgery.
Here’s what MediSave does and does not cover for hospital stays:
| Covered by MediSave | NOT Covered by MediSave |
|---|---|
| Inpatient ward charges (daily limit applies) | Outpatient GP or specialist visits (most cases) |
| Day surgery procedures | Cosmetic surgery |
| Approved surgical operations (procedure-specific limits) | Dental (except hospital-based procedures) |
| Chemotherapy, dialysis, radiosurgery | Vitamins and supplements |
| ISP premiums (up to the annual withdrawal limit) | Private nursing home fees (limited coverage only) |
Source: CPF Board, MOH Singapore, September 2026
For surgical procedures, MediSave follows a Table of Surgical Procedures (TOSP) classification system. Each procedure has a specific dollar limit. Your hospital bills to MediSave based on whichever is lower — the actual charge or the TOSP cap.
MediSave Daily Claim Limits 2026
Here are the current MediSave daily withdrawal limits for inpatient hospitalisation. These limits have been in effect since April 2025 and remain unchanged for 2026.
$400 per day from Day 3 onwards
| Type of Admission | MediSave Daily Limit | Notes |
|---|---|---|
| Inpatient (Days 1–2) | $1,130 / day | Applies to ward charges |
| Inpatient (Day 3 onwards) | $400 / day | Lower limit from day 3 |
| ICU (Days 1–2) | $1,130 / day | ICU follows same limits |
| Day Surgery | $300 per admission | Plus surgical procedure limit |
| Surgical Procedures | $250–$7,550 | Depends on TOSP table classification |
Source: CPF Board, MOH Singapore (2026 schedule). Limits apply per admission.
These limits are separate from your ISP rider benefits. Think of MediSave as the first layer of coverage. Your ISP then tops up the remaining bill, subject to deductibles and co-insurance.
Step-by-Step: How the MediSave Claim Process Works
The good news: you don’t actually need to do much. Your hospital handles the MediSave claim on your behalf at discharge. But it helps to understand the process, especially if you also have an ISP.
Step 1 — Admission
When you check in, let the hospital admissions team know you want to use MediSave and your ISP (if applicable). Provide your NRIC. The hospital will verify your MediSave balance and ISP details directly.
Step 2 — During Your Stay
Keep all receipts and billing summaries. If you’re in a private or restructured hospital with an ISP, the hospital will submit pre-authorisation requests to your insurer. You don’t need to coordinate this yourself in most cases.
Step 3 — Discharge and Bill Settlement
At discharge, the hospital presents your itemised bill. This breaks down into:
- MediShield Life payable — the compulsory base insurance component
- MediSave deduction — drawn from your CPF MediSave Account
- ISP insurer payable — if you have an ISP, your insurer pays this portion directly to the hospital
- Your out-of-pocket cash — what remains after all the above
Step 4 — Post-Discharge Statement
About 3–5 working days after discharge, CPF Board sends you a MediSave statement showing exactly how much was deducted. You can also check this via the CPF mobile app or my CPF online portal.
Step 5 — Any Disputes
If you think the bill is wrong, contact the hospital’s billing department first. For ISP disputes, contact your insurer directly. The Financial Dispute Resolution Centre (FDRC) handles unresolved insurance disputes.
The whole process sounds complex, but in practice, most hospitalisation bills are settled at discharge within 30–60 minutes. The hospital does the heavy lifting.
April 2026 ISP Rider Changes: What Changed
From 1 April 2026, MOH introduced new rules for Integrated Shield Plan riders sold after that date. These changes significantly affect how your out-of-pocket costs work.
Here’s a quick summary of what changed:
| Feature | Before April 2026 | From April 2026 (New Riders) |
|---|---|---|
| Deductible coverage | Riders could cover 100% of deductible | Riders cannot cover the minimum deductible |
| Co-payment cap (annual) | $3,000 / year | $6,000 / year |
| Rider premiums (approx) | Higher | ~30% lower on average for new riders |
| Grandfathered riders | N/A | Riders bought before November 2025 announcement are grandfathered in |
Source: MOH Singapore, November 2025 announcement. Effective April 1, 2026 for new riders sold from that date.
What this means for you: If you bought your rider before November 2025, nothing changes — you’re grandfathered in. If you buy a new rider from April 2026 onwards, you’ll pay the deductible yourself (MediSave can cover this), and your maximum annual co-payment is now capped at $6,000 instead of $3,000.
The trade-off: your rider premium is about 30% cheaper. For most healthy Singaporeans who rarely claim, this is actually a better deal. For frequent hospitalisation, the old full-coverage riders were more cost-effective if you still have one.
You can read the full breakdown in our article on MediSave hospitalisation claim limits and rider changes.
MediSave vs ISP: How They Work Together
Think of it as layers of protection:
- MediShield Life — your compulsory base coverage. Covers a portion of B2 and C ward bills.
- MediSave — your personal healthcare savings. Pays the deductible and co-insurance portions.
- ISP — optional private insurance. Covers higher ward classes and larger bills beyond MediShield Life limits.
- ISP Rider — optional add-on to your ISP. Reduces or caps your out-of-pocket co-payment (subject to the new 2026 rules).
If you only have MediShield Life (no ISP), you’ll stay in a B2 or C ward and pay the balance not covered by MediShield Life using MediSave and cash.
If you have an ISP with a rider, you can choose a higher ward class (Class A or private room) and your out-of-pocket costs are capped at $6,000 per year under the new 2026 rider rules — or lower if you were grandfathered under old rules.
To explore which ISP suits you, check our guide on the best shield plans in Singapore. And if you’re evaluating specific insurers, our Singlife Shield Plan review and PRUShield review cover the key comparisons.
Worked Examples: Real Hospital Bill Scenarios
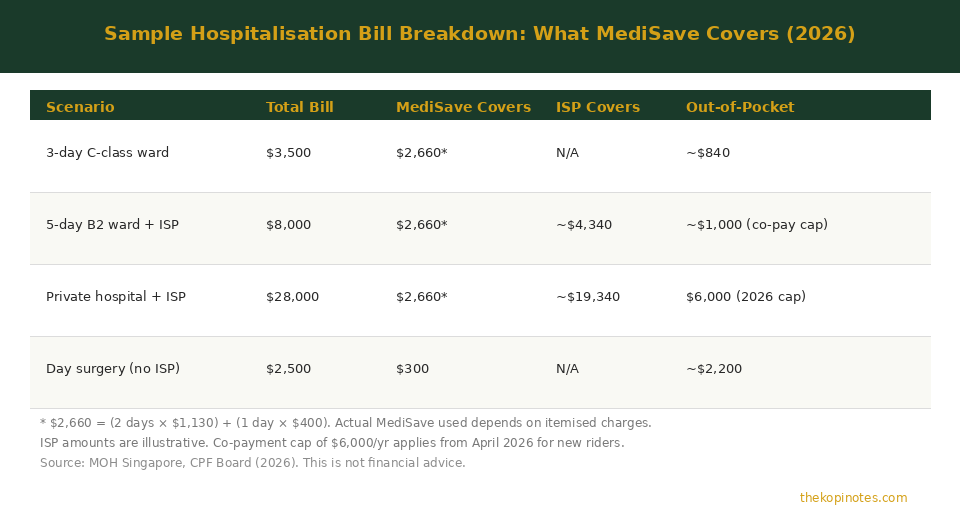
Let’s walk through three realistic hospital stays to show exactly how MediSave and ISP interact.
Scenario A — 3-Day C-Class Ward (No ISP)
You spend 3 days in a C-class ward after an appendix operation. Total bill: $3,500.
- MediShield Life pays: ~$1,800 (approximate, after deductible)
- MediSave covers: remaining ~$1,000 (from your deductible + co-insurance)
- Cash out-of-pocket: ~$700
For a C-class stay, many Singaporeans find MediShield Life + MediSave covers most of the bill. Cash top-up is modest.
Scenario B — 5-Day B2 Ward + ISP (New 2026 Rider)
Same illness, but you upgrade to B2 ward. Total bill: $8,000.
- MediShield Life pays: ~$3,500
- ISP covers: ~$3,500 (less deductible)
- MediSave covers your deductible portion
- Cash co-payment: ~$1,000 (well within the $6,000 annual cap)
Scenario C — Private Hospital + ISP (New 2026 Rider)
Major surgery in a private hospital. Total bill: $28,000.
- MediShield Life pays: limited amount (low for private)
- ISP covers: the bulk of the bill above MediShield Life
- MediSave covers: your deductible (typically $3,000–$5,000 for private ward)
- Cash co-payment: capped at $6,000/year under new rider rules
Without an ISP, that $28,000 private hospital bill would leave you with a very large cash gap. An ISP with rider is essential if you want private hospital access with peace of mind.
For premium benchmarks by age, see our ISP premium by age guide.
5 Tips to Maximise Your MediSave for Hospitalisation
1. Always top up your MediSave before hospitalisation if possible. If you know you’re going in for an elective procedure, check your MediSave balance. The Basic Healthcare Sum cap is $79,000 in 2026. You can top up via CPF if your balance is low.
2. Understand your ISP’s deductible before you’re admitted. The deductible is what you pay before your ISP kicks in. From April 2026, new riders don’t cover this — MediSave usually does, but you need to have enough in your account.
3. Choose your ward class strategically. If you have an ISP covering Class A or private wards, use it — your premium already pays for that coverage. But if your ISP only covers B1, don’t choose a private room expecting full coverage.
4. Keep your ISP active even when healthy. Many Singaporeans cancel their ISP when premiums feel expensive. But as you age, you can’t re-apply without medical underwriting. Keep it going, especially into your 50s and 60s.
5. Review your ISP rider after April 2026. If you bought a rider before November 2025, your grandfathered terms may be better. But if you’re buying new, compare the lower-premium new riders against the out-of-pocket risk — for most people under 50, the new structure is cost-effective.
For tips on managing your overall MediSave strategically, see our full MediSave Singapore 2026 guide.
Frequently Asked Questions
How much MediSave can I use for a hospital stay?
Do I need to file a MediSave claim myself?
What happens if my MediSave balance isn't enough?
Can I use MediSave for a private hospital stay?
How did the April 2026 rider changes affect my MediSave use?
Can I use MediSave for day surgery?
What is the MediSave Basic Healthcare Sum (BHS) in 2026?
Ready to Review Your ISP?
Understanding your MediSave limits is step one. The next step is making sure your Integrated Shield Plan is the right fit — especially given the April 2026 rider changes.
Explore TKN’s guides: best ISPs in Singapore · MediSave AWL for ISP premiums · What is an ISP?
Not financial advice. Always verify current limits with CPF Board and MOH before making healthcare decisions.
Get Free Insurance Advice
Speak with a licensed insurance advisor. No obligation, no cost.
By submitting this form, you agree to our Privacy Policy.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.