Medisave AWL 2026: How Much Can You Use for ISP Premiums?
The Medisave Additional Withdrawal Limit (AWL) determines exactly how much of your Medisave you can use each year to pay for your Integrated Shield Plan (ISP) premium — by age bracket.
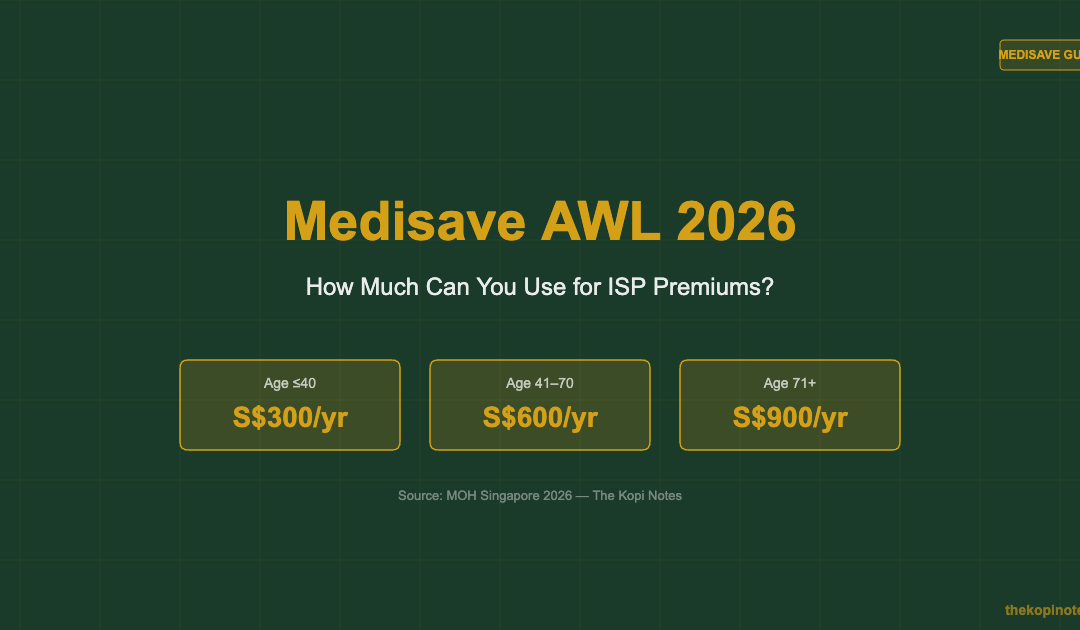
The Medisave Additional Withdrawal Limit (AWL) for ISP premiums in 2026 is S$300/year for policyholders aged 40 and below, S$600/year for those aged 41–70, and S$900/year for those aged 71 and above. Any ISP premium above your AWL must be paid in cash. Rider premiums are always 100% cash — Medisave cannot be used for riders at all.
Not financial advice. All figures are for educational reference only. Data verified as at 15 September 2026 unless noted.
- AWL is S$300/yr (age ≤40), S$600/yr (age 41–70), S$900/yr (age 71+) — set by MOH
- For most Singaporeans in their 30s–50s on Gold Max A, the AWL covers only a fraction of the annual premium — expect a significant cash shortfall
- Riders for ISPs are always paid 100% in cash — Medisave cannot be used at all for rider premiums
What is the Medisave AWL?
Your Medisave account holds money you cannot touch for most everyday spending. One approved use is paying for Integrated Shield Plan (ISP) premiums. But there is a cap — the Additional Withdrawal Limit (AWL).
MOH sets the AWL to make sure you do not drain your Medisave on private insurance premiums. The idea is to preserve enough Medisave for your future healthcare needs — especially hospitalisation and outpatient visits in old age.
The AWL is separate from the amount Medisave pays for the MediShield Life base premium. That base premium is covered in full from Medisave at any age. The AWL only caps the additional ISP component — the part your private insurer adds on top of MediShield Life. Read our MediShield Life benefits guide for a full breakdown of what the base plan covers.
AWL Table by Age Group 2026
Here are the official AWL limits for 2026, set by MOH. These apply to the private insurer’s portion of your ISP premium only — not the MediShield Life base premium.
| Age Band | Medisave AWL (per year) | Notes |
|---|---|---|
| 40 and below | S$300 | Lowest limit; ISP premiums in this group tend to be lower |
| 41 to 70 | S$600 | Mid-tier limit; premiums rise significantly from age 50 |
| 71 and above | S$900 | Highest limit; premiums can exceed S$10,000/yr for premium ISPs |
Source: MOH Singapore — Medisave Additional Withdrawal Limits, 2026.
Note: The AWL has not been raised in several years despite rising ISP premiums. This means Medisave covers a smaller proportion of your total ISP cost over time — especially for older policyholders on higher-tier plans.
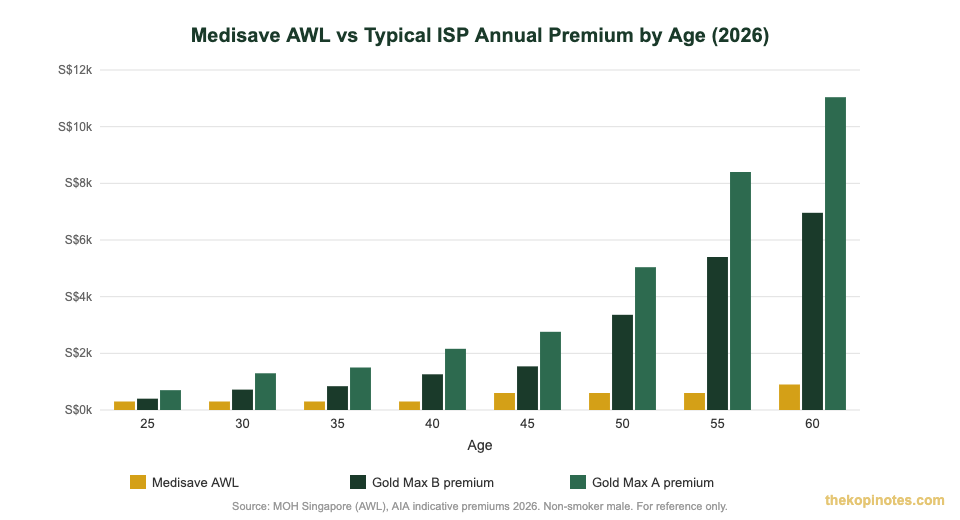
Source: MOH (AWL); AIA indicative premiums for non-smoker male, 2026. For illustrative purposes only.
MediShield Life vs ISP Component
Every ISP premium has two parts. You need to understand both to know what Medisave covers.
| Component | What It Covers | Paid From |
|---|---|---|
| MediShield Life base premium | Basic national hospitalisation coverage — B2/C ward public hospitals | 100% Medisave, no AWL cap |
| Private insurer ISP component | Upgraded coverage — A-ward or private hospital access | Medisave up to AWL, then cash |
| Rider premium | Reduces deductible and co-insurance at claim time | 100% cash — Medisave not allowed |
Source: MOH Singapore healthcare scheme rules, 2026.
CPF Board deducts the MediShield Life premium and up to the AWL from your Medisave automatically. The remaining balance — ISP component above AWL, plus the full rider premium — is charged in cash. See our CPF Medisave cap and ISP premiums guide for how the deduction flow works at different ages.
How Much Cash Do You Actually Pay?
Let us look at real examples using AIA HealthShield Gold Max (indicative 2026 premiums for non-smoker males).
For a 30-year-old on Gold Max A (~S$1,296/yr total ISP premium): The MediShield Life base (~S$165) is covered by Medisave first, then S$300 AWL covers the ISP component. Cash outlay is roughly S$831 — nearly two-thirds of the total premium.
For a 50-year-old on Gold Max B (~S$3,360/yr): Medisave covers the base premium (~S$530) plus S$600 AWL. Cash outlay is roughly S$2,230. At this age, the AWL barely makes a dent. For the detailed AIA HealthShield Gold Max A vs B comparison, see our dedicated guide.
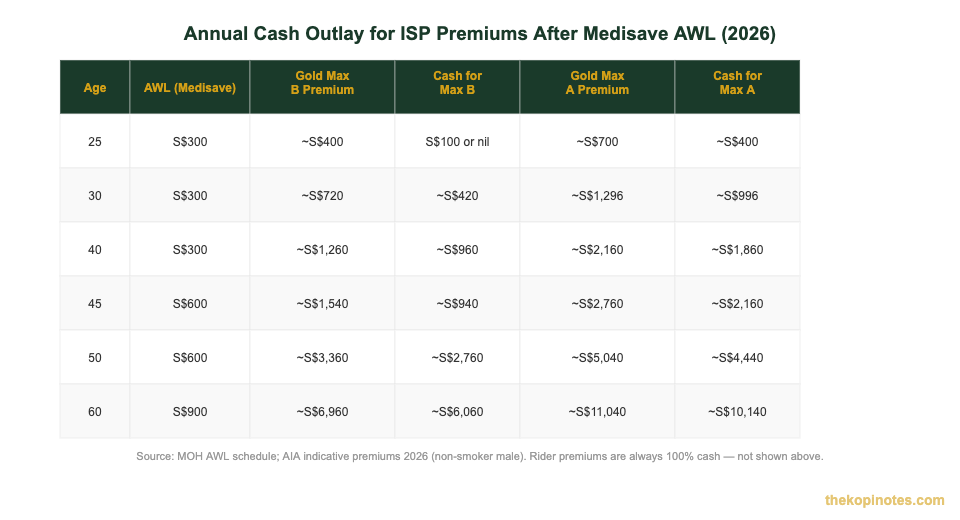
Source: MOH AWL schedule; AIA indicative premiums 2026, non-smoker male. Rider premiums excluded — always 100% cash.
The takeaway: if you are under 40 on a private-hospital ISP, expect to pay 60–80% of your ISP premium in cash. As you age, the absolute cash amount grows sharply — even though the AWL rises slightly at age 41.
Riders: Always 100% Cash
You cannot use Medisave to pay for ISP riders. Not even one dollar. Rider premiums are fully cash, every year. No exceptions.
A rider reduces your out-of-pocket costs when hospitalised — it absorbs most of the deductible and co-insurance. But you pay for that protection in cash. Rider premiums add S$600–S$4,000+ per year depending on your age and plan tier.
Strategies to Manage the Cash Gap
Since Medisave does not fully cover your ISP premium, you need to plan for the cash gap. Here are the main approaches Singaporeans use.
1. Choose the right ISP tier for your budget. Gold Max B premiums are 40–60% lower than Gold Max A at most ages. If you are comfortable with A-ward public hospital care, choosing Gold Max B frees up significant cash each year.
2. Consider stepping down as premiums rise. Some Singaporeans are on Gold Max A in their 30s but switch to Gold Max B when premiums spike in their 50s. You can downgrade at any time — though claims history may affect terms.
3. Build a healthcare cash reserve. Set aside a dedicated cash buffer for ISP premiums and rider payments. Many planners recommend keeping 1–2 years of combined ISP + rider premiums liquid at all times.
4. Let your savings earn more. If you are building that healthcare reserve, platforms like Endowus (referral code 2V343) or Syfe (referral code SRPRFFFCD) let your cash earn returns while it waits to be deployed. Use our Singapore retirement calculator to model your healthcare reserve needs alongside retirement goals.
Who Benefits Most from the AWL?
The AWL gives the most meaningful relief in two scenarios.
Young policyholders on mid-tier ISPs. At age 30 on Gold Max B (~S$720/yr), the S$300 AWL covers a meaningful portion of the ISP component. Medisave does real work here. Cash outlay is manageable — often under S$500/yr.
Elderly policyholders with large Medisave balances. At 71+, the S$900 AWL is the highest. If your Medisave balance is topped up (the 2026 BHS is S$79,000), you can sustain the AWL deduction for many years. See our Medisave cap 2026 and BHS guide for how the BHS interacts with ISP withdrawals.
The AWL gives the least relief to working-age Singaporeans (40–65) on premium ISPs. In this group, premiums are high and the AWL is capped at S$600 — often covering less than 15% of the total annual cost for Gold Max A.
Disclaimer: This article is for educational purposes only and does not constitute financial or insurance advice. All premium figures are indicative as at September 2026 and subject to change. Consult a licensed financial adviser before making insurance decisions.
Frequently Asked Questions
What is the Medisave Additional Withdrawal Limit (AWL) for ISP premiums in 2026?
The Medisave AWL for Integrated Shield Plan premiums in 2026 is S$300/year for policyholders aged 40 and below, S$600/year for those aged 41–70, and S$900/year for those aged 71 and above. These limits apply only to the private insurer’s component of your ISP premium. The MediShield Life base premium is covered separately from Medisave in full, with no withdrawal cap.
Can I use Medisave to pay for my ISP rider?
No. Rider premiums must be paid 100% in cash. You cannot use Medisave for any part of a rider premium, regardless of your Medisave balance. The AWL applies only to the base ISP premium (above MediShield Life) — riders are completely excluded from Medisave payment.
What if my ISP premium is lower than the AWL?
If the private insurer’s component of your ISP premium is lower than your AWL, Medisave covers the actual amount due. You do not need to use the full AWL. For example, if you are 30 years old and your ISP component is S$240/year, Medisave covers all S$240 — you pay nothing in cash for the base ISP. You still pay the full rider premium in cash if you have a rider.
How do I check how much Medisave is deducted for my ISP?
Your insurer’s annual premium notice will break down the MediShield Life component, the private ISP component, and the rider premium separately. CPF Board deducts the MediShield Life premium and up to the AWL from your Medisave automatically. The remaining balance is charged as cash. You can also check your CPF statement (via CPF online services) to see the exact Medisave deductions each year.
Has the AWL changed recently or will it change in 2026?
The AWL has remained at S$300/S$600/S$900 for several years. As at September 2026, MOH has not announced any revision to the AWL. MOH reviews the AWL periodically and has raised it in the past when premiums have risen substantially. Check MOH’s official website for the latest updates. This article will be updated if there is any change.
Does the AWL apply to all ISPs in Singapore or just AIA?
The Medisave AWL applies uniformly to all seven approved ISPs in Singapore — AIA HealthShield Gold Max, Great Eastern Supreme Health, NTUC Enhanced IncomeShield, Prudential PruShield, Raffles Shield, Singlife Shield Plan, and Aviva MyShield. The AWL is the same S$300/S$600/S$900 structure regardless of which insurer you are with or which plan tier you choose.
Can I hold two ISPs and use two AWLs?
No. You cannot hold two active ISPs simultaneously in Singapore. Each person may only have one ISP at a time. The AWL is a per-person annual limit. If you switch from one ISP to another, the same single AWL applies to your new plan.
Plan Smarter. Save More.
Once your ISP is sorted, put your cash savings to work with platforms that reward you.
Get Free Insurance Advice
Speak with a licensed insurance advisor. No obligation, no cost.
By submitting this form, you agree to our Privacy Policy.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.