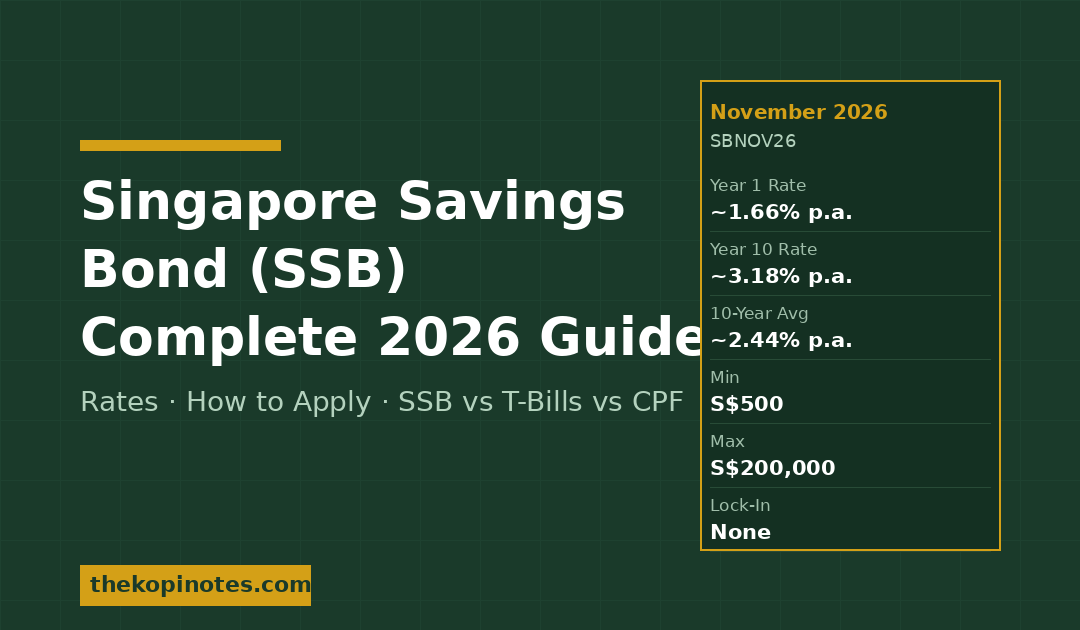
- What it is: A government-backed, retail savings bond issued monthly by MAS — zero credit risk, backed by Singapore’s AAA balance sheet.
- Interest structure: Step-up rates that rise each year you hold; November 2026 projects ~1.66% in Year 1 stepping to ~3.18% in Year 10 (~2.44% avg over 10 years).
- Minimum / maximum: S$500 minimum; S$200,000 per person across all SSB holdings.
- Lock-in: None. Redeem in any month with one month’s notice and no penalty.
- Apply via: DBS/POSB, OCBC or UOB internet banking, mobile app or ATM — or via CPFIS-OA or SRS account.
- Best for: Emergency fund overflow, SRS cash deployment, conservative retirement savings, CPFIS-OA holders with idle cash.
This is general information, not financial advice. Always verify current SSB rates at mas.gov.sg before applying.
What Is the Singapore Savings Bond?
The Singapore Savings Bond (SSB) is a special class of Singapore Government Securities (SGS) designed specifically for retail investors. Unlike regular SGS bonds, which are sold primarily to institutional investors and require large minimum amounts, the SSB is accessible from just S$500 and is available to any Singaporean citizen or permanent resident aged 18 and above.
Each month, the Monetary Authority of Singapore (MAS) issues a new SSB tranche with its own set of interest rates. These rates are anchored to Singapore Government Securities yields — a benchmark that reflects Singapore’s strong fiscal position and AAA credit rating. Because the Singapore government stands behind these bonds, they carry effectively zero default risk.
The SSB was introduced in 2015 and has become one of the most widely used instruments for conservative savers, especially those looking to earn a return on emergency funds, SRS balances, and retirement nest eggs without tying their money up for years.
How Is the SSB Different from Other Singapore Government Bonds?
SSBs differ from regular SGS bonds in three important ways. First, they feature a step-up interest structure — rates rise each year, rewarding those who hold longer rather than paying a flat coupon throughout. Second, they are fully redeemable at any time with no penalty, unlike fixed deposits or T-bills that lock your money until maturity. Third, they are accessible to retail investors directly, without going through a broker.
This combination of safety, flexibility, and improving returns over time makes the SSB unique among government instruments in Singapore.
How SSB Interest Works: The Step-Up Structure Explained
The defining feature of the SSB is its step-up interest rate. Instead of paying a single fixed rate over 10 years, the SSB pays a rate that increases year by year. Year 1 carries the lowest rate; Year 10 carries the highest. This structure serves two purposes: it encourages long-term holding while still allowing early exit without penalty.
Interest on the SSB accrues daily and is credited to your linked bank account every six months — on 1 February and 1 August each year. This means even if you only hold for one year, you still receive two semi-annual interest payments before you redeem.
The rates you see quoted as “Year 1,” “Year 2,” and so on represent the annualised rate you earn for that specific holding year. If you exit after Year 3, for example, you will have earned the Year 1 rate during Year 1, the Year 2 rate during Year 2, and the Year 3 rate during Year 3. The “10-year average return” quoted by MAS represents the simple average of all 10 annual rates — it is only achievable if you hold for the full decade.
Each monthly issuance has its own rate schedule, announced by MAS on the first business day of the application month. Rates cannot be locked for future months — if you want November 2026 rates, you must apply in October 2026.
Singapore Savings Bond Rates 2026: November 2026 (SBNOV26)
The November 2026 SSB (SBNOV26) is projected to offer a 10-year average return of approximately 2.44% per annum — the highest projected average since early 2025 and a meaningful step up from October 2026’s 2.32%. The improvement is driven by the US Federal Reserve’s 25-basis-point rate hike in September 2026 to 3.75–4.00%, which has filtered into Singapore Government Securities yields.
Note: The rates below are projections based on SGS yields as at 27 September 2026. Official rates will be confirmed by MAS on 1 October 2026. Apply between 1 October and 25 October 2026 for the November 2026 issue.
| Year | Annual Rate (Projected) | Effective Return If You Exit Here |
|---|---|---|
| Year 1 | ~1.66% | 1.66% p.a. |
| Year 2 | ~1.83% | 1.75% p.a. avg |
| Year 3 | ~2.00% | 1.83% p.a. avg |
| Year 4 | ~2.15% | 1.91% p.a. avg |
| Year 5 | ~2.28% | 1.98% p.a. avg |
| Year 6 | ~2.50% | 2.07% p.a. avg |
| Year 7 | ~2.70% | 2.16% p.a. avg |
| Year 8 | ~2.88% | 2.25% p.a. avg |
| Year 9 | ~3.02% | 2.33% p.a. avg |
| Year 10 | ~3.18% | ~2.44% p.a. avg |
Source: Projections based on SGS yields, ilovessb.com methodology, as at 27 September 2026. Subject to MAS confirmation.
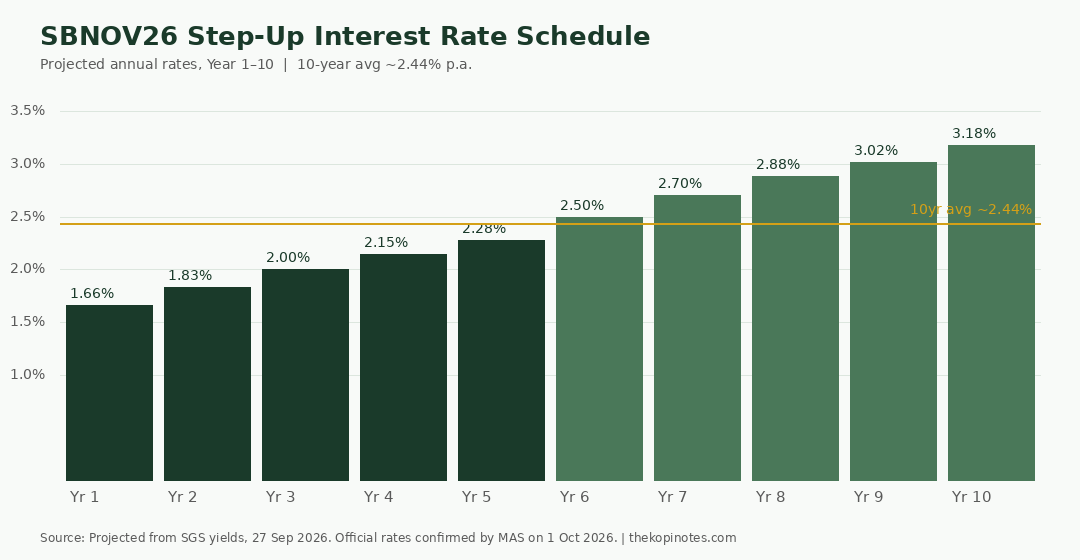
SSB rates change every month in line with SGS yield movements. October 2026’s average was 2.32% — November marks the second consecutive month of improvement. To track projected rates for upcoming months, bookmark our monthly SSB rate updates or use the SSB interest calculator to model returns at your preferred holding period.
Who Can Apply for the SSB?
To apply for an SSB, you must:
- Be a Singapore citizen or permanent resident (PRs are eligible).
- Be aged 18 or above (minors cannot apply directly).
- Hold a bank account with DBS/POSB, OCBC or UOB.
- Have a Central Depository (CDP) account linked to your bank account — or be applying via a CPFIS-OA or SRS account.
CDP accounts are free to open via the SGX website and take about 3–5 working days to process. Once your CDP account is linked to your bank, you can apply for SSBs immediately.
Foreigners, companies, trusts and joint account holders cannot apply for SSBs in the standard channel, though they may have access through specific fund structures.
How to Apply for the SSB: Step-by-Step
Via Internet Banking or Mobile App
- Log in to your DBS/POSB, OCBC or UOB internet banking or mobile app.
- Navigate to Investments → Singapore Savings Bond (or search “SSB” within the app).
- Enter the amount you wish to invest (minimum S$500, in S$500 increments).
- Confirm your CDP account number is correctly linked.
- Review and submit your application before the deadline (applications close at 9pm on the 4th last business day of the application month).
Via ATM
DBS/POSB, OCBC and UOB ATMs also accept SSB applications under the “Investments” or “Government Securities” menu. The process is similar: enter your desired amount, confirm your CDP link, and submit.
Via CPFIS-OA
CPF members can invest SSB using Ordinary Account funds under the CPF Investment Scheme (CPFIS-OA). This is subject to CPFIS eligibility and the investible CPF-OA balance (which excludes the first S$20,000 in OA). Applications via CPFIS-OA go through your CPFIS-approved bank — DBS, OCBC, or UOB. The S$200,000 cap applies across all SSB holdings including CPFIS-OA holdings. For more on using CPF strategically for retirement, see our CPF Retirement Sum guide.
Via SRS Account
Supplementary Retirement Scheme (SRS) account holders can also invest their SRS balance in SSBs. SRS contributions reduce your taxable income (up to S$15,300 per year for Singaporeans and PRs), and investing that SRS cash in SSBs keeps it working productively while the funds await retirement withdrawal. For SRS tax savings calculations, see our SRS tax relief guide.
Worked Example: Investing S$20,000 in SBNOV26
Suppose you invest S$20,000 in the November 2026 SSB (SBNOV26) using the projected rates above. The table below shows what you receive at different exit points — with interest credited every six months.
| Exit After | Total Interest Earned | Total Received | Effective Avg Rate |
|---|---|---|---|
| 1 year | ~S$332 | ~S$20,332 | 1.66% p.a. |
| 2 years | ~S$699 | ~S$20,699 | 1.75% p.a. avg |
| 3 years | ~S$1,099 | ~S$21,099 | 1.83% p.a. avg |
| 5 years | ~S$1,980 | ~S$21,980 | 1.98% p.a. avg |
| 10 years | ~S$4,880 | ~S$24,880 | ~2.44% p.a. avg |
Illustration only. Based on projected SBNOV26 rates; actual rates confirmed by MAS on 1 October 2026. Interest credited semi-annually.
The longer you hold, the higher your effective return. The trade-off: Year 1 at ~1.66% is meaningfully below the T-bill rate of 1.92% (as at September 2026). If you are highly confident you will need the money within 12 months, a T-bill or a short fixed deposit may serve better. For holding periods of two years or more, SBNOV26’s step-up structure pulls ahead. Use the SSB interest calculator to model your own amounts and exit dates.
SSB vs T-Bills, Fixed Deposits and CPF: Side-by-Side
| Instrument | Rate (Sep/Oct 2026) | Lock-In | Key Trade-Off |
|---|---|---|---|
| SSB Nov 2026 (10-yr avg) | ~2.44% | None | Lower Year 1; best long-term among risk-free options |
| SSB Nov 2026 (Year 1) | ~1.66% | None | Flexible; below T-bill for short-term |
| 6-Month T-Bill (Sep 2026) | 1.92% | 6 months | Better short-term; locked until maturity |
| Best 6-Month Fixed Deposit | ~2.10% | 3–6 months | Good short-term; SDIC-insured; bank-dependent |
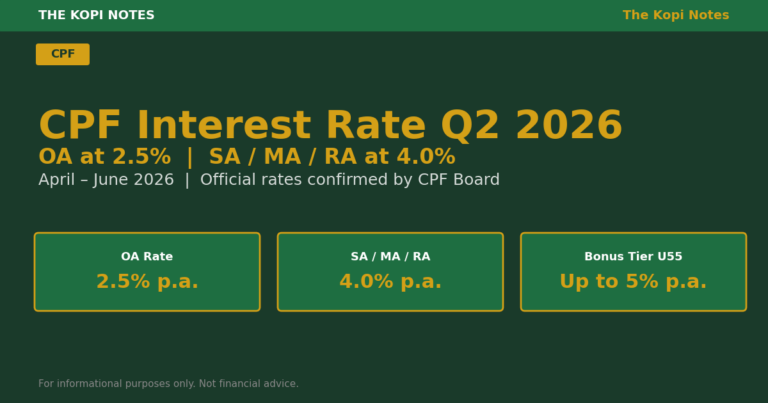
| CPF Ordinary Account (OA) | 2.5% | CPF withdrawal age | Stable rate; accessible only at 55 or for housing |
| CPF SA / MA / RA | 4.0% (floor to Dec 2027) | Retirement age | Best guaranteed rate; most restricted |
| SSB (SRS cash) | Up to ~2.44% avg | None | Tax-advantaged wrapper; best for SRS idle cash |
Rates as at September/October 2026. Verify current figures at mas.gov.sg, cpf.gov.sg and individual bank websites. This is not financial advice.
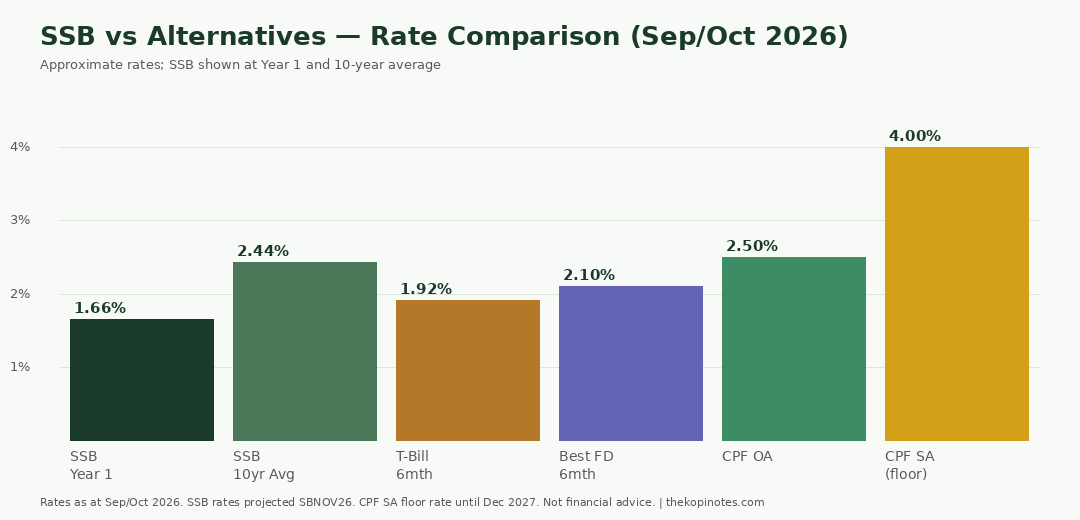
The SSB is not the highest-yielding safe instrument — CPF SA’s 4.0% floor dominates for funds already in CPF. But for money sitting outside CPF (including SRS), the SSB offers a compelling combination: government-backed safety, no lock-in, and rates that beat T-bills over any holding period beyond two years at current rate levels. For a full comparison including savings plans and endowment policies, see our savings plan vs SSB vs T-bill guide and endowment vs SSB comparison.
How SSB Redemption Works
Redeeming your SSB is as straightforward as applying. Log in to your bank’s internet banking or mobile app, select your SSB holding, and submit a redemption request by the 25th of any month (or the 4th last business day if the 25th falls on a weekend or holiday). Your principal and any accrued interest will be returned to your bank account by the 2nd business day of the following month.
There are no penalties, no exit fees, and no loss of previously earned interest. The only cost is the one-month delay between your redemption request and receipt of funds. You can also redeem a partial amount — for example, redeem S$5,000 of a S$20,000 holding while keeping the remaining S$15,000 invested.
If you submit a redemption in October (for example), your funds arrive in early November. You will still have earned interest up to the last semi-annual payment before your exit.
Important Limits and Rules
- S$200,000 per person cap: This is a cumulative cap across all SSB tranches held simultaneously (not total cumulative purchases). If you hold S$200,000 and redeem S$50,000, you can reinvest up to S$50,000 again.
- S$500 minimum, S$500 increments: Applications must be in multiples of S$500.
- One CDP account per application: Each application is linked to one CDP account. CPFIS-OA and SRS holdings are tracked separately.
- Allotment: If total applications exceed the issuance size, MAS allots pro-rata. You may receive less than you applied for. Unallotted amounts are returned to your bank by the issue date.
- Issue date: The SSB is issued on the 1st business day of the month after the application month (e.g., November 2026 SSB is issued 1 November 2026; apply in October 2026).
Risks and Limitations of the SSB
The SSB is as safe as a Singapore investment can be — the government itself backs it. But “safe” does not mean “optimal for every situation.” Consider these trade-offs:
Rate risk (future months, not your current holding): The rate you lock in today only applies to the current tranche. Future issuances may be higher or lower depending on SGS yield movements. Unlike a fixed deposit, you cannot lock the current SSB rate for future contributions.
Low Year 1 return: At ~1.66% for Year 1, SBNOV26 earns less than the September 2026 T-bill (1.92%) or the best 6-month fixed deposits (~2.10%) for truly short-term parking. If you are confident you need the money within 12 months, a T-bill or FD delivers more in that window.
CPF SA / MA opportunity cost: Funds already inside CPF earn 4.0% in SA (floor rate guaranteed to December 2027). Money that can stay in CPF earns far more than SSB. SSB is most relevant for funds outside CPF.
No CPFIS-SA use: SSB cannot be purchased with CPF Special Account funds — only Ordinary Account under CPFIS.
No joint holdings: SSBs are strictly individual instruments. Couples investing together must hold separate tranches.
Singapore Savings Bond FAQs
Is the Singapore Savings Bond safe? Can I lose money?
What happens if I need my money urgently?
Can I apply for SSB with my CPF money?
What is the maximum amount I can invest in SSBs?
How does SSB compare to T-bills for short-term savings?
When exactly is SSB interest paid?
Can I buy SSB in my child's name?
What happens to my SSB if I pass away?
Related Tools & Guides
- SSB Interest Calculator — Model your SSB returns at any holding period and amount
- SSB November 2026 Rates — Current month rates, analysis and application guide
- Savings Plan vs SSB vs T-Bill 2026 — Which parking instrument wins?
- Endowment Plan vs SSB — When guaranteed plans beat SSB
- CPF Retirement Sum Guide — Understanding your CPF FRS, BRS and ERS
- FIRE Singapore: The Number — How much do you need to retire early in Singapore?
This article is for general information only. It is not financial advice. Please consult a licensed financial adviser before making investment decisions.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.