Singapore Savings Plans vs T-Bills vs SSB 2026: Where Should Your Cash Go Now?
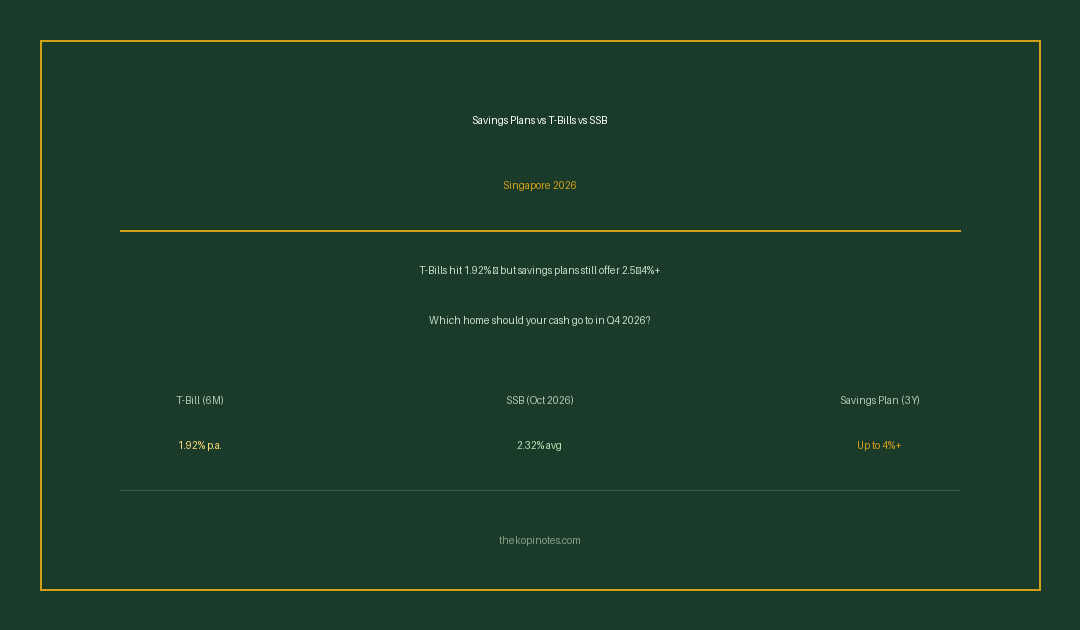
T-bill yields just hit 1.92% — the highest of 2026 — yet savings plans are offering 2.5–4%+ guaranteed returns for those willing to lock up funds for 2–3 years. SSBs sit in the middle with full flexibility. Here is a straight comparison so you can make a clear decision.
Data verified as at 28 September 2026. Rates sourced from MAS auction results, MAS SSB announcements, and publicly available insurer product sheets. Specific plan availability and rates should be confirmed directly with insurers before committing. This article is for general information only and does not constitute financial advice. Please consult a licensed financial adviser for personalised recommendations.
The Q4 2026 Rate Landscape at a Glance
The September 17 Federal Reserve rate hike — a 25-basis-point increase to 3.75–4.00% — sent Singapore’s 6-month T-bill yield jumping to 1.92% per annum at the 24 September 2026 auction. That is the highest T-bill yield of 2026, up 22 basis points from 1.70% just two weeks before.
Meanwhile, the Singapore Savings Bond for October 2026 carries a Year 1 rate of 1.65% and a 10-year average rate of 2.32% — its strongest tranche in 14 months. And selected short-term endowment and savings plans from major insurers continue to offer guaranteed returns of 2.5–4%+ per annum for 2–3 year lock-up periods.
So which is actually best for you? The answer depends on three things: how long you can park the money, how much you are investing, and whether you need the option to exit early. This guide breaks it down.
For a deeper look at how savings plans stack up within the endowment space, see our guide on single premium vs regular premium savings plans and our endowment plan vs T-bill comparison.
T-Bills: Best for Short-Term Parking Without Lock-In
Singapore 6-month Treasury bills (T-bills) are issued by the Singapore government through MAS and are considered one of the safest instruments available. There is no counterparty risk, and returns are fully capital-guaranteed.
At the 24 September 2026 auction, the cut-off yield for the 6-month T-bill came in at 1.92% per annum, the highest level recorded in 2026. Applications totalled S$15.8 billion against an issue size of S$5.8 billion, meaning competition was high but the rate still cleared above where most CPF-OA investors would find it worthwhile.
Key characteristics:
- Minimum investment: S$1,000 (no maximum)
- Tenor: 6 months (also 1-year T-bills issued less frequently)
- Guaranteed cut-off rate: 1.92% p.a. (Sep 24 2026 auction)
- Early exit: Not possible — you must hold to maturity or sell on secondary market at a discount
- CPF-OA eligible: Yes
- SRS eligible: Yes
The main drawback of T-bills is that you must roll them over every 6 months. If yields fall in the next auction — as they did from 1.70% to 1.92% (they rose in this case, but the direction can change) — your reinvestment rate is uncertain. For those who want to set and forget for 2–3 years, a savings plan or SSB offers better certainty.
For a detailed guide on applying and what to expect, see our SSB October 2026 article and the full savings plan rankings guide.
SSBs: Best for Flexibility and Step-Up Returns
The Singapore Savings Bond is a unique instrument from MAS that combines capital safety with step-up interest rates — you earn more each year you hold, and you can redeem in any given month with no penalty, getting back your full capital plus any accrued interest.
The October 2026 SSB tranche offers:
- Year 1 rate: 1.65% per annum
- Year 2: approximately 1.88%
- Year 5: approximately 2.45%
- Year 10: approximately 3.01%
- 10-year average rate: 2.32% per annum
This means if you hold the SSB for 10 years, you earn an average of 2.32% per annum — significantly better than the T-bill’s 1.92% for those with a longer time horizon. But if you only hold for one year, you earn just 1.65% — below the T-bill rate.
Key characteristics:
- Minimum investment: S$500
- Maximum investment: S$200,000 lifetime (across all SSB tranches)
- Lock-in: None — redeem monthly with 1 business day notice
- CPF-OA eligible: No (SRS eligible: Yes)
- Guaranteed by Singapore government: Yes
The SSB’s flexibility makes it an ideal emergency fund vehicle or a complement to savings plans. You can park your money here while you evaluate longer-term options, then redeem and move to a savings plan when you find a better rate.
Savings Plans: Best for Higher Guaranteed Returns With a Lock-Up
A savings plan (or short-term endowment plan) is an insurance product that locks in your premium for a fixed period — typically 2–5 years — and pays a guaranteed lump sum at maturity. Unlike T-bills or SSBs, most savings plans also include a small death benefit, which means they qualify for life insurance regulatory oversight and SDIC protection of up to S$100,000.
As of late September 2026, here is a snapshot of notable plans in the market:
- AIA Wealth Savvy (latest tranche): approximately 3.00% per annum guaranteed for a 3-year term. Minimum S$5,000 per transaction.
- Etiqa Tiq 3-Year Endowment: approximately 3.5–3.6% per annum guaranteed. Tranches have filled quickly — check availability directly.
- Manulife Goal (current tranche): up to 1.60% per annum for a 2-year term. A lower rate for those who prefer a shorter lock-up.
- Market range for 3-year plans: broadly 2.5% to 4%+ per annum depending on insurer, tranche, and whether you apply online or through an FA.
Note: Plan availability and rates change frequently. Always verify directly with the insurer or a licensed financial adviser before committing. The above figures are indicative as at 28 September 2026.
Key characteristics:
- Minimum investment: typically S$5,000–S$10,000 per policy
- Tenor: 2–5 years (most short-term plans are 2–3 years)
- Early exit: Capital loss risk — surrender value is typically less than premiums paid in early years
- SDIC protection: Yes, up to S$100,000 per insurer
- CPF-OA eligible: Generally no (CPF-SRS eligible: depends on plan)
The key trade-off with savings plans is liquidity. If you need the money before maturity, you will likely get back less than you put in. Only commit funds you are certain you will not need for the full tenure.
For a broader view of the short-term endowment market, see our short-term endowment plan guide.
Side-by-Side Comparison: T-Bill vs SSB vs Savings Plan
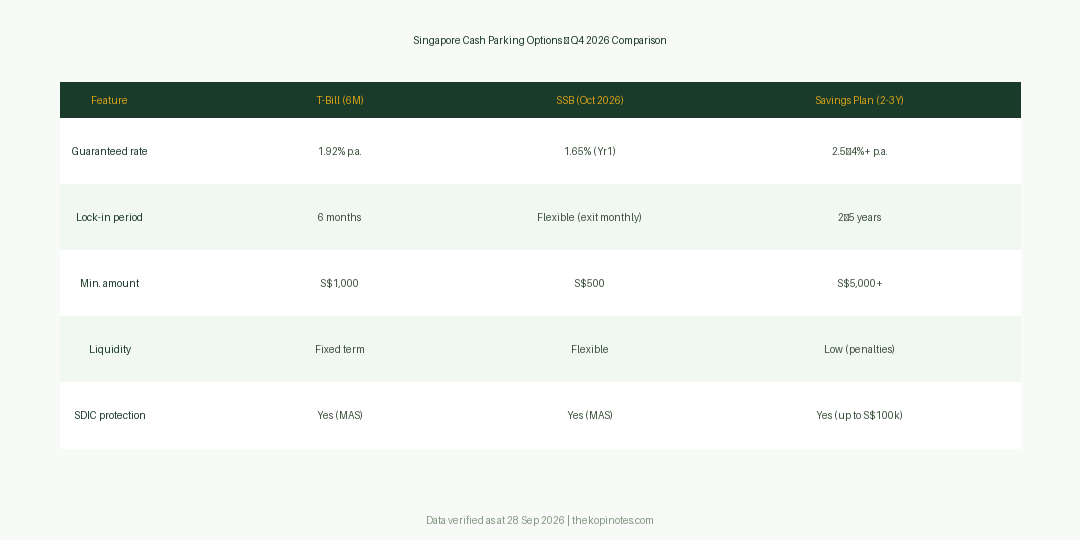
| Feature | T-Bill (6M) | SSB (Oct 2026) | Savings Plan (2-3Y) |
|---|---|---|---|
| Current rate | 1.92% p.a. (Sep 24) | 1.65% Yr1; 2.32% avg | ~2.5–4%+ guaranteed |
| Lock-in | 6 months fixed | None (monthly exit) | 2–5 years (penalty) |
| Min. amount | S$1,000 | S$500 | S$5,000–S$10,000+ |
| Max. amount | No cap | S$200,000 lifetime | Varies by plan/insurer |
| SDIC/Govt backed | Full (govt guarantee) | Full (govt guarantee) | S$100k per insurer |
| CPF-OA eligible | Yes | No | Generally no |
| SRS eligible | Yes | Yes | Selected plans only |
| Best for | Short-term, no lock-in needed, CPF-OA | Flexibility, long-term step-up, small amounts | Higher returns, certain funds, 2-3yr horizon |
Who Should Choose Each Option
Choose a T-bill if:
- You want the money back in 6 months and are comfortable rolling over
- You want to invest CPF-OA funds (T-bills are CPF-eligible)
- You have a large lump sum (above S$200,000, which exceeds the SSB lifetime cap)
- You are comfortable with the reinvestment risk at each roll-over
Choose an SSB if:
- You want maximum flexibility — no penalty for early exit
- You are investing a smaller amount (as low as S$500)
- You are willing to hold for 5–10 years to capture the step-up structure
- You want a government-guaranteed instrument but cannot commit to a fixed tenor
Choose a savings plan if:
- You can confidently park the funds for 2–3 years without needing early access
- You want to lock in a guaranteed rate above what T-bills or SSBs offer short-term
- You are starting with at least S$5,000 and want insurer-backed capital protection (SDIC)
- You want to combine modest life insurance coverage with your savings
A practical approach for S$50,000: Many Singapore investors split their allocation — keeping 20–30% in an SSB or high-yield savings account for emergencies, and deploying the remaining 70–80% into a 2–3 year savings plan to capture the higher guaranteed rate. This balances liquidity with return optimisation.
For more on comparing investment options for different goals, see our Singapore savings plans ranked guide.
Frequently Asked Questions: Savings Plans vs T-Bills vs SSB Singapore 2026
Is a savings plan better than a T-bill in Singapore right now?
Can I withdraw from an SSB at any time?
Are savings plans in Singapore covered by SDIC?
What happens if I surrender a savings plan early?
Can I use CPF to buy savings plans or SSBs?
What is the SSB October 2026 rate?
What is the minimum amount to invest in a savings plan in Singapore?
Ready to Invest Your Cash Wisely?
If you are comparing savings plans alongside broader investment options like ETFs or managed portfolios, two platforms worth exploring are Endowus (referral code 2V343) and Syfe (referral code SRPRFFFCD). Both offer access to low-cost funds and fixed income portfolios that complement your cash management strategy.
For a broader comparison of where to park your money in Singapore, read our 7 types of savings plans ranked. To understand the difference between endowment tenors, see single vs regular premium savings plans.
This article is for general information only. Rates are indicative as at 28 September 2026 and subject to change. The Kopi Notes is not a licensed financial adviser. Please consult a qualified professional before making any financial decisions.
Get Free Insurance Advice
Speak with a licensed insurance advisor. No obligation, no cost.
By submitting this form, you agree to our Privacy Policy.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.