TribeCar + MariBank + Trust Bank + GXS + IBKR: The Triple-SDIC Cash Ladder (2026)
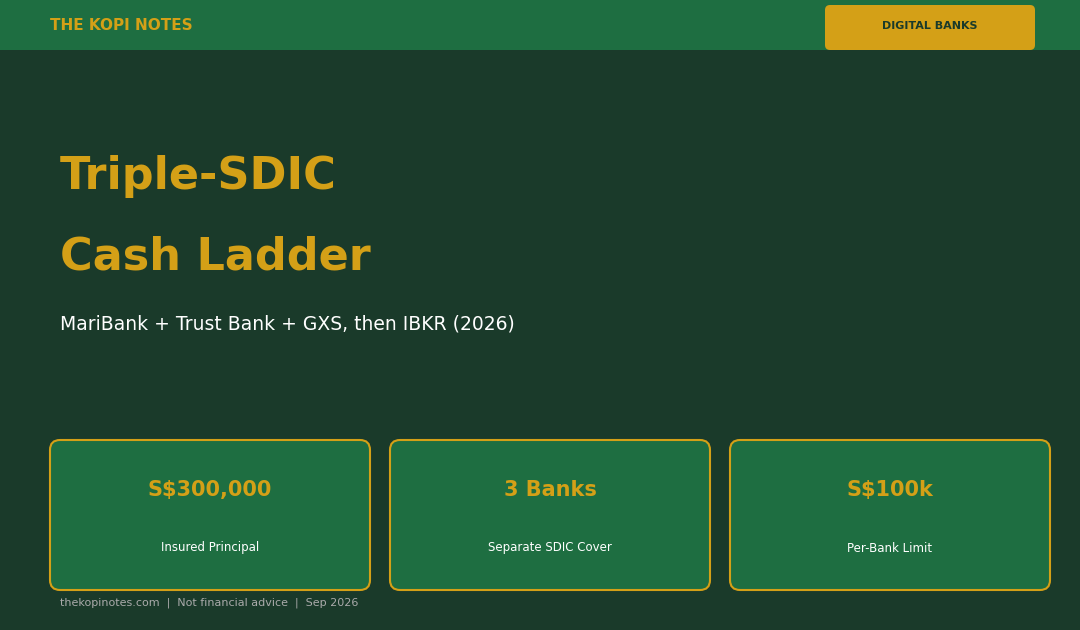
SDIC’s S$100,000 cover resets at every separate bank. Here’s the order to fund three insured accounts for S$300,000 of protection before a single dollar goes uninsured.
Not financial advice. Rates and promotions below are as at 27 September 2026 — always check each bank’s website before moving money.
SDIC insurance covers Singapore bank deposits up to S$100,000, but that cap resets at every separate bank. Skip car ownership with TribeCar, and the S$400–S$600 a month you free up can fill three separately insured accounts — at MariBank, Trust Bank, and GXS — for S$300,000 of government-backed protection before a single dollar needs to sit anywhere uninsured.
This guide sets out the order to fund them in, what each one actually pays once you strip out the marketing headline, and where the money goes once all three are full.
Table of Contents
Contents — Click to expand
Why S$100,000 x 3 Isn’t a Loophole
SDIC’s S$100,000 cap applies per depositor, per Scheme member. It doesn’t apply once across your entire net worth. MariBank Pte Ltd, Trust Bank Singapore Limited, and GXS Bank Pte Ltd are three separately licensed banks, so each carries its own S$100,000 of cover.
Trust Bank runs on a partnership with Standard Chartered, but it’s a separate legal entity and a separate SDIC Scheme member. A Trust Bank balance doesn’t share a cap with a Standard Chartered account, and it doesn’t reduce the cover you get at MariBank or GXS either.
Tier 1: MariBank, the First S$100,000
MariBank pays 0.88% p.a. on any balance, with no minimum deposit and no salary-crediting requirement. New members can stack a 1.60% p.a. bonus for the first 30 days, pushing the short-term rate toward 2.88% p.a., but that bonus expires. Plan around the 0.88% base, not the promo.
Route your freed-up TribeCar savings here first. It’s the simplest of the three accounts to open and carries no lock-in, so there’s no reason to delay starting the ladder.
Tier 2: Trust Bank, the Second S$100,000
Trust Bank markets up to 2.40% p.a., but that headline needs a large invested balance or heavy card spend most savers won’t hit every month. A realistic Flex plan — three achievable scoops, salary credit, a few card transactions, PayNow activity — lands closer to 0.85% p.a. for union members and 0.75% p.a. for everyone else.
Once MariBank’s S$100,000 is full, route the next tranche of savings to Trust Bank.
Tier 3: GXS, the Third S$100,000
GXS Boost Pocket pays up to 1.75% p.a. on a 12-month lock-in, with no conditions attached. A time-limited promotion running through 30 September 2026 pushes a 4-month Boost Pocket to 3.20% p.a., but only if it’s paired with a GXS Invest product. Weigh that trade-off before the window closes in three days.
This is your third and final S$100,000 of SDIC cover. Once it’s funded, all S$300,000 of freed-up savings sits behind government-backed insurance.
Beyond S$300,000: IBKR, Uninsured by Design
Once all three banks are full, the next dollar has nowhere insured left to go. IBKR isn’t a bank. It’s a capital markets services licence holder regulated by MAS, and client cash sits in segregated trust accounts rather than an SDIC-covered deposit.
IBKR also pays 0% interest on SGD cash until your account value passes roughly S$14,000, with the rate climbing further as your balance approaches S$100,000. Money that lands here should be earmarked for investing, not treated as a fourth savings account.
The Full Ladder at a Glance
| Tier | Platform | SDIC Status | Rate | Cap |
|---|---|---|---|---|
| 1 | MariBank | Insured to S$100,000 | 0.88% p.a. base (up to 2.88% p.a., first 30 days) | S$100,000 |
| 2 | Trust Bank | Insured to S$100,000 | ~0.85%/0.75% p.a. achievable (up to 2.40% p.a. headline) | S$100,000 |
| 3 | GXS | Insured to S$100,000 | Up to 1.75% p.a. (up to 3.20% p.a. promo to 30 Sep 2026) | S$100,000 |
| Overflow | IBKR | Not SDIC-insured (MAS-regulated, segregated) | 0% below ~S$14,000; rises toward NAV S$100,000 | Uncapped |
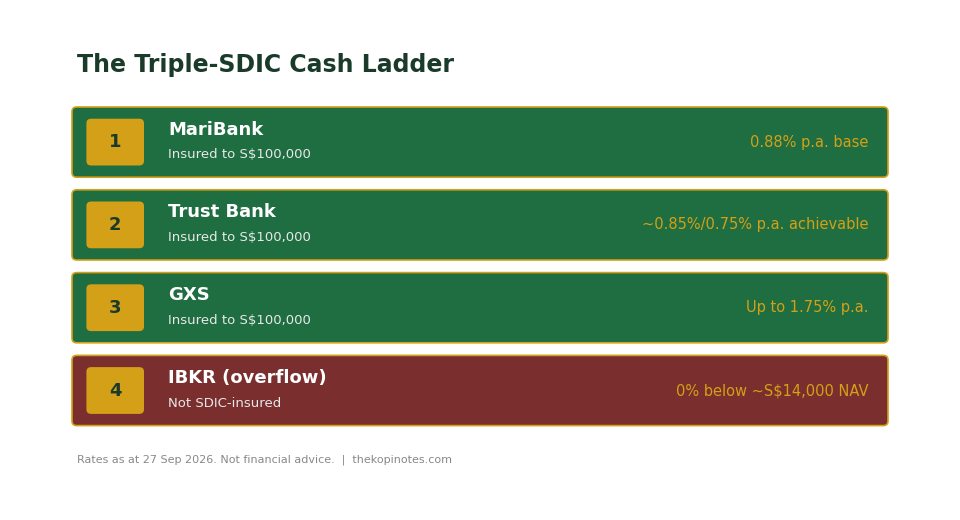
Rates as at 27 September 2026. Promotional rates are time-limited — check each platform before relying on them.
The Mistake This Fixes
Many savers assume S$100,000 is their total SDIC ceiling and stop opening new accounts once they hit it. It isn’t a personal ceiling. It’s a per-bank one.
Someone with S$300,000 sitting entirely in one bank has S$200,000 of it unprotected if that bank fails. The same S$300,000 split three ways, as above, is fully covered.
Who This Ladder Suits
This ladder suits savers who want their principal fully insured before they think about yield, not those chasing the single highest headline rate. Opening all three banks takes about 20 minutes total with Singpass MyInfo if you don’t already hold them.
If S$300,000 is far off, start with MariBank alone. It’s the account with no minimum and no lock-in. Add the other two as your balance grows, and only look at IBKR once all three are full.
For a related read on protecting savings by risk type rather than by bank, see our SDIC insurance barbell strategy. For how these same three banks compare on account-opening speed, see our KYC and account-activation comparison. If your CPF and SRS accounts still have room, our CPF investment guide and a look at Singapore Savings Bonds cover two more ways to keep principal government-backed. Our retirement calculator can help you work out how much of this S$300,000 you actually need liquid.
Get the Referral Codes
Current sign-up codes and bonuses for every platform in this ladder:
Frequently Asked Questions
Does SDIC really insure S$100,000 per bank, not per person?
Yes. SDIC’s S$100,000 limit applies per depositor, per Scheme member bank, in aggregate across all your accounts at that one bank. It doesn’t cap your total savings across every bank you use.
Are MariBank, Trust Bank, and GXS separately covered by SDIC?
Yes. MariBank Pte Ltd, Trust Bank Singapore Limited, and GXS Bank Pte Ltd are three separately licensed banks in Singapore, each its own SDIC Scheme member with its own S$100,000 of cover.
Does my Trust Bank balance share a cap with my Standard Chartered account?
No. Trust Bank operates in partnership with Standard Chartered, but it’s a separate legal entity and a separate SDIC Scheme member from Standard Chartered Bank (Singapore) Limited. The two balances are insured independently.
Is money held at IBKR protected by SDIC?
No. IBKR is a capital markets services licence holder regulated by MAS, not a bank, so SDIC doesn’t apply. Client cash is instead held in segregated trust accounts under MAS rules.
Is GXS's 3.20% p.a. promo still available?
It’s time-limited to 30 September 2026 and only applies to a 4-month Boost Pocket paired with a GXS Invest product. Outside that promo, GXS Boost Pocket pays up to 1.75% p.a. with no conditions.
What's the realistic Trust Bank rate, not the 2.40% headline?
Most savers land closer to 0.85% p.a. as a union member or 0.75% p.a. otherwise, from three achievable bonus scoops such as salary credit, card spend, and PayNow activity. The 2.40% headline needs a much larger invested balance or spend most people won’t sustain monthly.
What should I do once all three banks hold S$100,000 each?
Route further savings to IBKR for investing rather than parking it as idle cash, since IBKR pays little to nothing on small SGD balances and carries no SDIC cover. At that point the money is better put to work in a diversified portfolio than left sitting uninsured.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.