Singapore Savings Bond November 2026: Rates Projected at 2.44% — Apply by 25 October
The Singapore Savings Bond November 2026 (SBNOV26) is projected to deliver a 10-year average return of approximately 2.44% — a meaningful step up from October’s 2.32% and the highest projected average since early 2025. The Fed’s 25-basis-point rate hike in September 2026 has filtered into Singapore Government Securities yields, pushing SSB rates higher. Applications open 1 October 2026 and close 25 October 2026.
This is an editorial analysis. Not financial advice. Data verified as at 27 September 2026. SSB November 2026 rates are projected based on current SGS yields and are subject to confirmation on 1 October 2026.
- Projected 10-year average: ~2.44% p.a.
- Projected Year 1 rate: ~1.66% p.a.
- Application window: 1 October – 25 October 2026
- Minimum: S$500 | Maximum per person: S$200,000
- Channels: DBS/POSB, OCBC, UOB (internet banking, mobile, ATM)
- Key advantage: Zero lock-in — redeem any month, no penalty
What Is the Singapore Savings Bond November 2026?
The Singapore Savings Bond (SSB) is a government-backed savings instrument issued monthly by the Monetary Authority of Singapore (MAS). It is designed specifically for retail investors who want a safe, flexible home for their cash.
Unlike fixed deposits, SSBs have no lock-in period. You can redeem your SSB any month with no penalty, though you must give one month’s notice (applications for redemption submitted by the 25th of each month take effect the following month). Unlike T-bills, which pay a lump-sum return at maturity, SSBs pay interest monthly into your bank account — providing a steady income stream.
Each SSB tranche features a step-up interest rate: the rate rises each year you hold it. This structure rewards long-term savers while still allowing early exit without penalty. For November 2026, holding your bond for the full 10 years locks in a projected average of ~2.44% annually.
For a full primer on how SSBs work, see our complete Singapore Savings Bond guide for 2026. To model your returns at different holding periods, try our SSB interest calculator.
SSB November 2026 Projected Rates — Step-Up Schedule
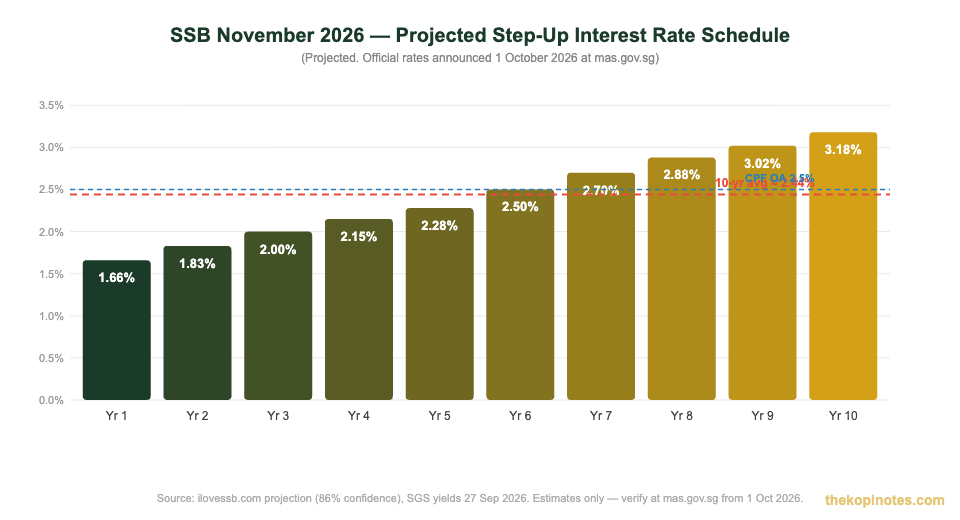
The official SSB November 2026 rates will be published by MAS on 1 October 2026. The projections below are based on current Singapore Government Securities (SGS) yields as tracked by ilovessb.com (86% confidence level as at 27 September 2026).
| Year | Projected Annual Rate | Effective Return |
|---|---|---|
| Year 1 | ~1.66% | 1.66% |
| Year 2 | ~1.83% | 1.75% |
| Year 3 | ~2.00% | 1.83% |
| Year 4 | ~2.15% | 1.91% |
| Year 5 | ~2.28% | 1.98% |
| Year 6 | ~2.50% | 2.07% |
| Year 7 | ~2.70% | 2.16% |
| Year 8 | ~2.88% | 2.25% |
| Year 9 | ~3.02% | 2.33% |
| Year 10 | ~3.18% | ~2.44% avg |
SSB November 2026 vs October 2026
November 2026 offers a 12-basis-point step up from October 2026 (2.32% average), reflecting SGS yield moves post the Fed’s September 2026 rate hike to 3.75–4.00%. If you missed the October deadline (closed 25 Sep 2026), November is your next chance — with a better rate.
How SSB November 2026 Compares: T-Bills, CPF, Fixed Deposits
| Option | Rate | Lock-In | Key Trade-Off |
|---|---|---|---|
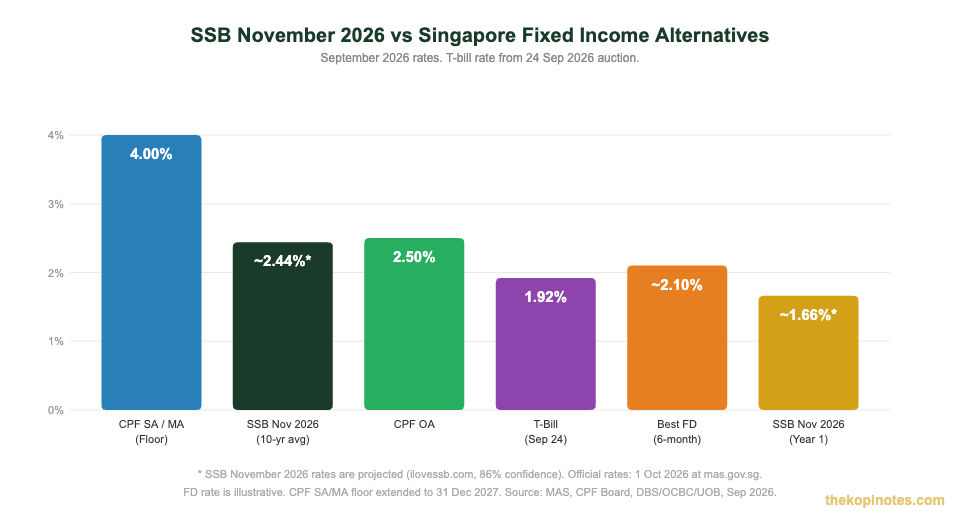
| SSB Nov 2026 (10-yr avg) | ~2.44% | None | Lower Year 1; higher long-term |
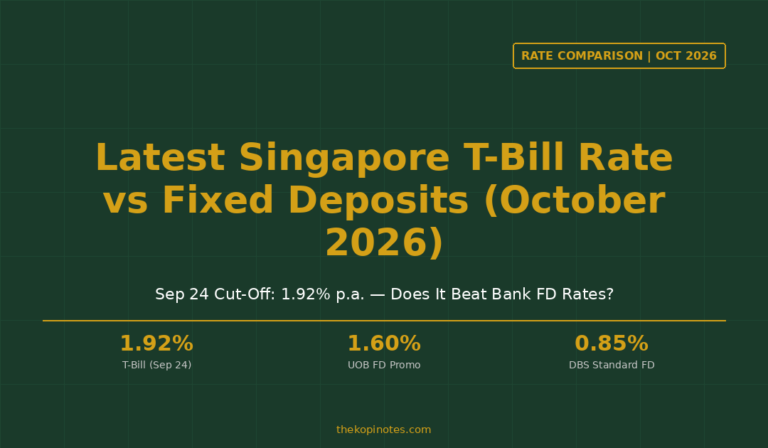
| 6-Month T-Bill (Sep 24) | 1.92% | 6 months | Locked until maturity |
| Best 6-Month FD | ~2.10% | 3–6 months | Good short-term; SDIC-insured |
| CPF OA | 2.5% | CPF withdrawal age | Locked |
| CPF SA/MA/RA | 4.0% (floor to Dec 2027) | Until 55 / retirement | Best rate; most restricted |
Why Are SSB Rates Rising in Late 2026?
Three forces are driving rates higher: (1) the Fed’s September 2026 hike to 3.75–4.00%, which passed through to SGS yields; (2) Singapore’s ~5% GDP growth in 2026 providing a floor to domestic rates; and (3) the Sep 24 T-bill yield jumping 22 bps to 1.92%, signaling market repricing of short-term rates upward. See our T-Bill vs SSB September 2026 guide for a detailed breakdown.
Who Should Apply for SSB November 2026?
Best fit: Investors with idle emergency fund cash earning under 1.5%; SRS account holders with undeployed cash; CPFIS-OA investors with uninvested funds; conservative retirees wanting capital preservation; anyone who missed the October 2026 deadline.
Probably pass: Those with full CPF SA/MA/RA earning 4% (156 bps above SSB); investors needing cash within 12 months (T-bill at 1.92% or FD at ~2.10% beats SSB Year 1 of ~1.66%).
How to Apply: Open 1 Oct, Closes 25 Oct 2026
Apply via DBS/POSB, OCBC, or UOB (internet banking, mobile, or ATM). Minimum S$500, maximum S$200,000 outstanding per person. Also available via CPFIS-OA and SRS channels. No lock-in, no fees, government-guaranteed.
The Kopi Notes Bottom Line
SSB November 2026 at ~2.44% 10-year average is among the best risk-free rates with zero lock-in available in Singapore today. For long-term savers with a 3–10 year horizon, this is the most compelling SSB tranche since early 2025. Watch for the official rate on 1 October 2026 at mas.gov.sg.
See also: Complete SSB Guide 2026 | SSB Calculator | SSB Glossary
Frequently Asked Questions: SSB November 2026
When will the official SSB November 2026 rates be announced?
What is the projected 10-year average for SSB November 2026?
What is the difference between SSB November and October 2026?
Can I use CPF OA or SRS money to apply?
Is there a lock-in period?
What happens if SSB November 2026 is oversubscribed?
How does SSB compare to CPF’s 4% SMRA rate?
Should I wait for December 2026 SSB?
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.