Is moomoo Safe for Savings? Cash Plus vs Bank Deposit Protection (2026)
Comparing MAS trust account protection vs SDIC coverage for MariBank, GXS & Trust Bank
moomoo is safe for investing and trading in Singapore — it holds a Capital Markets Services (CMS) licence from MAS and is legally required to segregate all client assets in trust accounts. However, moomoo Cash Plus is not a bank deposit and is not covered by SDIC deposit insurance. If your priority is government-backed deposit protection up to S$75,000, MariBank, GXS Bank, and Trust Bank offer that as fully licensed banks. If you want higher indicative yields (~3.5–4.5% p.a.) and are comfortable with money market fund risk, moomoo Cash Plus is a credible option.
Not financial advice. All figures are for educational reference only. Data verified as at 2 October 2026. Always verify rates directly with each provider before making financial decisions.
📋 What You’ll Find in This Guide
- The short answer — is moomoo safe for cash?
- moomoo is not a bank — what that means
- 3 protection layers for moomoo Cash Plus
- What moomoo Cash Plus actually is
- SDIC-covered digital banks: MariBank, GXS, Trust Bank
- Side-by-side safety comparison table
- What happens if moomoo fails?
- When to choose moomoo vs a licensed bank
- Frequently asked questions
The Short Answer: Is moomoo Safe for Cash?
Yes — with an important distinction. moomoo Singapore (operated by Futu Singapore Pte. Ltd.) is a MAS-licensed Capital Markets Services (CMS) licensee, not a bank. This means your money held on the platform is protected differently depending on where it sits:
| Where Your Money Is | Type of Protection | Government Guarantee? |
|---|---|---|
| moomoo Cash account (uninvested cash) | MAS trust account segregation | No SDIC, but legally ring-fenced |
| moomoo Cash Plus (money market account) | Underlying fund assets in custodian trust | No SDIC; fund risk applies |
| MariBank / GXS / Trust Bank savings accounts | SDIC deposit insurance | Yes — up to S$75,000 per bank |
Source: MAS, SDIC Singapore | Data as at October 2026
The key takeaway: moomoo is a regulated and credible platform, but it operates under different rules than a bank. Understanding what those rules mean for your cash is what this guide is all about.
moomoo Is Not a Bank — What This Means for Your Cash
When you deposit money at DBS, OCBC, or even a newer digital bank like MariBank or GXS, you are making a bank deposit. That deposit is backed by the bank’s balance sheet and, up to S$75,000, by the Singapore Deposit Insurance Corporation (SDIC).
moomoo’s business model is fundamentally different. As a CMS licensee, moomoo earns revenue from brokerage fees and platform services — not from lending out your deposits. Under the Securities and Futures Act (SFA), moomoo is required by MAS regulations to:
- Hold all client monies in a segregated trust account at a licensed bank, separate from moomoo’s own operating funds
- Maintain accurate books and records of each client’s holdings
- Not commingle client assets with company assets
This trust account structure is meaningful protection — it means moomoo cannot use your money to pay its own bills if things go wrong. But it is not deposit insurance. If the underlying custodian bank holding the trust account were to fail, SDIC might cover those trust funds (since they’re held at a licenced bank), but the chain of recovery is more complex than a direct bank deposit. In practice, moomoo holds its client trust accounts at major Singapore-licensed banks — an additional layer of stability.
For a full breakdown of moomoo’s regulatory standing and its past MAS regulatory fine (and what it means), see our in-depth is moomoo safe Singapore guide.
3 Protection Layers for moomoo Cash
While moomoo does not carry SDIC insurance, it is not unprotected. Here are the three legal and structural layers that cover your cash on the platform:
Layer 1 — MAS Licensing and Oversight
moomoo Singapore holds an active MAS Capital Markets Services licence for dealing in capital markets products. MAS conducts ongoing supervision including periodic audits and reporting requirements. If moomoo were to lose its licence or be wound down, MAS would supervise the process of returning client assets.
Layer 2 — Mandatory Client Asset Segregation
Under the SFA and MAS Notice SFA04-N12, all client monies must be held in a designated trust account at a Singapore-licensed bank, separate from moomoo’s own funds. Your uninvested SGD cash is held this way. This segregation means moomoo’s creditors cannot claim your cash if moomoo becomes insolvent.
Layer 3 — moomoo’s Parent Company Strength
moomoo is operated by Futu Holdings Ltd (Nasdaq: FUTU), a publicly listed company with a multi-billion dollar market cap, quarterly financial disclosures, and institutional shareholders. This is not the same as deposit insurance, but it provides a level of transparency and financial robustness that a startup would not have.
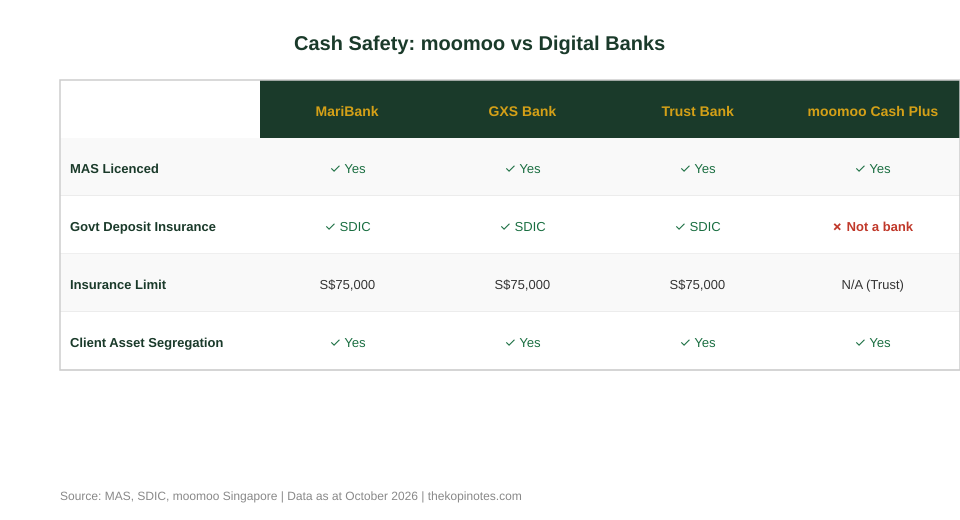
Source: MAS, SDIC, moomoo Singapore | Data as at October 2026 | thekopinotes.com
What Is moomoo Cash Plus, Exactly?
moomoo Cash Plus is often described as a “cash management” feature, but it is more precisely a money market account — it invests your idle cash into a portfolio of short-duration, high-quality money market instruments (such as Singapore government securities, bank-issued notes, and similar instruments). The return you see (quoted as an indicative annual yield) comes from the returns generated by this underlying fund, not from a fixed bank rate.
This is a critical distinction because:
- The rate is indicative, not guaranteed — it moves with short-term interest rates and the underlying fund’s performance
- Your money is invested in a fund, not deposited at a bank, so it carries money market fund risk (though historically very low)
- It is not covered by SDIC, since SDIC only covers bank deposits, not fund investments
- Liquidity is typically same-day or next-day — similar to most savings accounts
As of October 2026, moomoo Cash Plus has been offering indicative yields in the range of approximately 3.5–4.5% p.a. for SGD. This is noticeably above what most digital bank savings accounts offer. The trade-off is the absence of deposit insurance. For a deeper look at how the product works, see our moomoo Cash Plus review.
Money market funds in Singapore are generally very low-risk — they invest in investment-grade, short-duration instruments and are tightly regulated. But they are not risk-free. In extreme market dislocations, money market fund NAVs can “break the buck” (fall below S$1.00 per unit), though this is exceedingly rare for funds investing in SGD government and quasi-government instruments.
SDIC-Covered Digital Banks: MariBank, GXS, Trust Bank
Singapore’s three digital banks — MariBank, GXS Bank, and Trust Bank — are all fully licensed by MAS under the Banking Act. This means they operate as genuine banks with SDIC deposit insurance covering deposits up to S$75,000 per depositor per institution.
Here is a snapshot of what each currently offers for savings (rates and conditions are subject to change — always check the bank’s official website for the most current terms):
| Bank | Product Name | Indicative Rate | Key Conditions | SDIC Covered |
|---|---|---|---|---|
| MariBank | SaveUp | ~2.5–2.7% p.a. | Min. S$1,000; may require Shopee activity for bonus | ✓ Yes |
| GXS Bank | FlexiSavings / Pockets | ~1.75–2.6% p.a. | Variable rate; tiered by balance | ✓ Yes |
| Trust Bank | Trust Savings | ~1.7–2.2% p.a. | Bonus rate with Standard Chartered card spend | ✓ Yes |
Source: MariBank, GXS Bank, Trust Bank official sites | Rates indicative as at October 2026. Subject to change.
These digital banks are convenient, app-based, and offer competitive rates by traditional Singapore banking standards. The SDIC protection up to S$75,000 makes them the natural choice for emergency funds or money you absolutely cannot afford to put at any risk.
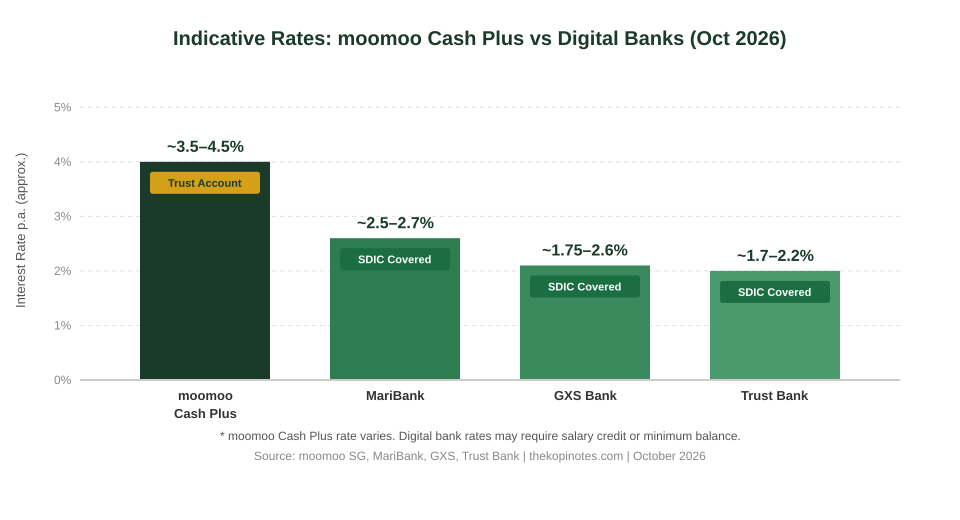
Source: moomoo SG, MariBank, GXS, Trust Bank | Rates indicative, subject to change | thekopinotes.com | October 2026
moomoo Cash Plus vs Digital Banks: Full Safety Comparison
| Feature | moomoo Cash Plus | MariBank | GXS Bank | Trust Bank |
|---|---|---|---|---|
| MAS Regulated | ✓ CMS Licence | ✓ Bank Licence | ✓ Bank Licence | ✓ Bank Licence |
| SDIC Deposit Insurance | ✗ No | ✓ Up to S$75k | ✓ Up to S$75k | ✓ Up to S$75k |
| Client Asset Segregation | ✓ Trust Account | N/A (bank owns deposits) | N/A (bank owns deposits) | N/A (bank owns deposits) |
| Indicative Rate (Oct 2026) | ~3.5–4.5% p.a. | ~2.5–2.7% p.a. | ~1.75–2.6% p.a. | ~1.7–2.2% p.a. |
| Rate Type | Indicative (varies daily) | Variable (tiered) | Variable (tiered) | Variable (tiered) |
| Withdrawal Speed | Same-day / T+1 | Instant | Instant | Instant |
| Best For | Higher yield seekers with existing moomoo account | Safety-first savers, Shopee users | Grab / GXS ecosystem users | SC card holders |
Source: MAS, SDIC, individual bank and moomoo official sites | Data as at October 2026
What Happens If moomoo Fails?
This is the key question for anyone parking meaningful cash on the platform. Here is the most accurate answer based on how MAS rules work in practice:
Uninvested cash in your moomoo account is held in a designated trust account at a Singapore-licensed bank, separate from moomoo’s own funds. If moomoo were placed in insolvency, a liquidator would be appointed to return these trust assets to clients. The process would take time, but your cash is legally ring-fenced from moomoo’s creditors. MAS’s supervisory role would ensure this process is managed in an orderly manner.
moomoo Cash Plus units are units in an underlying money market fund. In an insolvency scenario, these units still belong to you — they are held by a custodian bank on behalf of investors. The custodian would facilitate redemption of those units back to clients. The value at redemption would depend on the fund’s NAV at that time, which for a money market fund should be close to par.
In summary: moomoo failing would cause delays and inconvenience, but it should not result in total loss of your funds, given the regulatory requirements for segregation. However, this is very different from the certainty and immediacy of SDIC coverage at a bank, where the SDIC can begin compensating depositors within 3 months of a bank failure.
For investors using moomoo for ETFs and equities, the same trust account rules protect your securities. See our guide on is moomoo safe for Singapore investors for more on securities protection.
When to Choose moomoo Cash Plus vs a Digital Bank
Here is a practical decision framework for Singapore savers:
Choose moomoo Cash Plus if:
- You already have a moomoo account and want to put idle brokerage cash to work
- You have savings above the S$75,000 SDIC limit and are already spreading across multiple banks
- You are comfortable with money market fund mechanics and are not relying on SDIC insurance
- The higher indicative yield (often 1–2% above digital bank rates) is meaningful to you over a 6–12 month horizon
Choose a digital bank (MariBank / GXS / Trust Bank) if:
- You want government-backed deposit insurance — especially for emergency funds
- You have S$75,000 or less to park and want the clearest possible safety net
- You prefer instant withdrawal without any T+1 settlement risk
- You are building up a Singapore retirement nest egg and want the simplest, safest structure — pair this with our Singapore retirement calculator to model your savings trajectory
Consider both: Many Singapore investors use a combination — SDIC-covered accounts at digital banks for their core emergency fund (6 months of expenses), and moomoo Cash Plus for surplus savings above that threshold where the extra yield compounds meaningfully over time. For capital market alternatives with government backing, also consider Singapore T-bills and Singapore Savings Bonds, which carry full sovereign backing.
If you are looking at Syfe Cash+ or other robo-advisor cash management alternatives, check the Syfe referral code page for current sign-up bonuses alongside rate comparisons.
If you decide moomoo is the right fit for your investing and cash management needs, you can sign up using referral code YONG477 for current welcome rewards.
Open a moomoo Account Today
Use referral code YONG477 when you sign up — get current welcome rewards including trading vouchers and Cash Plus bonus interest for new users.
Frequently Asked Questions
Is moomoo Cash Plus covered by SDIC?
What is the SDIC deposit insurance limit in Singapore?
Are MariBank, GXS, and Trust Bank covered by SDIC?
Is it safe to keep more than S$75,000 on moomoo?
What happens to my moomoo Cash Plus if moomoo closes down?
Is moomoo a licensed bank in Singapore?
Should I use moomoo Cash Plus or a digital bank for my emergency fund?
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.