Latest Singapore T-Bill Rate (Sep 2026):
Does 1.92% Beat Fixed Deposits?
Updated 26 September 2026 | 6-minute read
The September 24, 2026 Singapore T-bill auction closed at a cut-off yield of 1.92% per annum — the highest rate in 2026 and up 22 basis points from 1.70% at the previous auction. Driven by the US Federal Reserve’s September 2026 rate hike, Singapore savers are now asking the same question: is the latest T-bill rate actually better than putting cash in a bank fixed deposit?
Not financial advice. All figures are for educational reference only. Data as at September 2026 unless noted.
- Latest 6-month T-bill cut-off: 1.92% p.a. (Sep 24, 2026) — a 2026 high
- T-bills beat standard bank FD rates (DBS 0.85%, OCBC 1.35%) but lose to some promotional rates (Citibank 2.00%)
- Next auction is around Oct 8, 2026 — if rates stay elevated, it may be worth applying
Latest Singapore T-Bill Cut-Off Rate
The most recent Singapore 6-month Treasury Bill auction took place on 24 September 2026. The cut-off yield was 1.92% per annum.
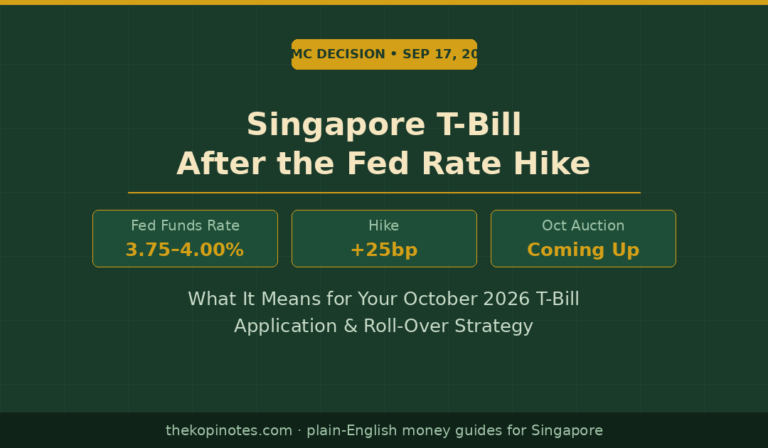
That is the highest cut-off rate for any Singapore T-bill auction in 2026. It jumped from 1.70% at the September 10 auction — a rise of 22 basis points in just two weeks. The catalyst: the US Federal Reserve raised its benchmark rate by 25 basis points at its September 17, 2026 FOMC meeting, the first hike since 2023.
Here is a summary of the most recent auctions:
| Auction Date | T-Bill Code | Cut-Off Yield (p.a.) | Change |
|---|---|---|---|
| 24 Sep 2026 | BS26119F | 1.92% | +22 bps |
| 10 Sep 2026 | BS26105F | 1.70% | +8 bps |
| 27 Aug 2026 | BS26096F | 1.50% | +8 bps |
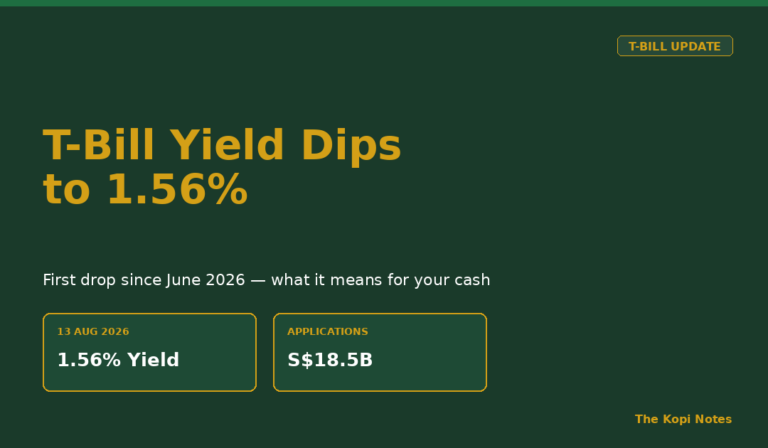
| 13 Aug 2026 | BS26082F | 1.42% | +7 bps |
Source: Monetary Authority of Singapore (MAS) SGS auction results, September 2026
All Singapore 6-month T-bills are denominated in SGD, issued and backed by the Singapore government (AAA-rated), and pay no coupons — you simply buy at a discount and receive face value at maturity.
T-Bill vs Fixed Deposit — Rate Comparison Table
The big question: is 1.92% actually competitive? Here is how it stacks up against the best 6-month fixed deposit rates available in Singapore as of late September 2026.
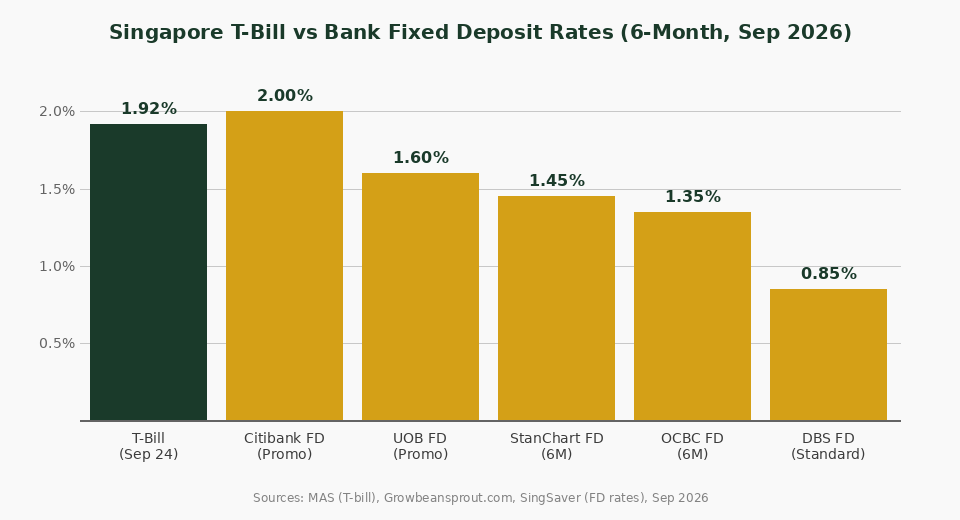
| Product | Rate (p.a.) | Min. Amount | Notes |
|---|---|---|---|
| T-Bill (Sep 24) | 1.92% | S$1,000 | Auction — rate not guaranteed until result |
| Citibank FD (Promo) | 2.00% | S$5,000 new funds | Eligible new funds only; 6M tenor |
| UOB FD (Promo) | 1.60% | S$10,000 | Promo ended Sep 30, 2026 — check current rate |
| Standard Chartered FD | 1.45% | S$25,000 | 6-month; varies by placement channel |
| OCBC FD (Online) | 1.35% | S$20,000 | 6-month online placement |
| DBS FD (Standard) | 0.85% | S$1,000 | Standard rate; 6-12 months |
Sources: MAS (T-bill), Growbeansprout.com, SingSaver (FD rates), September 2026. FD rates change frequently — verify on each bank’s website before placing.
The verdict: At 1.92%, T-bills beat most standard bank FD rates comfortably. The only product that tops T-bills is Citibank’s promotional rate at 2.00%, which requires new funds and has eligibility conditions. If you already have cash parked at DBS or OCBC, switching to T-bills for the next 6 months could earn you meaningfully more — on S$50,000, the difference between 0.85% and 1.92% is roughly S$535 extra per year.
Why T-Bills Have an Edge Over Fixed Deposits
Purely on the headline rate, T-bills look attractive right now. But there are other factors worth considering beyond the number itself.
Government Guarantee vs Bank Guarantee
T-bills are direct obligations of the Singapore government, which is AAA-rated. Fixed deposits, on the other hand, are covered by the Singapore Deposit Insurance Corporation (SDIC) up to S$75,000 per depositor per bank. For amounts below S$75,000, the protection is similar. Above that threshold, T-bills have no cap.
No Minimum (Beyond S$1,000)
You can apply for T-bills from as little as S$1,000, in multiples of S$1,000. Most competitive FD rates require S$10,000 to S$25,000 minimum. If you have smaller amounts to park, T-bills may be more accessible.
Tax Treatment
T-bill discount income is not subject to Singapore income tax for individual investors. Bank interest income is similarly exempt from Singapore income tax for individuals. So both products are tax-neutral for most Singapore residents. For Singapore companies or investment entities, treatment differs — consult IRAS directly.
The Auction Risk
Here is the key difference: you do not know your exact rate before the T-bill auction closes. You submit a competitive or non-competitive bid, and if the cut-off yield is lower than your bid (or you applied non-competitively), you receive the cut-off rate. Your money could also be returned if the auction is heavily oversubscribed and your bid falls short.
Fixed deposits, by contrast, give you a confirmed rate on the spot. No auction uncertainty. If rate certainty matters to you — say, you are matching cash flow to a known upcoming expense — FDs win on predictability.
For a deeper dive into how T-bills work, see the T-bill Singapore 2026 complete guide.
Singapore T-Bill Rate Trend in 2026
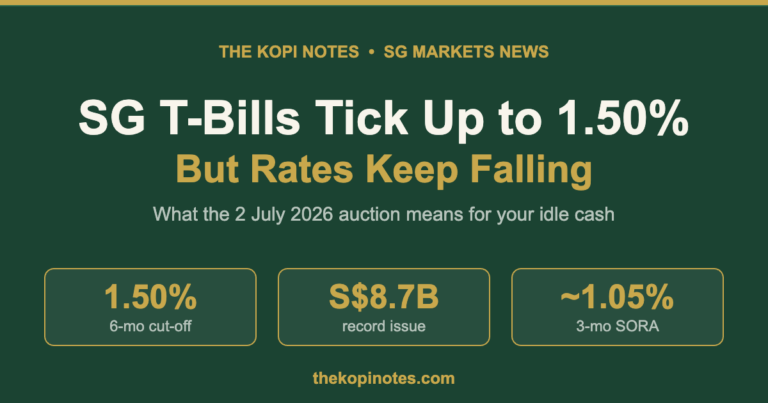
Singapore’s T-bill rates started 2026 below 1.10% per annum. Global rate cuts by the US Federal Reserve throughout 2024 and 2025 had pushed rates lower. Then, in September 2026, the Fed reversed course with a 25-basis-point hike — and Singapore’s T-bill cut-offs responded quickly.
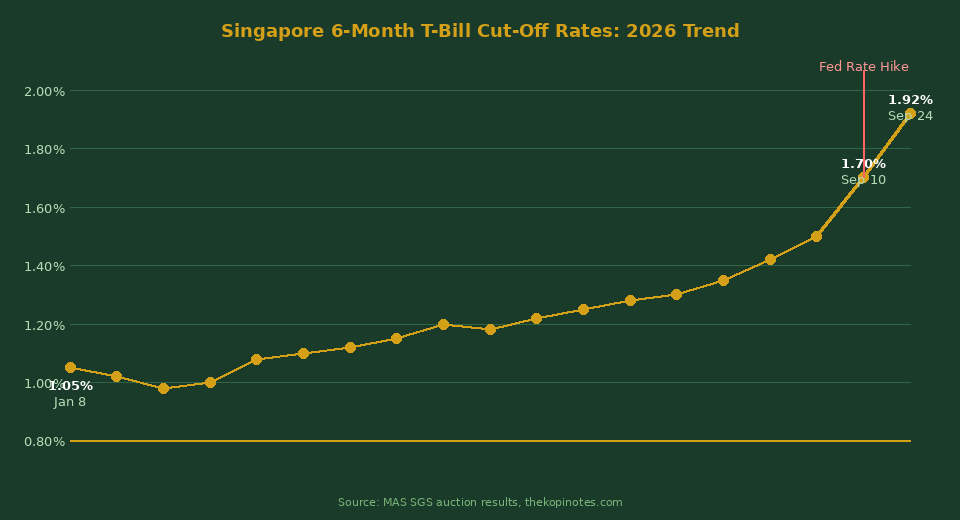
The rate trajectory tells an important story. From January through July 2026, 6-month cut-offs were mostly in the 1.00%–1.35% range — decent but not exciting for cash savers. The pace of increases picked up sharply in August and September, driven by rising US Treasury yields and growing expectations that the Fed’s hiking cycle had resumed.
Whether the October auction hits 2.00% or pulls back slightly will depend on global bond markets and local subscription demand. A highly oversubscribed auction (which typically happens when rates are rising and investors rush in) can sometimes push the cut-off lower, even if the broad yield environment is higher.
When Is the Next T-Bill Auction?
MAS runs 6-month T-bill auctions on a roughly two-week cycle (Thursdays). Following the September 24 auction, the next expected auction date is around 8 October 2026. The application window typically closes two business days before the auction — so around 7 October 2026.
How to Apply for Singapore T-Bills
You can apply for T-bills through three main channels:
- ATM (DBS/POSB, OCBC, UOB) — Select “SGS Bonds and T-bills” from the main menu. Cash applications deduct from your bank account and are held until the auction result.
- Internet banking (DBS/POSB, OCBC, UOB) — Look for “SGS / T-Bills” or “Invest” section. You can set a competitive bid or apply at the cut-off (non-competitive).
- CDP Online — Apply via the SGS website using your CDP account. Your funds are debited from the bank account linked to your CDP account.
If you apply via CPF Investment Scheme (CPFIS-OA), your CPF Ordinary Account funds are used and interest earned goes back into your CPF-OA. For CPFIS, you must apply through your CPF Investment Account with a participating broker.
For step-by-step application details and platform comparisons, the T-bill Singapore complete guide has full screenshots and timings. You may also want to check the September 24 T-bill auction breakdown for the most recent result context.
T-Bill vs FD: Which Is Right for You in Q4 2026?
Here is a practical decision framework based on your situation:
| Your Situation | Better Choice | Why |
|---|---|---|
| Have S$5,000+ in new funds, OK with Citibank | Citibank FD 2.00% | Higher confirmed rate, no auction risk |
| Have S$1,000–S$20,000 idle in DBS/OCBC | T-Bill | 1.92% likely beats standard FD rates significantly |
| CPF OA funds earning 2.5% in CPF | Leave in CPF OA | CPF OA 2.5% is risk-free and beats T-bill |
| Need rate certainty for a known expense in 6M | FD | Confirmed rate on placement, no auction uncertainty |
| Want maximum safe yield, flexible amount | T-Bill | Best government-backed rate with no large minimum |
Table: Decision framework based on common Singapore saver scenarios. Not personalised financial advice.
For long-term wealth building beyond cash savings, consider how T-bills fit within a broader investment strategy. Our CPF investment strategy guide covers how to maximise CPF returns alongside market investments. If you are looking at ETFs as a complement to T-bill cash holdings, Syfe’s Syfe Cash+ Enhanced (referral code SRPRFFFCD) and FSMOne’s FSMOne platform (referral code P0544985) offer cash management solutions alongside investment options.
For retirement planning in the context of rising interest rates, our Singapore retirement calculator can show you how today’s rates affect your savings projections.
Frequently Asked Questions
What is the latest Singapore T-bill cut-off rate?
Is the T-bill rate better than fixed deposits right now?
When is the next Singapore T-bill auction in October 2026?
Can I use CPF to buy T-bills?
How do I apply for Singapore T-bills step by step?
Is T-bill income taxable in Singapore?
What happens if I miss the T-bill application deadline?
The Bottom Line
At 1.92% per annum, the latest Singapore T-bill cut-off beats most standard bank fixed deposit rates. It falls short of Citibank’s promotional 2.00% offer (which has eligibility conditions), but for everyday savers with cash sitting in DBS or OCBC standard FDs, T-bills are a clear upgrade right now.
The next T-bill auction around October 8, 2026 could push rates slightly higher if global yields continue rising — or pull back if the auction is heavily oversubscribed. Either way, keeping S$1,000–S$50,000 in T-bills instead of a standard savings account or low-yield FD is a straightforward way to improve your cash returns in Q4 2026.
This article is for general information only and does not constitute financial advice. Always verify current rates at official bank and MAS sources before making any financial decisions.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.