Endowus vs MariBank 2026: Managed Investing Platform or Zero-Fee Fund Access?
Endowus charges a tiered advisory fee for CPF-eligible managed portfolios. MariBank’s new Mari Invest charges zero platform fee on four funds, cash only. Here’s which fits your money.
Endowus is a CPFIS-approved robo-advisor and fund platform charging a tiered access fee (0.60% down to 0.25% on cash, 0.40% on CPF/SRS) across 400-plus funds, including CPF OA, SA and SRS money. MariBank is a digital full bank whose Mari Invest feature charges zero platform fee but offers only four funds, cash only, with no CPF or SRS support. Endowus suits CPF and SRS investors who want managed rebalancing; MariBank suits cash-only investors who want to self-select a single fund at no extra cost.
Not financial advice. All figures are for educational reference only and verified against endowus.com/pricing and maribank.sg/fees-rates as at November 2026 unless otherwise dated.
Table of Contents
Quick Answer: Endowus or MariBank?
For a Singapore investor who wants to put CPF OA, CPF SA or SRS money to work in a diversified, professionally rebalanced portfolio, Endowus is the clear choice — MariBank’s Mari Invest does not accept CPF or SRS funds at all, cash only. For a cash-only investor who wants to self-select a single fund (income, gold, or Singapore dividend equity) without paying any platform-level fee on top of the fund manager’s own charge, MariBank’s Mari Invest is genuinely cheaper on paper — but it is execution-only, with no advice, no model portfolios and no automatic rebalancing across four funds.
The two platforms are not really substitutes for each other. Endowus is a managed wealth platform with CPFIS approval (licence CMS101051) spanning more than 400 funds across equity, bond, multi-asset and income categories, plus a dedicated low-risk Cash Smart range. MariBank is a Monetary Authority of Singapore-licensed digital full bank whose Mari Invest tab bolts four fund options onto an otherwise deposit-and-payments product, alongside the Mari Savings Account, Mari Credit Card and Instant Loan.
Key Differences at a Glance
| Feature | Endowus | MariBank (Mari Invest) |
|---|---|---|
| Regulator / Licence | MAS Capital Markets Services licence CMS101051; CPFIS-approved | MAS digital full bank (DFB) licence |
| Core product | Managed robo-advisor portfolios + fund marketplace | Digital bank account with a self-select fund tab |
| Number of funds | 400-plus (Flagship, Satellite, Income, Cash Smart) | 4 (SavePlus, PIMCO Income, Gold, SG Dividend Equity) |
| CPF OA / SA eligible | Yes | No |
| SRS eligible | Yes | No |
| Platform/access fee | 0.60%–0.25% p.a. (cash, tiered); 0.40%/0.30% (CPF/SRS) | 0% — free |
| Sales charge / withdrawal fee | None (Endowus is fee-only, no sales charge) | None — free |
| Fund manager’s own fee | Varies by fund, typically 0.05%–1% p.a. TER | 0.25%–1.25% p.a. (factored into NAV) |
| Rebalancing / advice | Automatic rebalancing on model portfolios | None — execution-only, self-select one fund |
| Minimum investment | S$10 (Cash Smart), S$1,000 (Flagship/Satellite) | No published minimum via app |
| Banking features | None — not a bank account | Full digital bank: savings account, debit/credit card, instant loan |
Source: endowus.com/pricing and maribank.sg/fees-rates/mari-invest, verified November 2026.
Fee Structure: Advisory Fee vs Zero Platform Fee
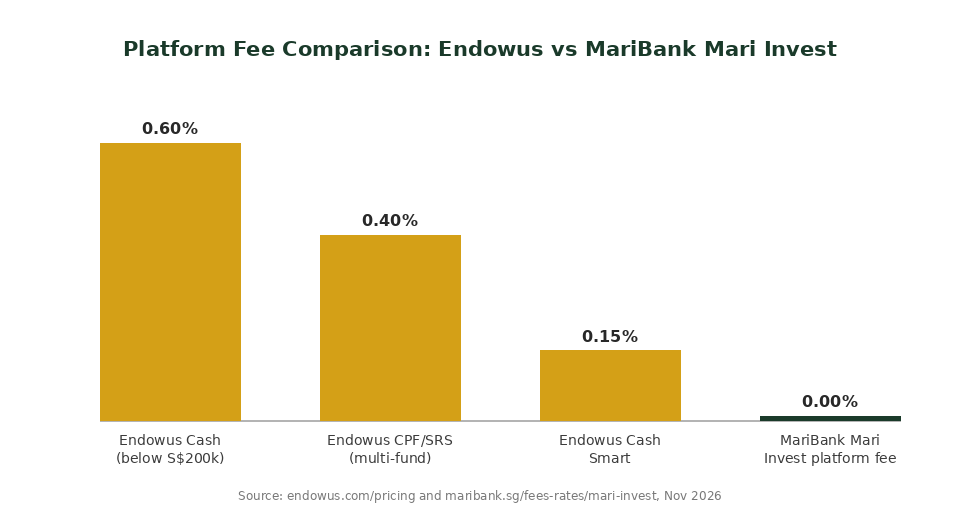
Endowus charges a tiered access fee on top of the fund manager’s own charge: 0.60% a year below S$200,000 in cash, stepping down to 0.50% between S$200,000 and S$1 million, then 0.30% up to S$5 million, and 0.25% above that, according to endowus.com/pricing (verified November 2026). CPF and SRS money is priced separately from cash — a flat 0.40% a year for multi-fund portfolios or 0.30% for a single-fund portfolio, regardless of balance size. This fee pays for advice, model-portfolio construction and automatic rebalancing across the chosen asset allocation.
MariBank’s Mari Invest, by contrast, charges absolutely nothing on top: no account opening fee, no account maintenance fee, no upfront fee, no sales charge and no withdrawal fee, per maribank.sg/fees-rates/mari-invest. The only cost an investor bears is the annual management fee charged by the underlying fund manager, which is already factored into the daily unit price — Lion-MariBank SavePlus at 0.25% p.a., LionGlobal Singapore Physical Gold Fund at 0.50% p.a., PIMCO GIS Income Fund at 1.05% p.a., and the Amova Singapore Dividend Equity Fund at 1.25% p.a.
Worked example: A Singapore investor with S$50,000 in cash choosing between Endowus’s lowest-cost diversified option (Cash Smart, flat 0.15% access fee) and MariBank’s lowest-cost Mari Invest fund (Lion-MariBank SavePlus, 0.25% p.a. fund fee, zero platform fee) would pay roughly S$75 a year on Endowus versus roughly S$125 a year on MariBank — but the two are not directly comparable products: Cash Smart is a managed basket of money market and short-duration bond funds, while SavePlus is a single fund with no Endowus-style tiered access fee to begin with.
CPF and SRS Eligibility
This is the sharpest dividing line between the two platforms. Endowus holds CPFIS approval under licence CMS101051, which means CPF Ordinary Account and CPF Special Account savings, as well as Supplementary Retirement Scheme funds, can be invested directly through the platform into eligible unit trusts — subject to the usual CPF Board and MOF administrative rules, not Endowus’s own. MariBank’s Mari Invest accepts cash only; there is no published pathway on maribank.sg to fund an investment with CPF OA, CPF SA or SRS money, which rules it out entirely for an investor whose primary pool of investable money sits in CPF or SRS.
For context on how CPF money can be deployed more broadly, see our CPF investment strategy guide and our Endowus CPFIS 2026 guide for the full CPF OA mechanics.
Cash Yield: Savings Account vs Cash Smart
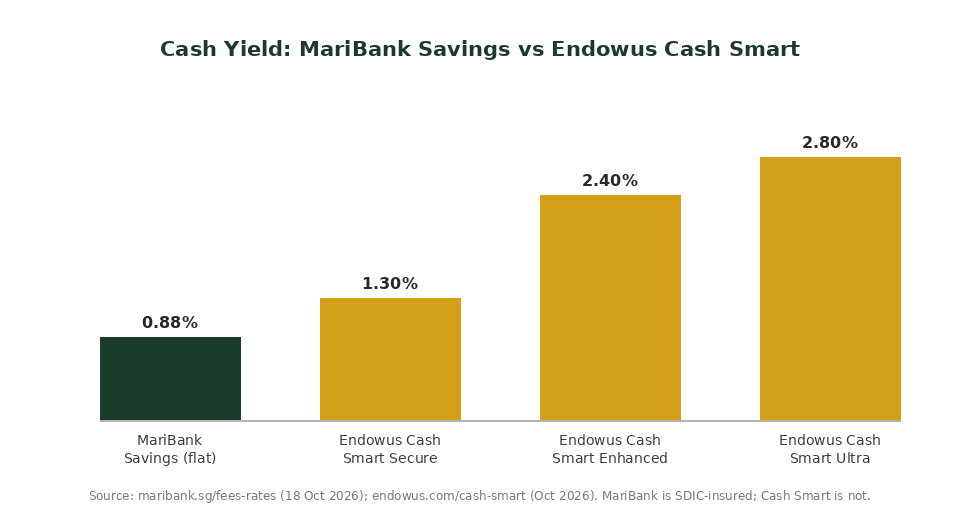
Outside of Mari Invest, MariBank’s core product is the Mari Savings Account, paying a flat 0.88% p.a. on SGD balances with no conditions attached, effective 18 October 2026 per maribank.sg/fees-rates/mari-savings-account. It is SDIC-insured up to S$100,000, meaning the principal is protected by Singapore’s Deposit Insurance Scheme regardless of market conditions. There is also a promotional 1.88% p.a. rate on USD balances running until 31 December 2026, after which the base rate applies.
Endowus Cash Smart is a different animal — it invests cash into a basket of money market and short-duration bond unit trusts rather than holding it as a bank deposit, so the net yields are projected, not guaranteed, and not SDIC-insured: Secure around 1.3% p.a., Enhanced around 2.4% p.a. and Ultra around 2.8% p.a., based on endowus.com/cash-smart (as at October 2026). The trade-off is clear: MariBank offers a lower, flat, SDIC-insured rate with zero downside risk; Endowus Cash Smart offers a higher projected yield with a small historical maximum drawdown (roughly -0.05% to -2.9% depending on tier) because the underlying funds do carry market risk.
Product Breadth Beyond Investing
Because MariBank is a licensed digital full bank and Endowus is not, MariBank has banking features Endowus simply does not offer: the Mari Credit Card (no annual fee, no foreign transaction fee as part of its 2026 proposition), the Mari Debit Card, and the Instant Loan feature with rates starting from roughly 1.28% p.a. flat. Endowus has no credit card, debit card or lending product — it is purely an investment and advisory platform. An investor who wants one app for daily banking, spending and a side pocket of fund investing will find MariBank more complete; an investor who wants the broadest possible fund selection with CPF and SRS support will need Endowus (or a combination of both).
For readers comparing MariBank against other digital banks on the savings side specifically, see our MariBank vs Trust Bank 2026 comparison and our Endowus Cash Smart vs GXS Savings piece for a second cash-yield angle.
Who Should Pick Which?
Choose Endowus if: you have CPF OA, CPF SA or SRS money you want to invest; you want a professionally constructed, automatically rebalanced portfolio rather than picking a single fund yourself; you want access to 400-plus funds across equity, bond, multi-asset, income and satellite themes; or you want a dedicated cash management product (Cash Smart) with higher projected yield than a flat bank rate.
Choose MariBank if: all your investable money is cash (not CPF or SRS); you are comfortable self-selecting one of four funds without advice or rebalancing; you want zero platform-level fee beyond the fund manager’s own charge; or you primarily want MariBank for its SDIC-insured savings account, credit card and instant loan, with Mari Invest as a convenient add-on rather than your main investment vehicle.
Many Singapore investors end up using both: MariBank for everyday banking and SDIC-insured cash parking, and Endowus for CPF, SRS and the bulk of their long-term diversified investing. Our passive income Singapore guide and retirement calculator can help map out how much of each pot you actually need.
Frequently Asked Questions
What is the main difference between Endowus and MariBank?
Endowus is a CPFIS-approved robo-advisor and fund platform with more than 400 funds, a tiered access fee, and support for CPF OA, CPF SA and SRS money. MariBank is a digital full bank whose Mari Invest feature offers only four self-select funds at zero platform fee, cash only, alongside a savings account, credit card and instant loan.
Can I invest my CPF or SRS money through MariBank?
No. MariBank’s Mari Invest only accepts cash. If you want to invest CPF OA, CPF SA or SRS funds, Endowus is CPFIS-approved (licence CMS101051) and accepts all three money types directly through the platform.
Is MariBank's Mari Invest really free to use?
MariBank itself charges no account opening fee, maintenance fee, sales charge or withdrawal fee on Mari Invest. You still pay the underlying fund manager’s own annual management fee — ranging from 0.25% p.a. (Lion-MariBank SavePlus) to 1.25% p.a. (Amova Singapore Dividend Equity Fund) — which is factored into the daily unit price, not charged separately.
Which gives a better cash yield, MariBank Savings or Endowus Cash Smart?
MariBank’s Mari Savings Account pays a flat 0.88% p.a., SDIC-insured up to S$100,000, with no market risk. Endowus Cash Smart’s projected net yields are higher (roughly 1.3% to 2.8% p.a. depending on tier) but are not SDIC-insured and carry a small historical maximum drawdown, since the money sits in money market and short-duration bond funds rather than a bank deposit.
Does Endowus or MariBank offer automatic portfolio rebalancing?
Endowus offers automatic rebalancing on its model portfolios (Flagship, Satellite and Income ranges), which is part of what the tiered access fee pays for. MariBank’s Mari Invest is execution-only — you pick one of four funds yourself and there is no rebalancing or advisory layer.
Can I use both Endowus and MariBank at the same time?
Yes. There is no restriction on holding accounts with both. A common approach is to use MariBank for everyday banking and SDIC-insured savings, and Endowus for CPF, SRS and the bulk of long-term diversified fund investing.
Ready to Start Investing?
Open an account with Endowus or MariBank and use our referral links for sign-up bonuses.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.