Endowus Cash Smart vs GXS Savings Account 2026: Guaranteed Bank Rate or Higher Projected Fund Yield?
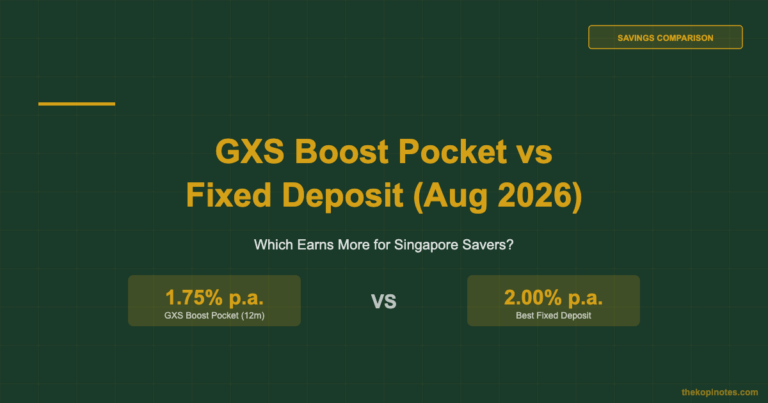
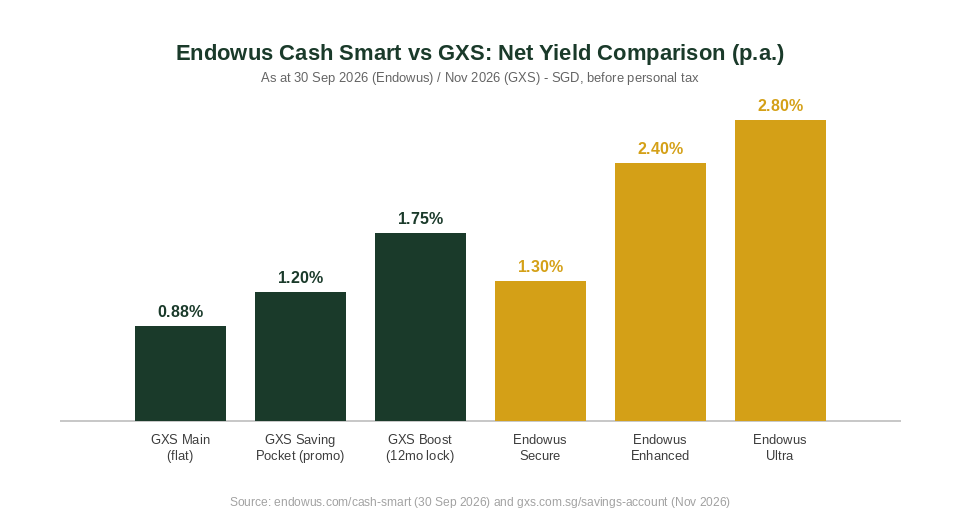
GXS pays a flat 0.88% p.a. on its Main Account (up to 1.75% on a 12-month locked Boost Pocket) and is SDIC-insured up to S$100,000, but GXS is cash-only and cannot hold SRS money at all. Endowus Cash Smart pays more — 1.3% (Secure), 2.4% (Enhanced) or 2.8% (Ultra) net yield as at 30 September 2026 — and accepts SRS funds too, but none of it is SDIC-insured since Cash Smart holds money market and bond funds, not a bank deposit.
Not financial advice. All figures are for educational reference only. Data as at November 2026 unless noted.
Table of Contents
What Endowus Cash Smart Actually Pays
Endowus Cash Smart is a family of three advised cash management portfolios, not a bank account. A Singapore investor parking S$30,000 in Cash Smart Enhanced today is targeting roughly S$720 a year in net yield, accrued daily, with no lock-up and no funding limit beyond the S$1,000 minimum.
According to Endowus’s own Cash Smart page (figures dated 30 September 2026), the three portfolios break down as follows:
| Portfolio | Net Yield (p.a.) | Historical Max Loss | Underlying Holdings |
|---|---|---|---|
| Secure | 1.3% projected | -0.05% | 50% Fullerton SGD Cash Fund, 50% LionGlobal SGD Enhanced Liquidity |
| Enhanced | 2.4% projected | -1.55% | 50% UOB United SGD Fund, 30% LionGlobal SGD Enhanced Liquidity, 20% Fullerton SGD Cash Fund |
| Ultra | 2.8% projected | -2.88% | Diversified short-duration bond and money market funds |
Source: endowus.com/cash-smart, net yields as at 30 September 2026.
None of these yields are guaranteed — they move with the underlying funds’ performance, and each portfolio carries a different historical drawdown. Your assets are held in your own name at UOB Kay Hian, Endowus’s partner broker, rather than in a bank deposit account.
What GXS Savings Account Actually Pays
GXS splits your money across three buckets, each with its own rate. According to GXS’s official savings account page (checked November 2026), the baseline, non-promotional rates are:
| Bucket | Rate (p.a.) | Conditions |
|---|---|---|
| Main Account | 0.88% flat | None — instant access, interest credited daily |
| Saving Pocket | 1.2% (limited-time promo) | None — no lock-in, up to 8 pockets |
| Boost Pocket (12-month) | 0.88% base + 0.87% maturity bonus = 1.75% | Locked for the full 12 months to earn the bonus tranche |
Source: gxs.com.sg/savings-account, checked November 2026. Boost Pocket also offers 1, 3, 4, 8 and 18-month tenures with smaller or larger bonus tranches.
Every dollar in GXS is covered by the Singapore Deposit Insurance Corporation (SDIC) up to S$100,000 per depositor, because GXS is a MAS-licensed digital full bank, not an investment platform.
SDIC-Insured Bank Rate vs Projected Fund Yield
This is a different structural contrast from our Syfe Cash+ vs GXS Savings comparison, where both sides were investment-style cash products with varying guarantees. Here, GXS is a straightforward insured bank deposit at every tier, while Endowus Cash Smart is entirely fund-based — there is no insured tier at all, not even on Secure.
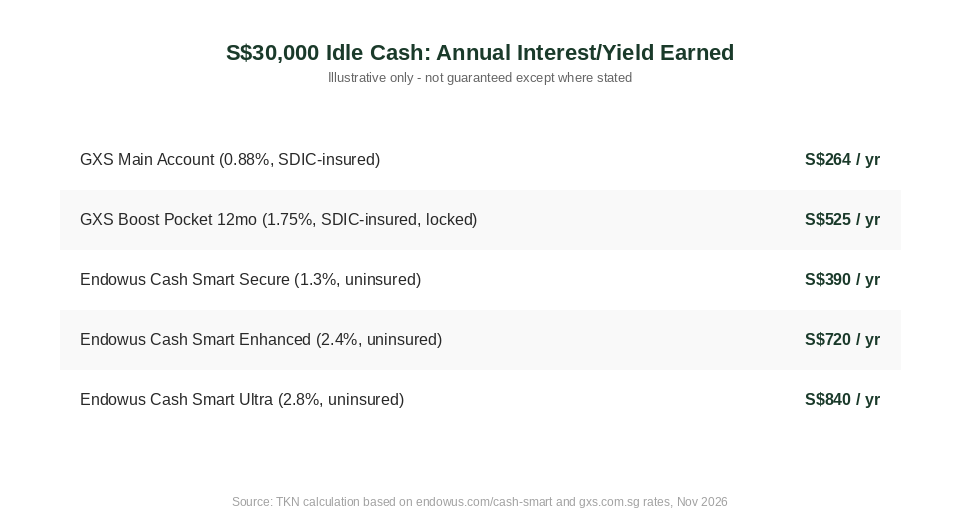
A Singapore investor with S$30,000 sitting idle earns roughly S$264 a year in GXS’s Main Account, or S$525 a year locking it into a 12-month Boost Pocket. The same S$30,000 in Endowus Cash Smart Enhanced targets roughly S$720 a year, and Ultra roughly S$840 a year — a gap of S$456 to S$576 a year for accepting fund-level risk and giving up SDIC protection entirely.
GXS’s rate is also contractually fixed once declared (subject to the bank changing published rates going forward), while every Endowus Cash Smart yield is a projection based on the trailing yield of the underlying funds and can move, including downward, month to month.
SRS Eligibility: The Real Differentiator
The feature that most comparisons skip is funding source. Endowus Cash Smart accepts both Cash and SRS money, so an investor who has topped up their Supplementary Retirement Scheme (SRS) account can park idle SRS cash in Cash Smart Secure or Enhanced while deciding on a longer-term fund, earning 1.3%–2.4% instead of letting it sit at the operator bank’s default SRS rate of around 0.05%.
GXS cannot take SRS money under any circumstance. SRS accounts in Singapore can only be opened with one of the three SRS operators — DBS, OCBC or UOB — and digital banks like GXS, MariBank and Trust Bank are structurally excluded from holding SRS funds at all, regardless of how competitive their savings rate is. For CPF money the picture is simpler still: neither platform takes it. Endowus Cash Smart is Cash and SRS only, and GXS does not support CPF or SRS funding in any form.
This matters for anyone comparing the two as a single pot of money. If part of your idle cash is actually SRS cash sitting at the bank’s default rate, GXS simply isn’t an option for it — Endowus Cash Smart (or another SRS-eligible cash product) is the only route to a better rate on that specific dollar.
Side-by-Side: Endowus Cash Smart vs GXS 2026
| Feature | Endowus Cash Smart | GXS Savings Account |
|---|---|---|
| Top net yield | 2.8% (Ultra, projected) | 1.75% (12-month Boost Pocket) |
| SDIC insured | No — held at UOB Kay Hian | Yes, up to S$100,000 |
| Funding sources accepted | Cash, SRS | Cash only |
| Minimum funding | S$1,000 | None |
| Lock-in required for top rate | No — Ultra has no lock-up | Yes — 12 months for the 1.75% Boost Pocket |
Source: endowus.com/cash-smart and gxs.com.sg/savings-account, November 2026.
Which Should You Pick?
A practical split for most Singapore savers in 2026:
| Money | Suggested Home |
|---|---|
| Core emergency fund, instant access | GXS Main Account or Saving Pocket (SDIC-insured, no lock-in) |
| Cash you can lock for 12 months | GXS Boost Pocket (1.75%, still SDIC-insured) |
| Idle SRS cash waiting to be invested | Endowus Cash Smart Secure or Enhanced (only SRS-eligible option of the two) |
| Cash with a 6–12 month horizon, risk-tolerant | Endowus Cash Smart Enhanced or Ultra (higher yield, accept fund risk) |
This mirrors the layered-cash logic in our GXS vs MariBank vs Trust Bank comparison and our Endowus Cash Smart vs MariBank comparison: keep the insured, instant-access layer at a digital bank, then route the remainder — including anything SRS-tagged — into a higher-yielding fund product. For the next step up the risk ladder, see passive income Singapore 2026 or, if the cash in question is CPF-related instead, CPF investment strategy.
How to Open an Account
Endowus: Sign up via Singpass MyInfo on the Endowus app or website (under 5 minutes), choose Secure, Enhanced or Ultra, and fund with S$1,000 minimum in Cash or SRS. Check the current sign-up offer on the Endowus referral code page.
GXS: Download the GXS app, verify via Singpass MyInfo, and open your Main Account instantly. Create Saving Pockets or Boost Pockets from there with no minimum deposit. Current referral bonuses are on the GXS Bank referral code page.
Frequently Asked Questions
Is Endowus Cash Smart better than GXS's savings account?
Can I put SRS money in GXS?
Is Endowus Cash Smart SDIC insured?
What is the minimum amount needed for Endowus Cash Smart or GXS?
Do I need to lock up my money to get the best rate on either platform?
Should I split my cash between Endowus Cash Smart and GXS?
Not financial advice. Endowus Cash Smart net yields are projected, not guaranteed, and can move with market conditions. GXS’s rates apply as checked in November 2026 and may change without notice, with Boost Pocket’s bonus tranche requiring the full lock-in tenure to be earned. Always verify current rates directly on endowus.com and gxs.com.sg before investing. The Kopi Notes may earn a referral fee if you sign up via links on this page.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.