Endowus Cash Smart vs MariBank 2026: Guaranteed 0.88% vs Projected Up to 2.8% — Which Wins?
MariBank pays a flat, SDIC-insured 0.88% with zero risk. Endowus Cash Smart projects up to 2.8% — but it’s a fund, not a deposit, and it isn’t guaranteed. Here’s the real trade-off.
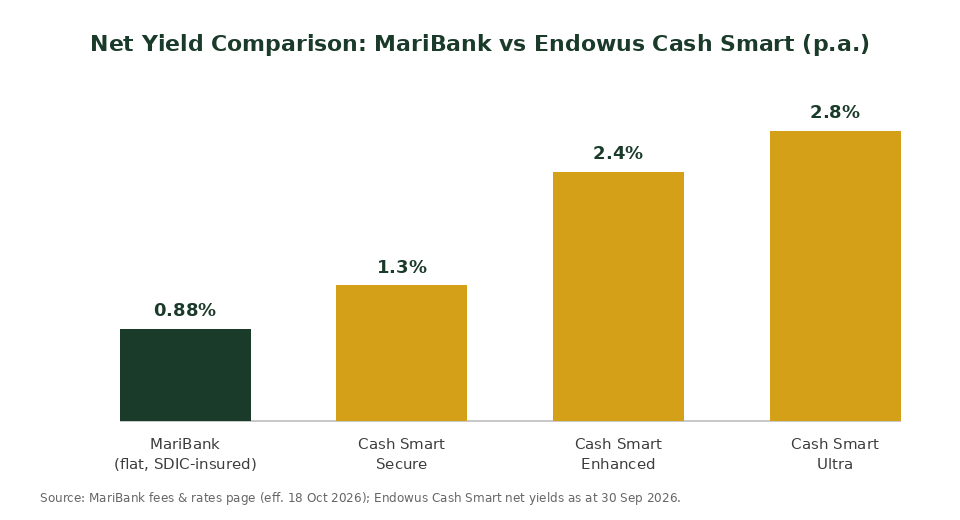
MariBank pays a flat 0.88% p.a. on SGD balances, SDIC-insured up to S$100,000, with zero conditions — while Endowus Cash Smart projects net yields of 1.3% (Secure), 2.4% (Enhanced) or 2.8% (Ultra) p.a. as at 30 Sep 2026, but these are unguaranteed money-market and bond fund returns, not a bank deposit, with historical drawdowns of up to -2.88% on the Ultra tier.
Not financial advice. All figures are for educational reference only. Data as at October 2026 unless noted.
- MariBank: flat 0.88% p.a. SGD savings deposit, SDIC-insured to S$100,000, no conditions — effective 18 Oct 2026 per MariBank’s own fees & rates page.
- Endowus Cash Smart: three fund portfolios — Secure (1.3%), Enhanced (2.4%), Ultra (2.8%) net yield p.a., as at 30 Sep 2026 per Endowus’s own Cash Smart page — none of it SDIC-insured or principal-guaranteed.
- The real question isn’t which rate is higher — it’s whether you want a guaranteed bank rate or a higher projected yield with fund-level market risk.
Table of Contents
Contents — Click to expand
The Rate Breakdown: Guaranteed vs Projected
On paper, Endowus Cash Smart’s Ultra tier at 2.8% p.a. looks like a clear winner over MariBank’s flat 0.88%. But that comparison only works if you ignore what each number actually represents: one is a bank’s contractual rate on a deposit, the other is a projected net yield on units in money-market and bond funds that can and do fluctuate.
| Metric | MariBank | Endowus Cash Smart |
|---|---|---|
| Rate type | Flat 0.88% p.a., bank-guaranteed | Projected net yield, 1.3%-2.8% p.a. |
| Minimum to start | S$0 | S$1,000 |
| Fees | None | 0.15% access fee (already netted into yield) |
| Capital protection | SDIC-insured up to S$100,000 | None — not principal-guaranteed |
| Data as at | 18 Oct 2026 | 30 Sep 2026 |
Source: MariBank fees & rates page (effective 18 Oct 2026); Endowus Cash Smart product page (yields as at 30 Sep 2026).
How MariBank’s Flat 0.88% Actually Works
MariBank’s Mari Savings Account pays a flat 0.88% p.a. on all SGD balances, effective 18 Oct 2026, per MariBank’s own fees-and-rates page. There is no salary credit requirement, no card spend quota, no balance tier, and no lock-up — every dollar earns the same rate from day one. MariBank also runs a 1.88% p.a. promotional rate on USD balances until 31 Dec 2026, though most Singapore savers are working in SGD.
MariBank is a full bank licensed by the Monetary Authority of Singapore and participates in the SDIC deposit insurance scheme, which insures deposits up to S$100,000 per depositor by law. Local transfers and fall-below fees are free, and overseas transfers are currently waived under an ongoing promotion through 31 Dec 2026.
How Endowus Cash Smart’s Up to 2.8% Actually Works
Endowus Cash Smart isn’t a savings account — it’s a managed portfolio of money market and short-duration bond unit trusts, held in your own name at UOB Kay Hian. There are three tiers, each with a different risk and return profile, per Endowus’s own Cash Smart page (net yields as at 30 Sep 2026):
| Portfolio | Net Yield p.a. | Historical Max Loss | Underlying Mix |
|---|---|---|---|
| Secure | 1.3% | -0.05% | 50% Fullerton SGD Cash Fund, 50% LionGlobal SGD Enhanced Liquidity |
| Enhanced | 2.4% | -1.55% | 50% UOB United SGD Fund, 30% LionGlobal Enhanced Liquidity, 20% Fullerton SGD Cash Fund |
| Ultra | 2.8% | -2.88% | Diversified short-duration bond and money market funds (6 funds) |
Source: endowus.com/cash-smart, net yields and historical max loss as at 30 Sep 2026.
Each net yield already deducts fund-level fees (after cashback) and Endowus’s own 0.15% access fee — there’s no separate charge on top. Cash Smart is available for Cash and SRS money (not CPF), with a S$1,000 minimum, daily interest accrual, and no lock-up period — you can withdraw at any time, though settlement typically takes a few business days rather than being instant.
The Real Difference: Deposit Protection vs Fund Risk
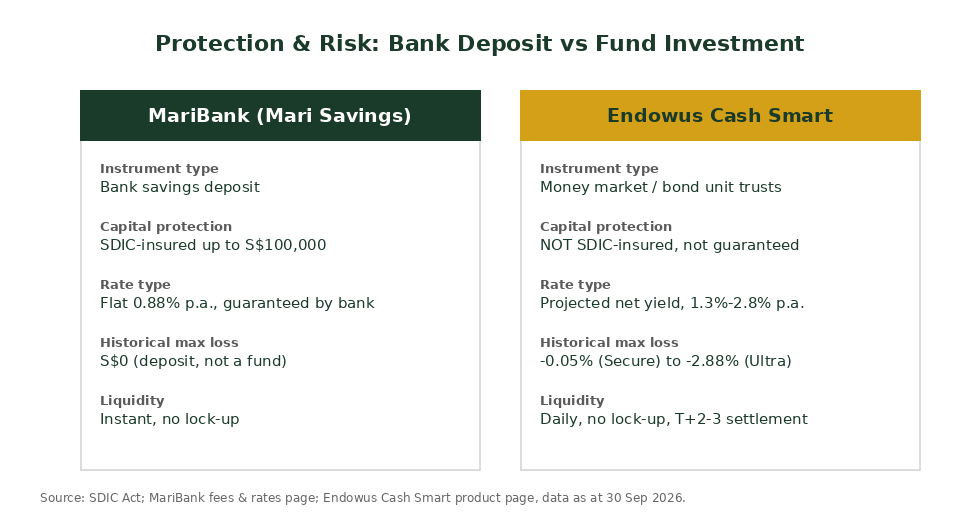
This is the part most rate-comparison tables skip entirely. MariBank’s 0.88% is a contractual bank liability — the bank owes you that interest, and SDIC insurance backs the principal up to S$100,000 if MariBank itself were to fail. Nothing about that 0.88% can go down because of market movements.
Endowus Cash Smart’s yields are not guaranteed. Your money buys units in money-market and bond funds, and the price of those units moves with interest rates and credit markets. Endowus itself discloses historical maximum drawdowns of -0.05% for Secure, -1.55% for Enhanced, and -2.88% for Ultra — meaning in a bad month, Ultra holders have seen their balance fall by close to 3%, erasing more than a year of projected yield in one stretch. Your Cash Smart holdings are also not SDIC-insured; they’re held in trust in your own name at UOB Kay Hian, which protects against Endowus or the broker failing, but doesn’t protect against the underlying funds losing value.
Which One Actually Wins For Your Cash
A Singapore saver parking S$20,000 in MariBank earns a guaranteed S$176 a year, with zero chance of that number falling. The same S$20,000 in Endowus Cash Smart Secure projects S$260 a year — a little more, with minimal historical drawdown (-0.05%) — making Secure the closest fund-based substitute for a savings account. Moving up to Enhanced projects S$480 a year, and Ultra projects S$560 a year, but both carry meaningfully larger historical swings (-1.55% and -2.88% respectively), which can briefly wipe out a year or more of extra yield.
For money you cannot afford to see dip even temporarily — an emergency fund, a home deposit due in weeks — MariBank’s guaranteed 0.88% is the safer home. For cash with a slightly longer runway (3–12 months) where you can tolerate a small, unlikely dip in exchange for a meaningfully higher projected yield, Cash Smart Secure or Enhanced make more sense. Ultra’s extra 0.4% over Enhanced rarely justifies its roughly double drawdown risk for most savers.
The Verdict: Who Should Pick Which
Pick MariBank if: you want a guaranteed, SDIC-insured rate with zero chance of your balance dipping — ideal for an emergency fund, a near-term expense, or anyone who wants cash management to be completely hands-off and risk-free.
Pick Endowus Cash Smart Secure if: you want a meaningfully higher projected yield than a savings account, can tolerate a near-negligible historical drawdown (-0.05%), and have at least S$1,000 to meet the minimum.
Pick Endowus Cash Smart Enhanced or Ultra if: your cash has a 6–12 month runway, you’re comfortable with fund-level market risk, and you want to maximise yield on money you won’t need at short notice.
Split your cash if you’re optimising: many Singapore savers keep a guaranteed MariBank float for true emergencies, then route surplus cash into Cash Smart Secure or Enhanced for everything else.
Ready to get started? Use the Endowus referral code (2V343) or the MariBank referral code (2DCT80WQ) for current sign-up terms, and see our Endowus income portfolio review for higher-yield options beyond Cash Smart. For deciding how much cash to keep liquid versus invest further, our passive income Singapore guide and retirement planning calculator can help.
Frequently Asked Questions
Is Endowus Cash Smart or MariBank better for idle cash in 2026?
It depends on your risk tolerance. MariBank’s flat 0.88% p.a. is a guaranteed, SDIC-insured bank rate with zero volatility. Endowus Cash Smart projects a higher net yield (1.3%-2.8% p.a. as at 30 Sep 2026), but it’s fund-based, not SDIC-insured, and has historically dipped by as much as -2.88% on its Ultra tier.
Is Endowus Cash Smart SDIC insured?
No. Cash Smart holdings are units in money-market and bond unit trusts held in your own name at UOB Kay Hian, not a bank deposit, so SDIC insurance does not apply. MariBank, as a licensed bank, is SDIC-insured up to S$100,000 per depositor.
What is MariBank’s current interest rate?
MariBank pays a flat 0.88% p.a. on SGD balances with no conditions, effective 18 Oct 2026, plus a 1.88% p.a. promotional rate on USD balances until 31 Dec 2026, per MariBank’s official fees and rates page.
What is the minimum amount to start Endowus Cash Smart?
Endowus requires a minimum initial investment of S$1,000 to open an account, which applies across its products including Cash Smart. MariBank has no minimum balance requirement.
Can Endowus Cash Smart lose money?
Yes. Cash Smart portfolios are not principal-guaranteed. Endowus discloses historical maximum drawdowns of -0.05% for Secure, -1.55% for Enhanced, and -2.88% for Ultra, meaning the fund value can fall, particularly for the higher-yield Enhanced and Ultra tiers during bond market volatility.
Can I use both MariBank and Endowus Cash Smart at the same time?
Yes. A common approach is keeping a guaranteed emergency fund in MariBank for instant, risk-free access, while routing longer-runway surplus cash into Endowus Cash Smart Secure or Enhanced for a higher projected yield.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.