MariBank vs Trust Bank 2026: Flat 0.88% vs Up to 2.40% — Which Digital Bank Wins?
MariBank’s flat 0.88% needs zero effort. Trust Bank’s 2.40% needs three monthly “scoops” — here’s which one actually pays more for your situation.
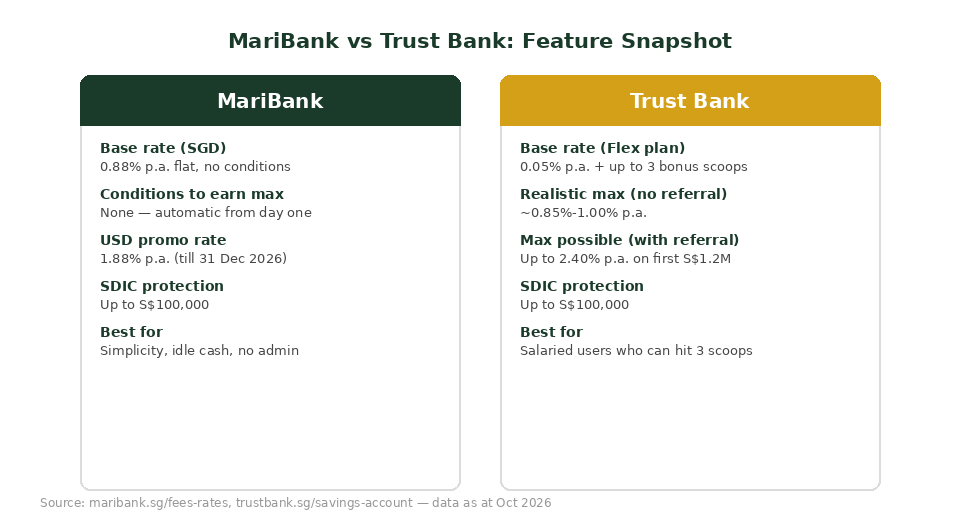
MariBank pays a flat 0.88% p.a. on all SGD balances with zero conditions, while Trust Bank’s Flex plan advertises up to 2.40% p.a. but requires hitting any 3 of 8 monthly “bonus scoops” (salary credit, card spend, PayNow, referrals, or a S$100K balance) — without a referral bonus, most users realistically earn only 0.85%–1.00% p.a. on Trust.
Not financial advice. All figures are for educational reference only. Data as at October 2026 unless noted.
- MariBank: flat 0.88% p.a. on SGD balances, no hoops, no tiers — effective 18 Oct 2026 per MariBank’s own fees & rates page.
- Trust Bank Flex plan: 0.05% base + up to 3 bonus “scoops” from a menu of 8, capping at 2.40% p.a. on the first S$1.2M — but the achievable rate for most ordinary salaried users without a credit card referral is closer to 0.85%–1.00% p.a.
- Both are SDIC-insured up to S$100,000 per depositor, so safety isn’t the differentiator — effort and predictability are.
Table of Contents
The Rate Breakdown: Flat vs Conditional
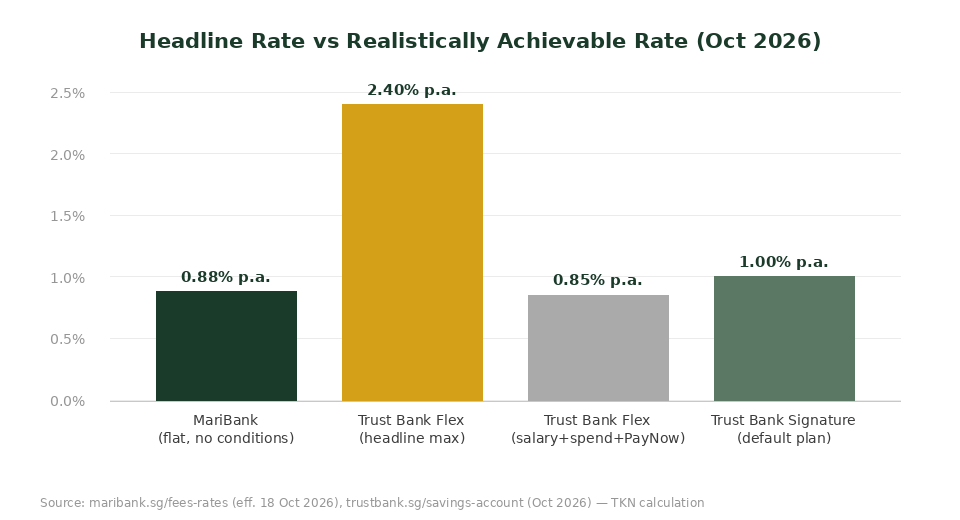
On paper, Trust Bank’s “up to 2.40% p.a.” headline beats MariBank’s flat 0.88% p.a. by a wide margin. But headline rates and realistic rates are two different numbers — and that gap is the entire story of this comparison.
| Metric | MariBank | Trust Bank (Flex) |
|---|---|---|
| Base rate | 0.88% p.a. | 0.05% p.a. |
| Conditions needed for max | None | Any 3 of 8 monthly “scoops” |
| Headline maximum | 0.88% p.a. | 2.40% p.a. (first S$1.2M) |
| Realistic max (no referral, no $100K ADB) | 0.88% p.a. | ~0.85%–1.00% p.a. |
| Effective date | 18 Oct 2026 | Oct 2026 |
Source: MariBank fees & rates page (effective 18 Oct 2026), Trust Bank savings account page (Oct 2026).
How MariBank’s 0.88% Actually Works
MariBank keeps its Mari Savings Account deliberately simple. According to MariBank’s own fees-and-rates page (effective 18 Oct 2026), the base rate on all SGD balances is a flat 0.88% p.a. — no salary credit requirement, no minimum card spend, no referral quota, no balance tier to unlock a “bonus” layer. Whatever you hold in the account earns the same rate from the first dollar.
There is one wrinkle worth knowing: MariBank also runs a 1.88% p.a. promotional rate on USD balances, valid until 31 Dec 2026, after which it reverts to the 0.88% base rate. For SGD-denominated savers — the vast majority of Singapore users — the number that matters day to day is the flat 0.88%.
MariBank local transfers, overseas transfers (under its current promotion, waived through 31 Dec 2026) and fall-below fees are all free, and the account is backed by MariBank Singapore Private Limited, which is licensed by MAS and participates in the SDIC deposit insurance scheme, insuring deposits up to S$100,000 per depositor.
How Trust Bank’s Up-to-2.40% Flex Plan Actually Works
Trust Bank now offers three savings plans you can switch between every month via the Trust app: Flex (up to 2.40% p.a.), Signature (up to 1.00% p.a., and the default if you never pick a plan) and Zen (a flat 0.40% p.a. with zero conditions, similar in spirit to MariBank’s model but at a lower rate).
The Flex plan starts at a 0.05% p.a. base rate, then lets you stack any 3 of 8 bonus “scoops” each month:
| Scoop | Condition | Bonus |
|---|---|---|
| Referral | Refer 1 new Trust credit card customer who gets approved | +1.20% |
| Invest | Buy S$20K of eligible TrustInvest funds | +0.70% |
| Salary | Credit min. S$1,500 monthly salary via GIRO | +0.45% |
| Balance (ADB) | Maintain min. S$100K Average Daily Balance | +0.30% |
| ADB increase | Grow ADB by S$3K from last month | +0.20% |
| Card spend | 5x S$30 card spends (NTUC Union member) | +0.20% |
| Card spend (non-Union) | 5x S$30 card spends | +0.10% |
| PayNow | Receive S$1,500 total incoming PayNow | +0.15% |
| FX spend | S$500 total foreign-currency card spend | +0.15% |
Source: trustbank.sg/savings-account, Oct 2026. Bonus rates apply for the full month once unlocked, on balances up to S$1.2M; 0.05% applies above that.
Notice the two biggest scoops — the +1.20% referral bonus and the +0.70% TrustInvest bonus — aren’t things an ordinary saver does every single month without effort. A realistic combination for most salaried users is Salary (+0.45%) + Card spend (+0.20% or +0.10%) + PayNow (+0.15%), which lands at roughly 0.05% + 0.45% + 0.20% + 0.15% = 0.85% p.a. — almost identical to MariBank’s flat rate, just with three boxes to tick every month.
Which One Actually Pays More For You
A Singapore saver holding S$20,000 in idle cash would earn S$176 a year on MariBank’s flat 0.88%, with zero admin. The same S$20,000 on Trust Bank’s Flex plan earns roughly S$170 a year if you only hit the salary, card-spend and PayNow scoops (0.85%) — effectively a wash, but with three monthly conditions to track. Only if you can genuinely stack the referral bonus (+1.20%) or route S$20K through TrustInvest (+0.70%) does Trust Bank pull meaningfully ahead, pushing the blended rate toward 1.5%–2.4% depending on which scoops you combine.
The practical takeaway: Trust Bank’s advantage only shows up once you’re already an active Trust ecosystem user — salaried, card-spending, and ideally bringing in a referral or TrustInvest purchase each month. If your cash just needs somewhere flat and predictable to sit, the gap narrows to a rounding error, and MariBank wins on simplicity alone.
Safety, Fees & SDIC Protection
Both banks are equally safe from a deposit-protection standpoint: MariBank Singapore Private Limited and Trust Bank Singapore Limited are both full banks licensed by the Monetary Authority of Singapore and both participate in the SDIC scheme, insuring up to S$100,000 per depositor per bank. Trust Bank is a joint venture between Standard Chartered and FairPrice Group; MariBank is backed by Sea Limited (Shopee’s parent company).
On fees: MariBank’s local transfers and fall-below fees are free, with overseas transfers currently waived under an ongoing promotion through 31 Dec 2026. Trust Bank’s savings account is also fee-less — no monthly fee, no minimum balance requirement, no account closure fee — regardless of which of the three plans (Flex, Signature, Zen) you choose.
The Verdict: Who Should Pick Which
Pick MariBank if: you want a flat, predictable rate with zero monthly admin — ideal for an emergency fund, a parking spot for idle cash, or anyone who doesn’t want to track bonus conditions every month.
Pick Trust Bank if: you already credit your salary somewhere flexible, spend on a card regularly, receive PayNow transfers, and especially if you can realistically refer a friend to a Trust credit card or route a lump sum through TrustInvest — in which case the Flex plan can meaningfully beat MariBank.
Pick neither exclusively if you’re optimising hard: many Singapore savers split cash between MariBank (the no-effort floor) and Trust Bank Flex (stacking only the free, low-effort scoops like salary credit and PayNow), capturing most of the upside without chasing the harder-to-hit referral bonus every month.
Ready to open an account? Use the MariBank referral code (2DCT80WQ) or the Trust Bank referral code (HTWYQP95) for current sign-up bonuses, and see our full MariBank review for a deeper look at its credit card and Mari Invest products. For routing idle cash beyond these two banks, our passive income Singapore guide and retirement planning calculator can help you decide how much should stay in cash versus move into S-REITs or CPF.
Frequently Asked Questions
Is MariBank or Trust Bank better for a Singapore investor in 2026?
It depends on effort tolerance. MariBank’s flat 0.88% p.a. needs no conditions, while Trust Bank’s Flex plan can hit 2.40% p.a. but only if you stack 3 of 8 monthly bonus scoops — without a referral or large TrustInvest purchase, Trust Bank’s realistic rate (roughly 0.85%–1.00%) is close to MariBank’s flat rate.
What is MariBank's current interest rate?
MariBank pays a flat 0.88% p.a. on SGD balances with no conditions, effective 18 Oct 2026, plus a 1.88% p.a. promotional rate on USD balances until 31 Dec 2026, per MariBank’s official fees and rates page.
How do I actually earn Trust Bank's 2.40% interest rate?
You need the Flex plan and must hit any 3 of 8 monthly bonus conditions: salary credit, card spend, PayNow transfers, TrustInvest purchases, referrals, or maintaining a S$100,000 Average Daily Balance. The two highest-value scoops (referral +1.20% and TrustInvest +0.70%) require active effort each month, not passive holding.
Are MariBank and Trust Bank both SDIC insured?
Yes. Both are full banks licensed by MAS and participate in the SDIC scheme, which insures Singapore dollar deposits up to S$100,000 per depositor per bank by law.
Can I use both MariBank and Trust Bank at the same time?
Yes, and many Singapore savers do. A common approach is parking a baseline emergency fund in MariBank for its no-effort flat rate, while using Trust Bank’s Flex plan for salary-linked cash where the low-effort scoops (salary credit, PayNow) are easy to hit anyway.
Does Trust Bank's Signature or Zen plan beat MariBank?
Trust Bank’s Signature plan (up to 1.00% p.a., the default if you don’t actively choose Flex) can slightly beat MariBank’s 0.88% if you credit salary and spend on your card, but its Zen plan (flat 0.40% p.a., no conditions) pays less than half of MariBank’s flat rate, making MariBank the better no-effort option of the three.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.