- Sell the years of your HDB lease you are unlikely to need — HDB buys them back at market value.
- You continue living in your flat. The proceeds top up your CPF Retirement Account, boosting your CPF LIFE monthly payouts for life.
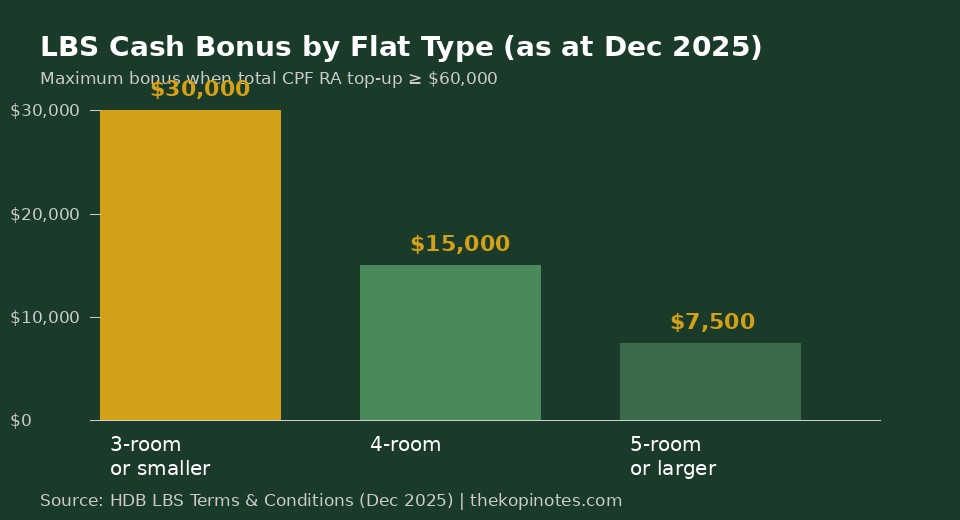
- Cash bonus: up to $30,000 for 3-room or smaller flats; $15,000 for 4-room; $7,500 for 5-room or larger (as at Dec 2025).
- Eligibility: all owners aged 65+, at least one Singapore Citizen, gross household income ≤ $14,000/month, no private property.
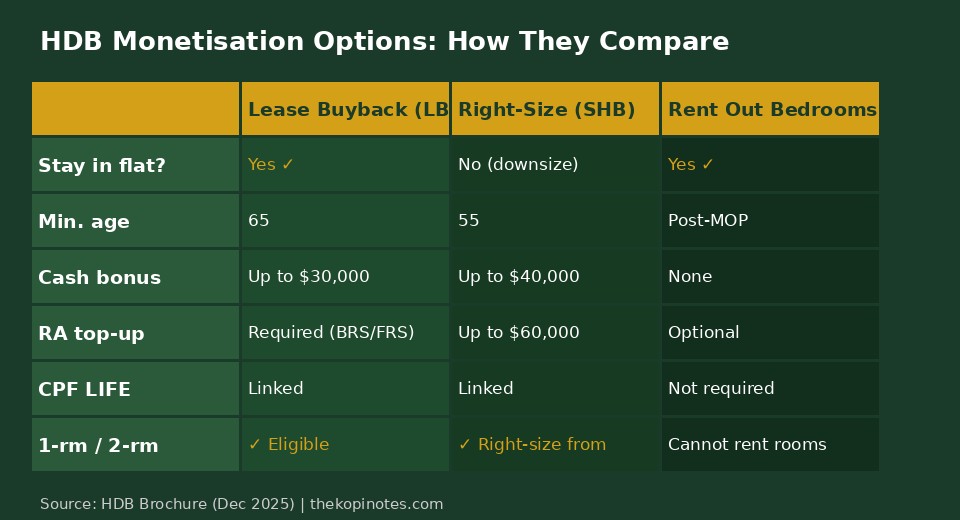
- The LBS is one of three HDB monetisation routes. Right-sizing (Silver Housing Bonus, up to $40,000) and renting out spare bedrooms are the alternatives — each suits a different situation.
What Is the HDB Lease Buyback Scheme?
For most Singaporeans, the HDB flat is the single largest asset they own — and it is locked up in bricks and mortar until death or sale. The HDB Lease Buyback Scheme (LBS) is designed to change that. It lets you sell the tail-end of your flat’s 99-year lease back to HDB while you carry on living in the same home.
Think of it this way. If you are 67 today and your flat has 55 years of lease remaining, you realistically need the flat to cover you until age 95 — that is 28 years. The remaining 27 years of lease are years you are statistically unlikely to use. The LBS lets you sell those surplus years to HDB at market value. The money goes into your CPF Retirement Account (RA) and funds a lifetime income through CPF LIFE.
The scheme has been progressively expanded since it was introduced in 2009. It now covers all flat types — from 2-room flexi up to executive flats — and the cash bonus has been enhanced multiple times. The latest terms took effect in December 2025.
Am I Eligible? The 2026 Checklist
You must meet all of the following criteria to apply for the LBS (as at Dec 2025):
| Criterion | Requirement |
|---|---|
| Age | All flat owners must be aged 65 or above |
| Citizenship | At least one owner must be a Singapore Citizen |
| Gross monthly household income | Must not exceed $14,000/month |
| Other property | Must not own private residential property or more than one non-residential property |
| Minimum occupation period | MOP for your flat must be fulfilled |
| Lease available to sell | At least 20 years of lease remaining after you retain enough for the youngest owner to reach age 95 |
| Spouse consent | Non-owner spouse must consent in writing |
Quick age check: If the youngest owner is 67, retaining 28 years covers them to age 95. That leaves 55 − 28 = 27 years available to sell — well above the 20-year minimum (assuming the flat has 55 years remaining).
How the HDB Lease Buyback Scheme Works: Step by Step
Step 1 — Decide how much lease to retain
The lease you keep must, at minimum, cover the youngest owner to age 95. Your options for the retention period depend on that youngest owner’s age:
| Youngest owner’s age | Lease retention options |
|---|---|
| 65 – 69 | 30 or 35 years |
| 70 – 74 | 25, 30, or 35 years |
| 75 – 79 | 20, 25, 30, or 35 years |
| 80 and above | 20, 25, 30, or 35 years |
Retaining a shorter lease means selling more years to HDB — and receiving higher proceeds. The trade-off is that a shorter retained lease depresses your flat’s resale value if you later want to sell.
Step 2 — HDB buys the tail-end lease
HDB values the sold portion of the lease at its market rate (based on SLA’s assessed value), then deducts outstanding mortgage or CPF housing refund obligations. What remains is your net LBS proceeds.
Step 3 — Top up your CPF Retirement Account
Your net proceeds are used to top up your RA to the required Retirement Sum level:
| Owner type | Age 65–69 | Age 70–79 | Age 80+ |
|---|---|---|---|
| Sole owner (top up to FRS) | $220,400 | $210,400 | $200,400 |
| Two or more owners (each to BRS) | $110,200 each | $105,200 each | $100,200 each |
Source: HDB LBS Terms and Conditions (December 2025). Figures valid for applications from 1 January to 31 December 2026.
If your net proceeds exceed the top-up requirement and combined household proceeds are above $100,000, the surplus first goes toward topping up RA balances to the Full Retirement Sum before any cash is paid out to you. The absolute cash cap per household is $100,000 per transaction.
Step 4 — Receive the LBS bonus (and keep the cash remainder)
Once the RA top-up is done, HDB pays out the LBS cash bonus and any remaining proceeds as cash. The bonus depends on your flat type and the size of your RA top-up — explained in the next section.
Step 5 — Join CPF LIFE (if not already on it)
If your RA holds at least $60,000 after the top-up and you are below age 80, you must join CPF LIFE. Your RA savings are then converted into a lifelong monthly income that pays out from age 65. Owners aged 80 and above receive payouts under the older Retirement Sum Scheme instead.
The LBS Cash Bonus: How Much Will You Get?
The LBS bonus rewards you for topping up your RA. The maximum bonus is paid if the combined RA top-up across all owners reaches at least $60,000:
| Flat type | Maximum LBS bonus | Pro-rated rate (if top-up < $60,000) |
|---|---|---|
| 3-room or smaller | $30,000 | $1 for every $2 topped up |
| 4-room | $15,000 | $1 for every $4 topped up |
| 5-room or larger | $7,500 | $1 for every $8 topped up |
Source: HDB LBS Terms and Conditions (December 2025). The LBS bonus can be enjoyed by each household only once.
Worked Example: Mr and Mrs Tan, Age 67 (4-Room Flat)
This is an illustrative example. Actual proceeds depend on HDB’s valuation of the flat and the specific terms at the time of application.
| Assumptions | |
| Both owners | Age 67, Singapore Citizens, joint tenants |
| Flat type | 4-room HDB, market value ~$480,000 |
| Lease remaining | 55 years |
| Lease to retain | 30 years (covers both owners to age 97) |
| Lease sold to HDB | 25 years |
| Net LBS proceeds (illustrative) | $200,000 |
| Existing RA balance each | $60,000 |
| How the $200,000 is distributed | |
| Each owner’s share (50/50) | $100,000 |
| RA top-up target (2026, age 67, 2+ owners = BRS) | $110,200 per owner |
| Shortfall from existing $60,000 to BRS | $50,200 per owner |
| RA top-up (both owners combined) | $50,200 × 2 = $100,400 |
| Proceeds left as cash (both) | $49,800 × 2 = $99,600 |
| Combined RA top-up ≥ $60,000? | Yes ($100,400) → full 4-room LBS bonus |
| LBS cash bonus | $15,000 |
| Total cash to household | $99,600 + $15,000 = $114,600 |
CPF LIFE outcome: Each owner’s RA is now $110,200 (the 2026 BRS). Under the CPF LIFE Standard Plan, a BRS balance at age 65 generates approximately $770–$830 per month for life (estimate; check the CPF LIFE estimator for your exact situation). Combined, Mr and Mrs Tan would receive an estimated $1,540–$1,660 per month in lifelong CPF LIFE payouts — as a guaranteed income floor — while retaining their flat.
LBS vs Right-Sizing (Silver Housing Bonus) vs Renting Out
Your HDB flat gives you three main monetisation routes. Which one is right depends on whether you want to stay, move, or simply generate rental income.
| Feature | LBS (Lease Buyback) | Right-Size (SHB) | Rent Out Bedrooms |
|---|---|---|---|
| Stay in flat? | ✓ Yes | No — must downsize to 3-room or smaller | ✓ Yes (if renting out bedrooms) |
| Minimum age | 65 (all owners) | 55 (at least 1 SC owner) | Post-MOP (no age floor) |
| Income ceiling | ≤ $14,000/month | ≤ $14,000/month | None |
| Cash bonus | Up to $30,000 (3-rm or smaller) | Up to $40,000 (to 2-rm or smaller) | None — rental income only |
| CPF RA top-up | Required (to BRS or FRS) | Up to $60,000 committed to RA | Optional — income is separate |
| CPF LIFE linkage | Mandatory if RA ≥ $60,000 and age < 80 | Yes — join CPF LIFE | Not required |
| 1-room/2-room flat | ✓ Eligible (highest bonus) | ✓ Right-size from any flat | Cannot rent out bedrooms; can rent whole flat |
| Best for | Staying put; converting illiquid flat equity into CPF LIFE income | Willingness to move to a smaller flat for a larger cash bonus | Generating monthly cash flow while retaining full flat value |
Silver Housing Bonus (SHB) note: The SHB pays up to $30,000 for right-sizing to a 3-room flat, or up to $40,000 for a 2-room or smaller flat (for HDB sellers or private property with AV ≤ $21,000). It has a lower age floor (55) and a larger maximum bonus — but you must move. Committed RA top-up can now come entirely from CPF housing refunds, so no cash top-up is required.
The CPF LIFE Connection: Turning Your Flat into Lifelong Income
The LBS is fundamentally a CPF LIFE top-up mechanism with housing as the funding source. Understanding how CPF LIFE converts your RA into monthly payouts is key to evaluating whether LBS makes sense for you.
When your RA balance reaches the Basic Retirement Sum (BRS, $110,200 in 2026), CPF LIFE Standard Plan at age 65 generates approximately $770–$830 per month for life. The exact figure depends on your birth year and the plan you choose. Top up to the Full Retirement Sum ($220,400) and those payouts roughly double.
For a couple where both own the flat, the LBS unlocks two streams of lifelong income — one for each owner — even if the flat’s market value would have generated only a one-time sale gain.
The power of LBS is the combination: a lump-sum cash payout today (proceeds + bonus) plus a permanent increase in your monthly income floor from CPF LIFE. Many retirees use the cash payout for one-off needs (medical, renovation, helping adult children) while the higher CPF LIFE payout covers recurring monthly expenses.
To see how your CPF LIFE payout would change with a higher RA balance after LBS, use the TKN Retirement Planning Calculator.
Key Trade-offs and What to Watch
Your flat’s resale value may fall
Retaining only 30 years of lease materially reduces your flat’s resale value if you later decide to sell. A flat with 30 years remaining is worth significantly less than one with 55 or 65 years. Once you sell the tail end to HDB, you cannot buy it back.
The LBS bonus is a one-time benefit
The cash bonus can only be enjoyed by each household once. If you apply now but proceed only with the minimum top-up, you cannot top up further later to receive a larger bonus.
CPF LIFE payouts only start from age 65
If you apply for the LBS at 67, the RA top-up improves your CPF LIFE payout going forward. If you deferred CPF LIFE, the enhanced payout begins immediately. If you have not yet reached 65, check the CPF LIFE deferral bonus rules — each year you defer increases your payout.
What happens to CPF RA withdrawals?
Once the LBS proceeds go into your RA, you cannot withdraw them as a lump sum (unlike your CPF Ordinary and Special Account balances at age 55). The RA is designed to generate retirement income, not lump-sum access.
Income ceiling matters for lower-income seniors
The $14,000 monthly household income ceiling is high enough that most seniors will qualify. But if one owner is still working at a senior wage — say, as a professional earning above that threshold — check whether household income is calculated pre- or post-CPF contributions.
Is the LBS Right for You? A Decision Guide
LBS is likely the better fit if:
- You want to stay in your current flat (community, proximity to family, no disruption)
- You own a 3-room or smaller flat — the $30,000 bonus is proportionally large relative to the flat’s value
- You have a low CPF RA balance and need to top it up to qualify for meaningful CPF LIFE payouts
- Your flat has sufficient lease remaining to sell at least 20 years after retaining cover to age 95
- You want a lump-sum cash injection now plus a permanent increase in monthly income
Consider right-sizing (SHB) instead if:
- You are open to moving to a smaller flat (3-room or 2-room) — the Silver Housing Bonus can reach $40,000
- You are 55–64 (below the LBS age floor) and want to start unlocking your flat’s value sooner
- Your flat has limited lease left to sell, making LBS proceeds small
- Lower maintenance and utility costs at a smaller flat meaningfully reduce your monthly expenditure
Consider renting out bedrooms instead if:
- You want to preserve your flat’s full value (and future resale potential)
- You are comfortable sharing your home with tenants
- You prefer monthly rental income over a one-time CPF RA top-up
- You own a 3-room or larger flat (required to rent out bedrooms)
For a broader view of how housing fits into your overall retirement number, see the FIRE Singapore: The Number guide, which frames CPF LIFE, HDB, and cost-of-living in a single Singapore-specific picture.
How to Apply for the LBS
The LBS application is managed by HDB. Here is the process:
- Check eligibility — Use HDB’s e-service at go.gov.sg/hdb-hmoptions to see which monetisation options you qualify for.
- Submit an online application — Log in with your Singpass at hdb.gov.sg to submit an Intent to Apply.
- Valuation and proceeds calculation — HDB arranges for the flat to be valued. You will receive an indicative net proceeds figure.
- Appointment at HDB Branch — All owners (and the consenting non-owner spouse, if any) must attend in person. Witnesses (Singapore Citizen or PR children or relatives aged 21+, or two friends/grassroots leaders) are required.
- Completion — HDB transfers the tail-end lease. Proceeds flow to CPF RA within the completion timeframe, and any cash amount is paid by cheque.
HDB’s Branch Service Line is 6225-5432 (weekdays, 8:00am to 5:00pm) for queries.
Related Tools and Guides
- Retirement Planning Calculator Singapore — Model your CPF LIFE income, SRS, and total retirement number
- CPF Retirement Sum 2026 Guide — BRS, FRS and ERS explained; what your RA needs to reach
- CPF Withdrawal at 55 — What you can take out and what stays in your RA
- CPF Top-Up Guide — SA, RA and MediSave top-ups for tax relief and retirement
- Silver Support Scheme — Quarterly payouts for lower-income seniors
- LBS Glossary Entry — Quick reference definition and key terms
Frequently Asked Questions
Can I apply for the LBS if one owner is a Permanent Resident (PR) and not a Singapore Citizen?
What happens if my CPF RA already meets the BRS or FRS? Can I still apply?
Is the LBS bonus taxable? Does it affect my SRS or income tax?
Can I rent out rooms in my HDB flat after doing the LBS?
What if my flat has very little lease left — say, under 40 years remaining?
How does the LBS interact with the Majulah Package and Silver Support Scheme?
Can I reverse or undo the LBS after the lease is sold?
Does applying for the LBS affect my eligibility to buy a new flat or private property later?
No financial advice: This article is for informational purposes only and does not constitute financial, investment, legal, or tax advice. Figures are based on publicly available official sources (HDB, CPF Board) as at December 2025 and are subject to change. Always verify the latest terms directly with HDB (hdb.gov.sg) and CPF Board (cpf.gov.sg) before making any decisions. Individual outcomes from the Lease Buyback Scheme depend on your specific flat valuation, CPF balances, age, and prevailing Retirement Sum levels at the time of application. Consider speaking with a licensed financial adviser for advice tailored to your personal situation.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.