OCBC Endowment Plan Singapore 2026: Complete Guide to All Plans & Rates
OCBC Bank distributes three endowment insurance plans underwritten by Great Eastern Life Assurance Company Limited — an OCBC Group subsidiary and one of Singapore’s oldest life insurers. Whether you want a short 2-year guaranteed return, a long-term participating plan, or a structured bonus payout, OCBC offers options to match. This guide covers every plan with verified rates, capital guarantee timelines, and SRS eligibility, so you can compare before you commit.
Table of Contents
Jump to Section
2. GREAT SP (24-Month) — Guaranteed Plan
3. GREATLife Endowment Insurance 3 — Long-Term Participating Plan
4. PrimeGold Bonus III — Structured Bonus Plan
5. Plans Comparison Table
6. Which OCBC Endowment Plan Is Right for You?
7. Key Risks to Know
8. OCBC Endowment vs Other Banks
9. Frequently Asked Questions
Overview of OCBC Endowment Plans
OCBC distributes endowment plans through its bancassurance partnership with Great Eastern Life. All plans are protected under the Policy Owners’ Protection Scheme (PPF Scheme) administered by SDIC, covering up to S$500,000 of guaranteed benefits per life assured per insurer.
Three plans are currently available (as at Sep 2026):
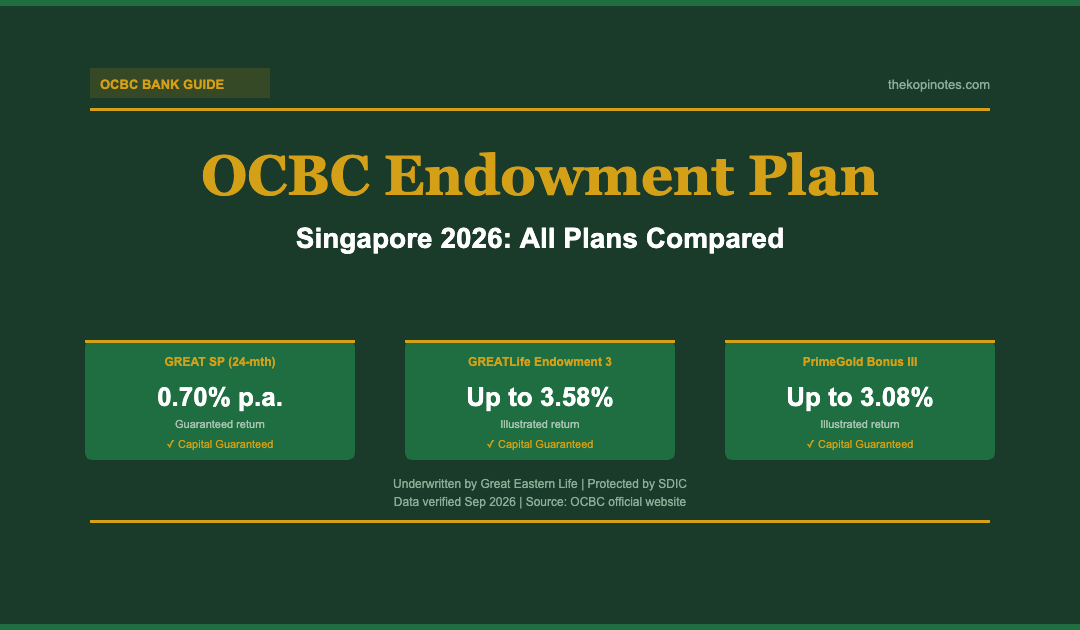
- GREAT SP (24 months) — Short-term, 100% guaranteed, fixed 0.70% p.a.
- GREATLife Endowment Insurance 3 — Long-term participating endowment with illustrated returns up to 3.58% p.a.
- PrimeGold Bonus III — Single-premium participating plan with structured bonus payouts up to 3.08% p.a. illustrated.
None of these plans require medical underwriting — you do not need to answer health questions or take a medical exam to apply. This makes them accessible even to those who might struggle with fully underwritten life insurance policies. To understand the basics of how endowment policies work, see our guide to endowment plan meaning in Singapore.
GREAT SP (24-Month) — Guaranteed Short-Term Plan
The GREAT SP is OCBC’s shortest endowment option. It runs for exactly 24 months and delivers a 100% guaranteed return of 0.70% p.a. — no non-guaranteed bonuses, no par fund dependency. Every cent is locked in from day one.
Key Features
- Policy term: 24 months
- Premium payment: Single premium (lump sum at entry)
- Guaranteed return: 0.70% p.a.
- Capital guarantee: 100% on maturity
- SRS eligible: Yes — minimum S$15,000 for SRS single premium
- Medical underwriting: None required
The 0.70% p.a. guaranteed rate is modest compared to fixed deposits, but the GREAT SP has one advantage: SRS eligibility. Topping up your Supplementary Retirement Scheme (SRS) account and placing funds here provides a tax deduction on the top-up amount. For a 40-year-old in the 15% marginal tax bracket, topping up S$15,300 (the 2026 SRS cap for Singapore Citizens) saves S$2,295 in income tax — effectively boosting the total return significantly beyond the stated 0.70% p.a.
The downside is liquidity: surrendering early will result in a loss of the guaranteed return and possibly a portion of capital depending on surrender terms. Treat this as money you will not need for two years.
GREATLife Endowment Insurance 3 — Long-Term Participating Plan
The GREATLife Endowment Insurance 3 is a participating endowment policy aimed at long-term wealth accumulation. Returns are partly guaranteed and partly dependent on how well Great Eastern’s participating fund performs. Illustrated returns assume specific par fund crediting rates set by MAS guidance — they are not guaranteed.
Illustrated Returns (at 4.25% par fund, age 25, 10-year premium, retire at 65)
- Illustrated total return: Up to 3.58% p.a.
- At 3.00% par fund: 2.30% p.a. illustrated
Premium Terms
- Single premium, or regular premiums over 5, 10, or 15 years
- No medical underwriting required
- Minimum S$15,000 for SRS single premium
Capital Guarantee Timeline
- Single premium: Capital guaranteed from Year 10
- 5-year or 10-year premium: Capital guaranteed from Year 15
- 15-year premium: Capital guaranteed from Year 20
Entry Age Limits
- Single / 5-year / 10-year premium: Maximum entry age 70
- 15-year premium: Maximum entry age 65
The illustrated 3.58% p.a. figure assumes the par fund consistently credits 4.25% p.a. over the full policy term — this is the upper illustration required by MAS. Actual returns depend on investment performance and bonuses declared. The 2.30% p.a. lower illustration (3.00% par fund) is a more conservative scenario. Most long-term participating policies in Singapore have historically delivered returns between these two figures, but past performance is not a guarantee. For comparison with alternatives, see our analysis of endowment plans vs savings plans in Singapore.
PrimeGold Bonus III — Structured Bonus Plan
PrimeGold Bonus III is a single-premium participating endowment plan with structured payouts — the insurer declares and distributes bonuses at fixed intervals rather than accumulating all value to maturity. This suits investors who want periodic income from their endowment rather than a single payout at the end.
Illustrated Returns
- At 4.25% par fund: Up to 3.08% p.a. illustrated
- At 3.00% par fund: 1.91% p.a. illustrated
Policy Terms and Plan Types
- Policy terms: 15 years or 20 years
- Plan types (by payout structure): 4 variants — payouts from Year 6–15, Year 1–20, Year 4–20, or Year 6–20
- All are single-premium only
Capital Guarantee
- Capital guaranteed from Year 5 — earlier than GREATLife Endowment 3’s single-premium variant
SRS Eligibility and Entry Age
- SRS eligible: Yes
- Maximum entry age: 70 (15-year policy), 65 (20-year policy)
PrimeGold Bonus III’s capital guarantee from Year 5 is a meaningful difference from GREATLife Endowment 3 (which guarantees capital from Year 10 on single premium). If you want your capital protected sooner, PrimeGold Bonus III has the edge. However, the illustrated return ceiling of 3.08% p.a. is lower than GREATLife’s 3.58% p.a. — the trade-off for earlier capital protection and periodic payouts. For those comparing this against other bank endowment options, see our breakdowns of UOB endowment plans, NTUC Income endowment plans, and Etiqa endowment plans.
OCBC Endowment Plans: Side-by-Side Comparison
| Feature | GREAT SP | GREATLife Endow. 3 | PrimeGold Bonus III |
|---|---|---|---|
| Policy Term | 24 months | Long-term (varies) | 15 or 20 years |
| Premium Payment | Single | Single / 5 / 10 / 15 yrs | Single |
| Guaranteed Return | 0.70% p.a. | Partially guaranteed | Partially guaranteed |
| Max Illustrated Return | 0.70% p.a. | 3.58% p.a. | 3.08% p.a. |
| Capital Guaranteed From | Maturity (Year 2) | Year 10–20 (by term) | Year 5 |
| SRS Eligible | ✓ Yes | ✓ Yes | ✓ Yes |
| Medical Underwriting | None | None | None |
| Underwriter | Great Eastern Life | Great Eastern Life | Great Eastern Life |
| SDIC Protected | ✓ Yes | ✓ Yes | ✓ Yes |
Source: OCBC official website, as at Aug 2026. Illustrated returns at 4.25% par fund (upper MAS scenario). Not financial advice.
Which OCBC Endowment Plan Is Right for You?
The right plan depends on your time horizon, need for guarantees, and whether you’re parking SRS funds.
Choose GREAT SP if: You have a 2-year horizon, want 100% certainty on your return, and/or are placing SRS funds for a short lock-up. The guarantee removes any par fund risk — what you see is what you get.
Choose GREATLife Endowment Insurance 3 if: You’re planning for long-term goals (retirement, education) and are comfortable with the non-guaranteed portion. The regular-premium option (5/10/15 years) suits those who want to commit smaller amounts monthly rather than a single lump sum. The higher illustrated ceiling of 3.58% p.a. rewards patience.
Choose PrimeGold Bonus III if: You have a lump sum to deploy, want periodic bonus payouts rather than a single terminal payout, and prefer earlier capital protection (from Year 5). It suits retirees or near-retirees who want some income along the way rather than waiting until policy maturity. For more context on how endowment plans compare against direct equity, see our piece on endowment plans vs dividend stocks in Singapore.
Key Risks to Know
Non-guaranteed returns: For GREATLife Endowment Insurance 3 and PrimeGold Bonus III, only part of the maturity benefit is guaranteed. The non-guaranteed portion (reversionary bonuses and terminal bonus) depends on Great Eastern Life’s par fund performance. If the par fund underperforms, you will receive less than the upper illustrated figure — potentially closer to or below the lower illustrated figure of 2.30% or 1.91% p.a. respectively.
Illiquidity: Endowment plans are not meant to be surrendered early. If you need the money before maturity, the surrender value — especially in the early years — may be significantly less than your total premiums paid. Capital guarantee only kicks in after the specified year (Year 5 for PrimeGold Bonus III; Year 10 or later for GREATLife Endowment 3 single premium).
Inflation risk: A 3% illustrated return over 15–20 years may barely keep pace with inflation in a high-rate environment. Endowment plans are capital preservation instruments, not aggressive growth vehicles.
Par fund declaration risk: Great Eastern Life declares bonuses annually at its discretion. Declared reversionary bonuses are guaranteed once added, but the terminal bonus is not guaranteed until the policy matures or a claim is made. Both illustrated scenarios (3.00% and 4.25% par fund) are projections, not promises. Compare this to alternatives with our guide on Singapore SRS savings plans.
OCBC Endowment vs Other Banks
OCBC’s endowment lineup is distributed exclusively through Great Eastern Life — its affiliated insurer. This differs from banks like UOB (which also uses Great Eastern) and DBS (which uses Manulife). Etiqa and NTUC Income offer their own plans through direct and bank channels.
In terms of short-term guaranteed options, OCBC’s GREAT SP at 0.70% p.a. for 24 months is competitive but not always the highest available. Short-term endowment rates fluctuate with SORA and overall interest rate conditions — check live offers at the time of application. For long-term participating plans, Great Eastern Life’s par fund track record is relevant context that OCBC should provide on request.
If you’re shopping across banks, the key variables to compare are: guaranteed vs non-guaranteed split, capital guarantee start year, SRS eligibility, and actual surrender value tables for your intended holding period. Our guides to UOB endowment plans and Etiqa endowment plans provide the same breakdown format for easy cross-comparison. Also consider whether an Investment-Linked Policy (ILP) or BTIR strategy better suits your risk appetite.
Frequently Asked Questions
Is the OCBC GREAT SP 100% capital guaranteed?
Can I use SRS funds to buy OCBC endowment plans?
”Who
”Do
”When
Get Free Insurance Advice
Speak with a licensed insurance advisor. No obligation, no cost.
By submitting this form, you agree to our Privacy Policy.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.