Frasers Centrepoint Trust Share Price 2026: Q4 Rate-Cut DPU Recovery & Suburban Retail Outlook (SGX: J69U)
How falling rates in Q4 2026 support FCT distribution recovery — gearing headroom after White Sands, DPU trajectory, and what income investors need to watch.
Frasers Centrepoint Trust (FCT, SGX: J69U) is Singapore’s largest pure-play suburban retail REIT, owning nine malls including Causeway Point, Northpoint City North Wing, and Waterway Point. After the S$467 million White Sands disposal in 3QFY2026, gearing dropped to approximately 34.5%, giving FCT meaningful debt headroom. As the Fed enters a Q4 2026 rate-cut cycle, lower financing costs support DPU recovery — making FCT worth a close look for income-focused investors.
Not financial advice. All figures are for educational reference only. Data as at September 2026 unless noted.
Table of Contents
Contents — Click to expand
What Is Frasers Centrepoint Trust?
Frasers Centrepoint Trust (SGX: J69U) was listed on the Singapore Exchange in 2006 and is managed by Frasers Property Retail Asset Management Pte. Ltd., a wholly owned subsidiary of Frasers Property Limited. FCT focuses exclusively on suburban retail malls in Singapore — a deliberate strategy that insulates it from the cyclicality of office and industrial markets.
As at September 2026, FCT’s portfolio spans nine income-producing retail properties with approximately 2.2 million square feet of NLA. These malls are anchored by supermarkets, medical clinics, enrichment centres, and food courts — tenant categories that hold up even when consumer spending tightens. This defensive positioning explains why FCT has maintained near-full occupancy across multiple interest rate cycles.
Unlike Grade-A CBD office REITs sensitive to corporate headcount decisions, FCT’s suburban shopper base is driven by catchment population density. With Singapore’s HDB BTO projects concentrated in the north and northeast corridors where FCT’s strongest malls sit, the REIT is structurally aligned with long-term residential population growth. An earlier deep-dive covering FCT’s post-FOMC rate-hike impact on DPU and gearing remains useful context for the Q4 2026 rate-cut pivot.
FCT Key Facts at a Glance
The table below summarises FCT’s key investment metrics as at September 2026, sourced from FCT’s latest quarterly business update and SGX filings.
| Metric | Detail |
|---|---|
| SGX Ticker | J69U |
| REIT Manager | Frasers Property Retail Asset Management |
| Portfolio (Sep 2026) | 9 suburban retail malls, ~2.2M sq ft NLA |
| Portfolio Valuation | ~S$6.8 billion (as at Jun 2026) |
| Gearing | ~34.5% (post White Sands disposal) |
| Portfolio Occupancy | ~99.5% |
| WALE (by NLA) | ~2.7 years |
| FY2025 DPU | ~11.80 cents per unit |
| FY2026F DPU | ~12.10 cents per unit (analyst consensus) |
| Distribution Yield | ~6.3% at S$2.28/unit (Sep 2026) |
Source: FCT quarterly business updates, SGX filings, analyst consensus (September 2026). FY2026F/FY2027F represent market consensus only.
Q4 2026 Rate-Cut Impact on FCT Share Price and DPU
The Federal Reserve’s pivot into a rate-cut cycle in late 2025 is the most important macro driver for S-REITs heading into Q4 2026. For FCT, the impact works through two clear channels.
Channel 1 — Lower borrowing costs. FCT carries approximately S$2.1 billion in total debt. Every 50 basis point reduction in SORA — which tracks Fed funds movements with a short lag — reduces FCT’s annual finance costs by an estimated S$10 to S$15 million, or roughly 0.40 to 0.55 cents per unit in additional distributable income. For investors building a passive income Singapore strategy, this direct interest savings mechanism is the core transmission channel between monetary policy and quarterly distributions.
Channel 2 — Valuation re-rating. REITs trade on an implied yield spread over the Singapore 10-year government bond. As risk-free rates fall, the distribution yield needed to attract capital also falls — yield compression translates to a higher unit price. FCT’s approximately 6.3% yield at S$2.28 looks attractive if the 10-year SGS bond falls toward 2.5% in a full rate-cut cycle, creating scope for the unit price to trend higher.
A practical illustration. A Singapore investor holding 100,000 FCT units at S$2.28 per unit (portfolio value: S$228,000) currently receives approximately S$11,800 per year at the FY2025 DPU of 11.80 cents. If DPU recovers to 12.5 cents by FY2027, the annual payout rises to S$12,500 — a 5.9% increase. Model how FCT distributions combine with CPF LIFE payouts using the Singapore retirement planning calculator on this site.
FCT Portfolio: Singapore Suburban Retail Resilience
FCT’s portfolio is concentrated in suburban Singapore, which is structurally defensive compared to Orchard Road retail. Suburban malls serve essential needs — groceries, healthcare, childcare, and food courts — rather than discretionary luxury spending. Tenant demand is anchored in population density, not tourist arrivals or corporate entertainment budgets.
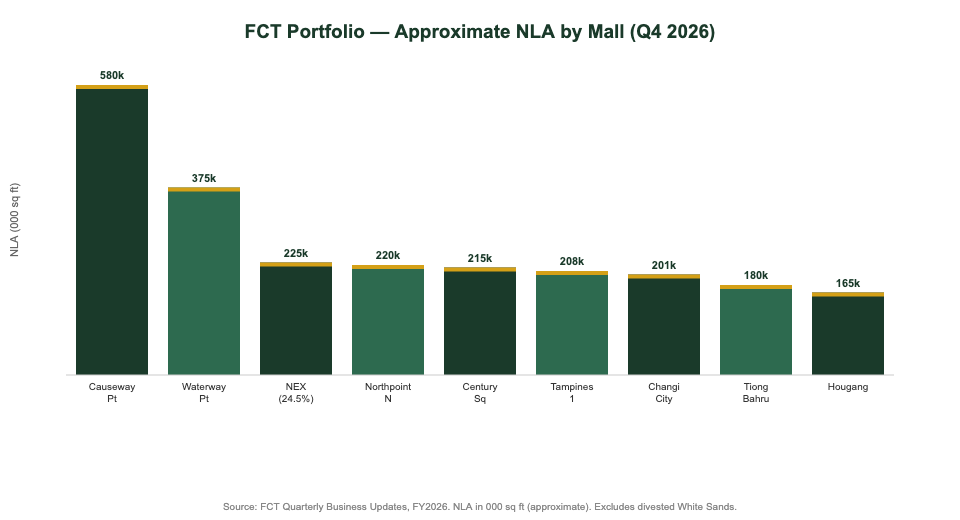
| Mall | Location | Est. NLA | Key Anchor |
|---|---|---|---|
| Causeway Point | Woodlands | ~580,000 sq ft | NTUC FairPrice, Courts |
| Waterway Point | Punggol | ~375,000 sq ft | NTUC FairPrice Extra, Golden Village |
| NEX (24.5% stake) | Serangoon | ~225,000 sq ft FCT share | Cold Storage, BHG |
| Northpoint City North Wing | Yishun | ~220,000 sq ft | NTUC FairPrice, Kopitiam |
| Century Square | Tampines | ~215,000 sq ft | NTUC FairPrice Finest |
| Tampines 1 | Tampines | ~208,000 sq ft | FairPrice Finest, lifestyle retail |
| Changi City Point | Changi Business Park | ~201,000 sq ft | Outlet-style, sports retail |
| Tiong Bahru Plaza | Tiong Bahru | ~180,000 sq ft | Cold Storage, Shaw Theatres |
| Hougang Mall | Hougang | ~165,000 sq ft | NTUC FairPrice |
Source: FCT quarterly business updates and annual report filings (FY2026). NLA is approximate. White Sands (Pasir Ris) divested in 3QFY2026.
FCT DPU History and Recovery Outlook
FCT’s distribution per unit (DPU) trajectory illustrates the interest rate cycle clearly. DPU peaked before the aggressive rate-hiking cycle of 2022 to 2024, dipped as higher financing costs squeezed distributable income, and is now expected to recover as the Fed eases. The White Sands disposal added a structural shift: it permanently removed White Sands’ rental income but reduced the annual interest expense burden meaningfully.
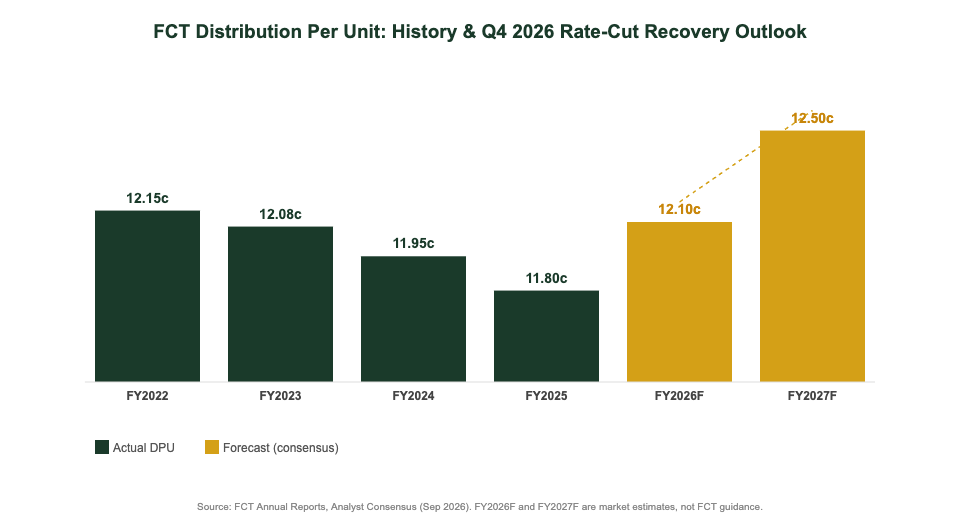
FY2026 reflects a partial-year effect from White Sands disposal (completed mid-FY2026). The FY2027 recovery assumes the rate-cut cycle contributes approximately 0.45 to 0.55 cents per unit in reduced finance costs, partially offset by the permanent loss of White Sands NPI.
For investors building a diversified income portfolio alongside S-REITs, the Singapore T-bills 2026 guide and Singapore Savings Bonds guide on this site cover complementary fixed-income instruments — illustrating the risk premium FCT’s ~6.3% yield offers over the 1.8 to 2.2% risk-free rate range.
Gearing Position and Acquisition Pipeline
The White Sands divestment for S$467 million — approximately 5.9% above the last independent valuation — drove gearing from approximately 38 to 39% down to approximately 34.5%. This frees roughly S$800 million to S$1 billion in acquisition headroom before FCT approaches the 40% threshold.
FCT’s sponsor, Frasers Property Limited, holds a pipeline of suburban retail assets in Singapore and the region, with FCT enjoying a right of first refusal on Singapore retail assets the sponsor brings to market. If the rate-cut cycle continues into 2027, FCT could announce an acquisition that partially offsets the White Sands income loss while maintaining a stronger balance sheet. Income-focused investors evaluating platforms to access FCT can explore the Syfe referral code page for automated REIT portfolio options, or the FSMOne referral code page for direct brokerage. For a comparative view across the sector, the best S-REITs in Singapore 2026 ranking contextualises FCT’s yield and gearing position.
Who Should Invest in FCT?
FCT suits Singapore investors who prioritise income stability over capital growth. Its approximately 6.3% distribution yield, backed by near-full occupancy and a well-diversified suburban retail portfolio, makes it one of the more dependable income plays in the S-REIT universe.
FCT suits you if: you want quarterly distributions from anchor-tenanted suburban Singapore malls with low vacancy risk; you believe the rate-cut cycle will continue into 2027, reducing financing costs and supporting DPU recovery; and you are comfortable with the ~2.7 year WALE (short leases mean regular roll-over, but also the opportunity to capture rental uplifts in a firm retail market).
FCT suits you less if: you are seeking high capital growth — FCT’s price is closely tied to the yield spread over risk-free rates; or you need exposure to industrial, data centre, or overseas market growth other S-REITs offer. The Singapore REIT ETF guide covers diversified REIT exposure for investors who want broader sector coverage in a single instrument.
Disclaimer: This article is for educational purposes only and does not constitute financial advice. Past DPU performance is not indicative of future distributions. Consult a licensed financial adviser before making investment decisions.
Frequently Asked Questions
What is Frasers Centrepoint Trust share price today?
How often does FCT pay distributions?
What happened to White Sands mall and how does it affect FCT?
Is FCT a good buy in Q4 2026?
What is FCT gearing ratio and how much acquisition headroom does it have?
How does FCT compare to other Singapore retail REITs?
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.