DBS Endowment Plans 2026
Are 1.44%–1.60% Guaranteed Returns Worth It After the Rate Hike?
Data verified as at 24 September 2026. Source: DBS Bank (dbs.com.sg). This article is for informational purposes only and does not constitute financial advice.
If you bank with DBS, you’ve probably seen the SavvyEndowment 23 banner — offering guaranteed returns of 1.44% p.a. for two years, with a potential of up to 1.60% p.a.
At first glance, that sounds reasonable. But when 6-month Singapore T-bills are yielding around 3.5%+ and the Fed just hiked rates again in 2026, is a DBS endowment plan actually a good deal?
This article breaks down every DBS endowment option available in Q4 2026, compares the numbers honestly, and tells you exactly when a DBS endowment makes sense — and when it doesn’t.
What DBS Offers in 2026
DBS distributes endowment plans underwritten by Manulife Singapore. In Q4 2026, the primary options are:
| Plan | Type | Guaranteed Return | Potential Return | Term | Min Premium |
|---|---|---|---|---|---|
| SavvyEndowment 23 | Short-term savings | 1.44% p.a. | Up to 1.60% p.a. | 2 years | S$5,000 |
| Manulife Goal 2026 (I) | Short-term savings | TBC (up to 1.60% p.a. potential) | Up to 1.60% p.a. | 2 years | Single premium |
| SavvySpring (II) | Long-term savings + protection | Participating | Par fund returns | 12 years | Regular premium |
| RetireSavvy | Retirement income | Customisable | Par fund | Flexible | Regular premium |
Source: DBS Bank Singapore, dbs.com.sg, verified September 2026.
SavvyEndowment 23: Full Review
SavvyEndowment 23 is DBS’s flagship short-term endowment in 2026. It’s underwritten by Manulife Singapore and distributed exclusively through DBS digibank.
Key Numbers
- Guaranteed return: 1.44% p.a. for 2 years
- Potential total return: Up to 1.60% p.a. (includes 0.16% non-guaranteed maturity bonus)
- Capital guarantee: 100% at maturity
- Death coverage: 101% of single premium paid during the policy term
- Minimum single premium: S$5,000
- Application: 100% online, no health check required
- Eligible age: 18 to 75 years old (last birthday)
- Payment: Cash or SRS funds
Worked Example (S$20,000)
- Scenario 1 (higher illustrated rate): S$20,000 × (1.0160)² − S$20,000 = S$646 gain
- Scenario 2 (guaranteed only): S$20,000 × (1.0144)² − S$20,000 = S$582 gain
The non-guaranteed bonus of S$64 (on S$20,000 over 2 years) is modest. In practice, most buyers should plan around the guaranteed 1.44% floor.
The Catch: Early Surrender
Early termination before maturity can result in a surrender value lower than your total premiums paid. This is a 2-year commitment — not a cash management tool.
Manulife Goal 2026 (I)
Also available through DBS, the Manulife Goal 2026 (I) is another 2-year single premium endowment plan with a potential yield of up to 1.60% p.a.. The structure is similar to SavvyEndowment 23, and both are underwritten by Manulife Singapore.
DBS periodically launches different tranches of these plans. If SavvyEndowment 23 is fully subscribed or closed to new applications, Manulife Goal 2026 (I) may be the alternative. Check DBS digibank for current availability.
DBS Endowment vs T-Bills vs Fixed Deposits
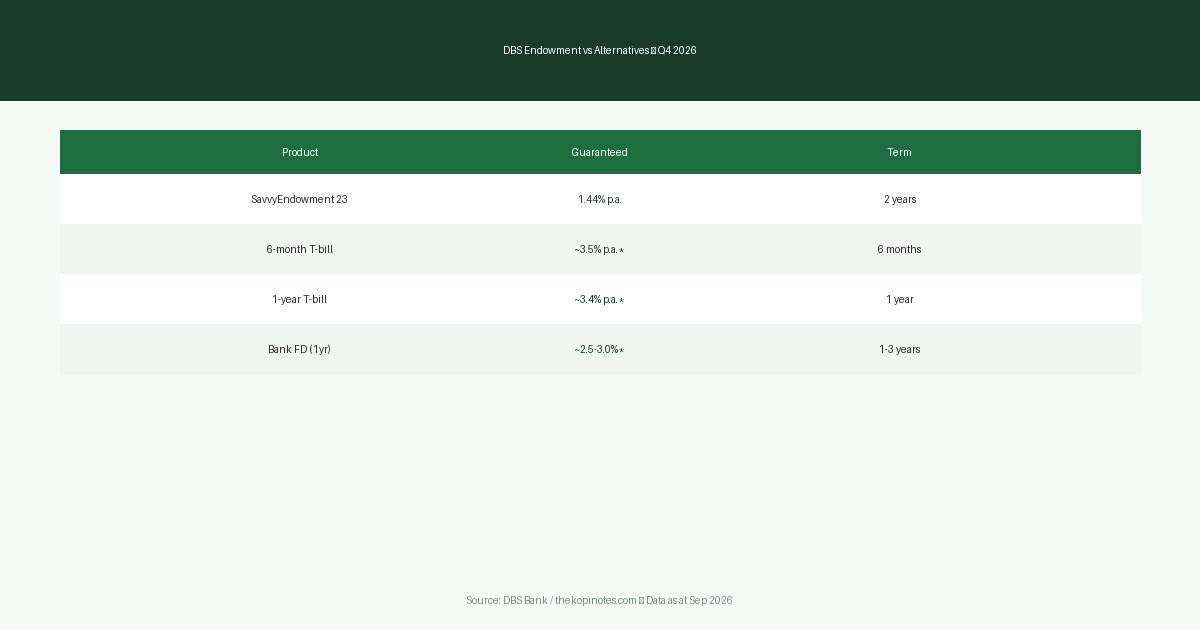
This is the honest question. In Q4 2026, after the Fed rate hike brought rates to 3.75–4%:
| Product | Return | Capital Safe? | Term | Death Coverage? |
|---|---|---|---|---|
| SavvyEndowment 23 | 1.44% p.a. guaranteed | Yes (100% at maturity) | 2 years | Yes (101%) |
| 6-month T-bill | ~3.5% p.a.* | Yes (MAS backed) | 6 months | No |
| 1-year T-bill | ~3.4% p.a.* | Yes (MAS backed) | 1 year | No |
| Bank fixed deposit (1 year) | ~2.5–3.0% p.a.* | Yes (SDIC up to S$100k) | 1–3 years | No |
*T-bill and FD rates are approximate as at Q4 2026. They fluctuate with each auction. Check MAS or your bank for current rates before deciding. Past auction rates do not guarantee future cut-off yields.
On a pure yield comparison, T-bills currently beat DBS endowment returns significantly. For most investors parking cash, T-bills or fixed deposits offer better returns with more flexibility.
See our guide: T-Bill Singapore 2026: Complete Guide
The DBS Multiplier Angle
Here’s where DBS endowment plans get more interesting. Holding SavvyEndowment 23 qualifies your DBS Multiplier Account for bonus interest.
According to DBS, holding an eligible Manulife protection or endowment plan distributed by DBS can help you earn up to 4.1% p.a. on your DBS Multiplier Account balance (subject to meeting all qualifying criteria, including crediting your salary to DBS).
For DBS customers who already credit their salary to DBS Multiplier and want to boost their savings account tier, SavvyEndowment 23 can serve as a qualifying product to unlock higher Multiplier interest rates. In that context, the 1.44% on the endowment itself is less important than the tier boost it provides on a much larger Multiplier balance.
This is the scenario where DBS endowment plans make the most financial sense for existing DBS customers.
SRS Compatibility
SavvyEndowment 23 can be purchased using SRS (Supplementary Retirement Scheme) funds. This is a key advantage over T-bills, which cannot be purchased with SRS money directly.
If you’ve maxed out your SRS contributions (S$15,300 per year for Singapore citizens) and need to deploy those funds while awaiting a better investment, SavvyEndowment 23’s 1.44% guaranteed return is competitive for SRS money. The capital is protected at maturity, and you get death coverage on top.
For SRS holders comparing options, also see: Singapore Savings Plans After the Fed Rate Hike
Verdict: Who Should (and Shouldn’t) Buy a DBS Endowment in 2026
Buy if you:
- Are a DBS Multiplier customer and want to boost your savings account interest tier
- Have SRS funds sitting idle and want capital-guaranteed returns (T-bills are not available via SRS direct)
- Want basic death coverage bundled with your savings (101% of premium)
- Are between ages 65–75 and want a simple, no-health-check capital-guaranteed product
- Prefer the convenience of an all-in-one DBS ecosystem (digibank, SRS, Multiplier)
Skip if you:
- Are purely optimising for yield — T-bills at ~3.5% currently outperform by a wide margin
- May need liquidity before the 2-year term ends (early surrender can return less than premiums)
- Already have standalone term insurance and don’t need the death coverage feature
- Are not a DBS Multiplier customer and won’t benefit from the tier boost
For most Singaporeans focused on yield in the current high-rate environment, our broader endowment plan comparison guide and the T-bill guide will be more useful. DBS endowment plans shine specifically for DBS ecosystem users and SRS money.
Referral Bonuses: If you’re opening a DBS account or exploring other platforms, here are some useful referral codes: MariBank (code: 2DCT80WQ), Trust Bank (code: HTWYQP95), GXS (code: YONG477). Always compare rates before committing.
Frequently Asked Questions
Is DBS endowment plan safe?
What is the minimum amount for DBS SavvyEndowment 23?
Can I use CPF to buy DBS endowment plans?
What happens if I surrender SavvyEndowment 23 early?
Is SavvyEndowment 23 still available in 2026?
How does DBS endowment compare to Singapore T-bills?
Get Free Insurance Advice
Speak with a licensed insurance advisor. No obligation, no cost.
By submitting this form, you agree to our Privacy Policy.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.