What Happens to Your Unspent Medisave Balance at Year-End? (2026)
Your unspent Medisave balance does not expire or get forfeited at year-end — it rolls over in full to the following year and continues earning interest. In 2026, the Basic Healthcare Sum (BHS) — the cap on how much can sit in your Medisave Account (MA) — is $79,000, up from $75,500 in 2025. Any balance below this cap earns 4% per annum. Once your MA hits $79,000, new contributions and interest overflow redirect automatically to your Special Account or Retirement Account, so you never lose a cent.
Not financial advice. All figures are for educational reference only. Data as at November 2026 unless noted.
Does Unspent Medisave Roll Over? The Short Answer Is Yes
Many CPF members worry — especially toward the end of November and December — that any Medisave balance they haven’t spent on healthcare premiums will disappear on 1 January. This is a misconception. Medisave is not an annual “use-it-or-lose-it” scheme.
Your Medisave Account (MA) is one of four CPF accounts. Unlike a flexible spending account under some employer health plans, it has no annual forfeiture rule. Whatever sits in your MA on 31 December simply stays there, continues to compound, and is available for the same eligible purposes — MediShield Life premiums, Integrated Shield Plan (ISP) premiums, hospitalisation bills, day surgery, certain outpatient treatments, and approved chronic disease management — in the new year.
What does change each year is the Basic Healthcare Sum (BHS), which is the ceiling on how much can be held in your MA. Understanding the BHS is the key to understanding what actually happens to your Medisave balance at year-end.
If you are researching how Medisave interacts with your Integrated Shield Plan, the full picture is in our Medisave 2026 Singapore guide, which covers the annual contribution limits, withdrawal rules, and how ISP premiums are deducted monthly.
The Basic Healthcare Sum (BHS): $79,000 in 2026
The BHS is revised annually by the Ministry of Health (MOH) to keep pace with estimated Medisave usage for a subsidised stay in a B2-class ward during one’s lifetime. For 2026, the BHS is $79,000 — an increase of $3,500 from the 2025 figure of $75,500. This was announced in the MOH press release dated 15 December 2025.
The BHS matters for one specific reason: once your MA balance hits $79,000, Medisave can no longer accept new deposits above that level. Contributions that would have gone into your MA (from your monthly CPF contributions or voluntary top-ups) are automatically redirected to other CPF accounts instead — your Special Account (SA) if you are under 55, or your Retirement Account (RA) if you are 55 and above.
Until your balance reaches $79,000, there is no ceiling effect and your MA simply accumulates as it normally would — from CPF contributions, employer contributions, government grants such as the Medisave top-up for Pioneer and Merdeka Generation members, and the annual 4% interest credited by CPF Board.
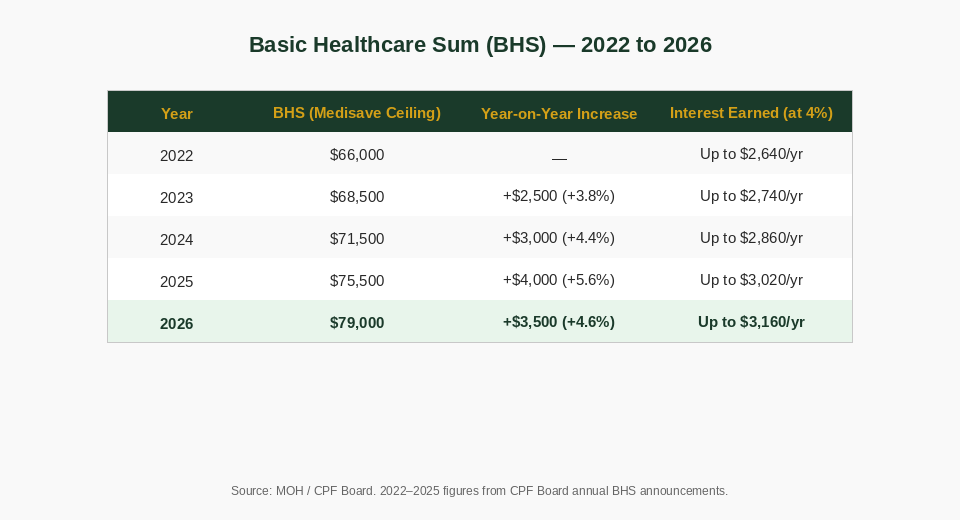
Source: MOH press releases and CPF Board. BHS raised from $66,000 (2022) to $79,000 (2026). Data as at 21 November 2026.
The table above shows how the BHS has grown by roughly 4–6% each year since 2022. This steady upward revision is deliberate: it reflects projected healthcare cost inflation and ensures that members build an adequate Medisave cushion over their working lives.
| Year | BHS (Medisave Ceiling) | YoY Change | Max Annual Interest at 4% |
|---|---|---|---|
| 2022 | $66,000 | — | Up to $2,640/yr |
| 2023 | $68,500 | +$2,500 | Up to $2,740/yr |
| 2024 | $71,500 | +$3,000 | Up to $2,860/yr |
| 2025 | $75,500 | +$4,000 | Up to $3,020/yr |
| 2026 | $79,000 | +$3,500 | Up to $3,160/yr |
Source: MOH press releases; CPF Board. BHS announced each December for the following year. Interest is computed on the full MA balance at 4% p.a. (SMRA floor rate, Q1 2026).
What Happens When Your Medisave Account Exceeds the BHS
This is the scenario that trips up the most people. Once your MA balance reaches $79,000, here is what happens to any additional funds that would otherwise flow in:
1. Monthly CPF Contributions
Your employer and your own CPF contributions are split across OA, SA, and MA according to your age group. Once your MA hits $79,000, the MA portion of each month’s contribution is automatically rerouted to your SA (or RA if you are 55+). You do not need to do anything — CPF Board handles this automatically.
2. Annual 4% Interest
Interest on your MA is credited on the last day of each calendar year (and also monthly in some cases). If the credited interest pushes your MA over $79,000, the excess is transferred to your SA (under 55) or RA (55+). If your SA has already met the Full Retirement Sum (FRS), the excess may instead flow to your Ordinary Account (OA).
3. Voluntary Medisave Top-Ups
If you or a family member is topping up your MA voluntarily (for example, using cash top-ups or transferring from OA), CPF Board will reject or limit the transaction if it would breach the BHS. You can only top up to exactly $79,000.
Key takeaway: you do not “lose” any Medisave above the BHS. It simply flows to another CPF account where it continues to work for your retirement or remains accessible (in the case of OA) for other approved uses such as housing.
For a worked example of how ISP premium deductions interact with your MA balance throughout the year, see our step-by-step hospitalisation claim guide for 2026.
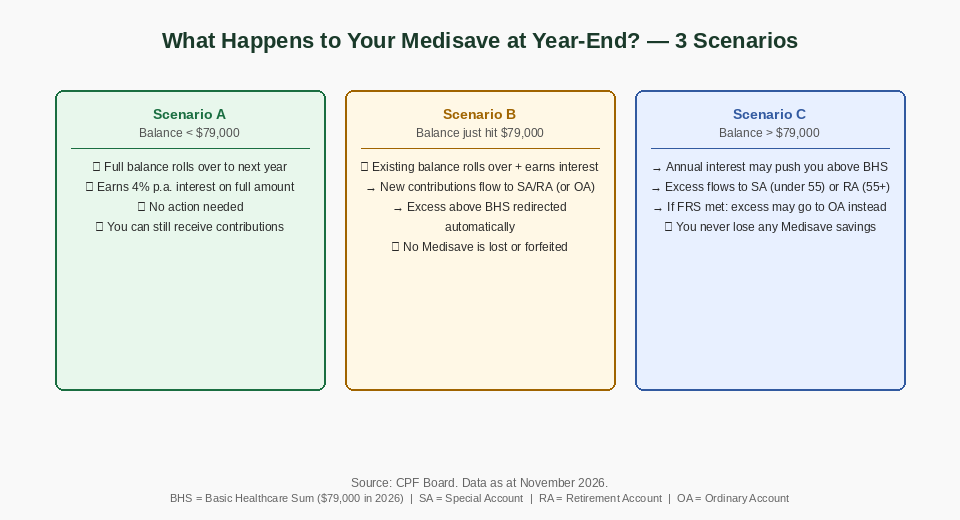
Source: CPF Board. Scenarios based on BHS of $79,000 for 2026. Data as at 21 November 2026.
How Medisave Interest Works in 2026
Medisave earns interest at the Special Member Rate Account (SMRA) rate, subject to a floor of 4% per annum. For Q1 2026, the SMRA rate is exactly at this 4% floor. The interest is computed daily on the closing balance of your MA and credited monthly, with any adjustments applied at year-end.
This 4% rate is notably higher than the OA rate (currently 2.5% base + 1% extra interest on the first $20,000 of combined CPF balances). It is one of the main reasons financial planners consider a healthy Medisave balance to be a risk-free, government-guaranteed return comparable to long-dated Singapore Government Securities.
Interest Calculation Example
Say your MA balance stands at $60,000 on 1 January 2026. At 4% p.a., you would accrue approximately $2,400 in interest over the year. Your balance would grow to around $62,400 by 31 December 2026 (before any new contributions or withdrawals). Since $62,400 is well below the $79,000 BHS, all of this stays in your MA.
If instead your balance is $78,000 on 1 January, the 4% interest would add approximately $3,120 — bringing your balance to roughly $81,120. The $2,120 above the $79,000 BHS would be redirected to your SA or RA at year-end. Again, nothing is lost.
| MA Balance (Jan 1) | Interest Earned at 4% p.a. | Balance (Dec 31) | Outcome |
|---|---|---|---|
| $40,000 | ~$1,600 | ~$41,600 | Stays in MA |
| $60,000 | ~$2,400 | ~$62,400 | Stays in MA |
| $75,000 | ~$3,000 | ~$78,000 | Stays in MA |
| $78,000 | ~$3,120 | ~$81,120 | $2,120 → SA/RA |
| $79,000 | ~$3,160 | ~$82,160 | $3,160 → SA/RA |
Illustrative only. Actual interest accrual is computed daily. Contributions, withdrawals, and government grants will affect the actual balance. Data as at November 2026.
The practical implication: if your MA is close to but not yet at the BHS, your November–December ISP premium deductions and CPF contributions may bring it slightly away from $79,000, giving you room to absorb more of the year-end interest credit inside your MA rather than having it overflow to SA.
For detailed year-end planning strategies, our November–December Medisave planning guide walks through specific scenarios and what actions (if any) you can take.
Year-End Medisave Checklist for 2026
Even though your unspent Medisave rolls over automatically, the year-end period is a good time to review your Medisave position. Here is a simple checklist:
1. Check Your Current MA Balance
Log in to your CPF account at cpf.gov.sg or via the CPF Mobile app. Note your current MA balance and compare it to the 2026 BHS of $79,000. Our guide on how to check your remaining Medisave balance explains exactly where to find this.
2. Review Your ISP Premium Deductions
Your Integrated Shield Plan (ISP) premiums are deducted from Medisave monthly or annually, depending on your insurer. If your ISP premium deductions are set to auto-debit from Medisave and your MA balance is very low, it is worth confirming that the December deduction will process without issue. If your MA runs dry, you will need to pay the premium in cash. See our ISP rider guide for 2025–2026 for what to do if a premium lapses.
3. Confirm Your Beneficiary Nominations Are Up to Date
CPF nominations cover all your CPF accounts, including your MA. If your circumstances have changed — a new spouse, the birth of a child, the death of a previous nominee — update your nomination at any CPF Service Centre or online.
4. Consider Voluntary Medisave Top-Ups (if below BHS)
If your MA is below $79,000, you can make voluntary cash top-ups. These qualify for income tax relief of up to $8,000 per year (combined across all CPF cash top-ups under the Retirement Sum Topping-Up scheme) and immediately start earning 4% per annum. Only do this if you are comfortable with the fact that Medisave funds can only be withdrawn for approved healthcare expenses.
5. Plan Your Retirement Savings
If your MA is at or near the BHS and your CPF contributions are already overflowing to your SA or RA, you are in a strong position. Consider whether your overall retirement plan is on track using our Singapore retirement planning calculator. For hands-off, CPF-integrated investing, platforms like Endowus (referral code 2V343) and Syfe (referral code SRPRFFFCD) offer CPF OA investment portfolios to grow your savings beyond the standard CPF interest rates.
Frequently Asked Questions
Does my Medisave expire at the end of the year?
What is the Medisave limit (BHS) in 2026?
What happens if my Medisave balance goes above $79,000?
What happens if my Medisave balance goes above $79,000?
Can I top up my Medisave account to earn more interest?
How does Medisave interact with my Integrated Shield Plan (ISP) premiums?
When exactly is Medisave interest credited?
Make Your CPF Savings Work Harder
Your Medisave earns a guaranteed 4% — but your OA can do more. Platforms like Endowus and Syfe let you invest your CPF OA savings in diversified, low-cost portfolios to potentially grow your retirement nest egg beyond the standard 2.5%.
Get Free Insurance Advice
Speak with a licensed insurance advisor. No obligation, no cost.
By submitting this form, you agree to our Privacy Policy.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.