MediSave Limit 2026: Prostate Surgery in Singapore — What ISP and MediSave Actually Cover
The 2026 MediSave surgical limit for most prostate procedures runs from $2,440 to $3,260 — but a typical private hospital bill for TURP can hit $24,354. Whether you are facing BPH treatment or planning ahead for prostate cancer surgery, this guide breaks down the exact TOSP code that applies to your procedure, how much MediSave pays, what your Integrated Shield Plan adds on top, and your likely out-of-pocket cost at each ward class.
Not financial or medical advice. All figures are for educational reference only. MediSave limits and ISP terms are correct as at November 2026. Consult your insurer and surgeon before making any healthcare decisions.
Contents
- What Is Prostate Surgery in Singapore?
- How MediSave Works for Surgical Procedures
- TOSP Codes and Surgical Claim Limits for Prostate Surgery
- What Your Integrated Shield Plan Covers
- Real Bill Scenarios: Ward B2 vs Private Hospital
- Which Ward Class Should You Choose?
- Pre-Surgery Checklist for MediSave and ISP Claims
- Frequently Asked Questions
What Is Prostate Surgery in Singapore?
Prostate surgery in Singapore is most commonly performed for two conditions: benign prostatic hyperplasia (BPH) and prostate cancer. BPH — a non-cancerous enlargement of the prostate gland — affects roughly 40% of men over 60 and over 80% of men over 80. When medication fails to control symptoms like frequent urination, weak flow, or inability to empty the bladder, surgery becomes the recommended next step.
The most common BPH surgeries covered by MediSave in Singapore are:
- TURP (Transurethral Resection of the Prostate) — the gold-standard surgical treatment for BPH, performed under spinal or general anaesthesia. Most patients stay three to five nights inpatient.
- HoLEP (Holmium Laser Enucleation of the Prostate) — a newer laser technique increasingly preferred for larger prostates; shorter hospital stay but higher upfront cost.
- Simple prostatectomy — open or laparoscopic surgery for very large prostates; less common today due to minimally invasive alternatives.
For prostate cancer, the primary surgical option is radical prostatectomy (robotic-assisted or open), which removes the entire prostate gland. This is a more complex procedure with significantly higher bills and a different TOSP code. If you are facing prostate cancer treatment, see also our guide on how ISP covers cancer treatment in Singapore.
All these procedures are approved under Singapore’s Table of Surgical Procedures (TOSP), which means they qualify for MediSave surgical claims and are covered by Integrated Shield Plans as medically necessary admissions.
How MediSave Works for Surgical Procedures
MediSave is the healthcare savings component of your CPF account. When you are admitted to hospital for a surgical procedure, you can use MediSave to pay two categories of charges — daily hospitalisation and the surgical procedure itself.
MediSave inpatient daily limits (2026): You can claim up to $1,130 per day for the first two days of your hospital stay, then $400 per day from day three onward. These limits cover ward fees, nursing, and ancillary charges. For a typical five-night TURP admission, the daily MediSave claim adds up to: $1,130 × 2 + $400 × 3 = $3,460.
MediSave surgical limits are set by the Table of Surgical Procedures (TOSP). Each procedure is assigned a table (Table 1 to Table 7, with higher numbers meaning higher complexity), and that table determines the maximum you can claim from MediSave for the surgery itself. For prostate procedures, the limits range from $2,440 to $3,260 depending on which code your surgeon uses.
The combined MediSave claim for a typical five-night TURP admission therefore runs to around $5,210 to $6,230 — the daily component plus the surgical component. For detailed information on how TOSP tables work across all procedure categories, see our complete MediSave limit 2026 guide.
MediSave does not cover outpatient consultations, GP visits, or medications prescribed after discharge. It also has an annual withdrawal limit per admission, so if you have multiple surgeries in the same year, each draws from the same account.
TOSP Codes and Surgical Claim Limits for Prostate Surgery
The TOSP code your surgeon assigns determines your MediSave surgical claim ceiling. For prostate surgery in Singapore, four codes are most commonly used. The key factor differentiating TURP codes is the weight of tissue resected — a simple indicator of procedure complexity that your surgeon will record.
| Procedure | TOSP Code | TOSP Table | MediSave Surgical Limit |
|---|---|---|---|
| TURP (resected weight <30 g) | SH836P | Table 4B | $2,440 |
| TURP / Enucleation (resected weight >30 g) | SH837P | Table 5C | $2,770 |
| Simple Prostatectomy (open / lap) | SH829P | Table 4B | $2,440 |
| Radical Prostatectomy (without lymph node dissection) | SH830P | Table 6A | $3,260 |
Source: MOH Table of Surgical Procedures (TOSP), Nov 2026
What about HoLEP? Holmium laser enucleation of the prostate (HoLEP) is a laser-based BPH procedure that removes the entire prostate lobe rather than just resecting tissue. In Singapore, HoLEP is typically coded under SH837P (TURP/enucleation with resected weight >30 g), giving it the same $2,770 MediSave surgical limit. Confirm the code with your urologist before admission, as coding can vary between hospitals.
For a full explanation of how TOSP tables translate to MediSave claim amounts across all surgery types, our MediSave hospitalisation and surgery TOSP guide covers every table in detail.
What Your Integrated Shield Plan (ISP) Covers
An Integrated Shield Plan (ISP) is a private health insurance policy sold by Singapore’s major insurers — AIA, Prudential, Great Eastern, NTUC Income, AXA, and Singlife. It wraps around MediShield Life (the government’s basic scheme) to extend your coverage, particularly for private hospital stays and Ward A/B1 at public hospitals where the bills are substantially higher.
When you are admitted for prostate surgery, your ISP covers the charges that remain after MediSave has been applied. For a private hospital TURP bill of $24,354, MediSave handles roughly $6,230 of that — your ISP is responsible for the bulk of the remaining $18,124.
ISP Rider Rules from April 2026
MOH’s revised ISP rider framework, effective 1 April 2026, changed how riders supplement your base ISP plan. Under the new rules:
- All new and renewing riders must carry a minimum 5% copayment on eligible medical claims
- Your annual out-of-pocket copayment is capped at $6,000 per policy year, so even a very large bill caps your copayment exposure
- The deductible (the fixed amount you pay first before your rider kicks in) must be paid entirely from your own pocket — it is no longer covered by the rider. At a private hospital, this deductible is typically $3,500
Putting these together for a private hospital TURP bill of $24,354 with a standard ISP and rider:
- MediSave pays: $6,230
- Remaining bill: $18,124
- Your deductible: $3,500
- ISP/rider pool: $14,624
- Your 5% copayment on $14,624: $731
- ISP pays: $13,893
- Your total out-of-pocket: $4,231 (vs $18,124 without ISP)
For a full comparison of ISP plans in Singapore and how to pick the right coverage tier for your situation, see our Integrated Shield Plan Singapore 2026 guide.
Real Bill Scenarios: Ward B2 vs Private Hospital
The table below uses MOH’s official bill benchmarks (based on 2023 transaction data) for TURP with resected weight above 30 g (TOSP code SH837P). These figures are the typical bills before insurance and do not include physician fees billed separately at private hospitals — your actual bill may be higher.
| Setting | Typical Bill | MediSave (5-night) | ISP Pays | Your OOP |
|---|---|---|---|---|
| Public Ward B2 (subsidised) | $2,463 | $2,463 ✓ | Not needed | ~$0 |
| Public Ward A (non-subsidised) | $14,809 | $6,230 | ~$6,250* | ~$2,329* |
| Private Hospital (with ISP rider) | $24,354 | $6,230 | ~$13,893 | ~$4,231 |
| Private Hospital (no ISP) | $24,354 | $6,230 | $0 | $18,124 |
*ISP scenario based on $3,500 deductible (private) or $2,000 (Ward A), 5% copayment per April 2026 rider rules. Source: MOH Bill Benchmarks, SH837P (TURP >30g), 2023 data. Typical bill; range varies.
The takeaway is stark: at a subsidised Ward B2, MediSave covers the entire bill and you pay nothing out of pocket. At a private hospital without ISP, you face over $18,000 out of pocket. With a good ISP and rider, that exposure drops to roughly $4,231 — a difference of $13,893.
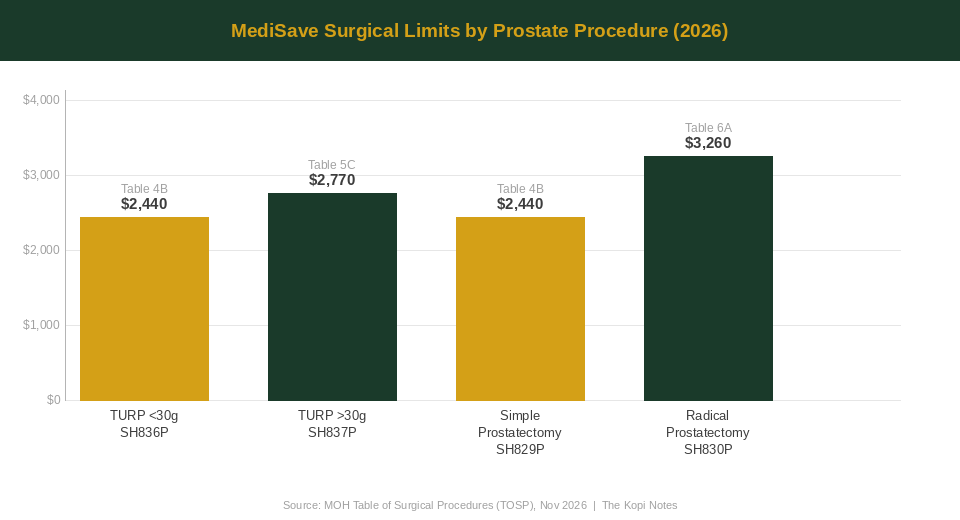
MediSave surgical claim limits by prostate TOSP code, 2026. Radical prostatectomy (SH830P, Table 6A) attracts the highest limit at $3,260. Source: MOH TOSP, Nov 2026.
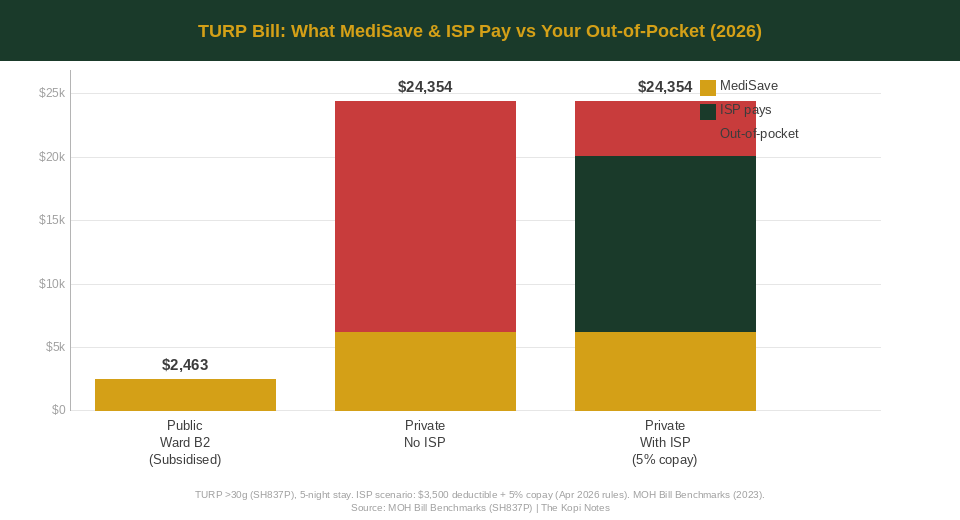
For a typical TURP >30g bill: at a public Ward B2 (subsidised), MediSave covers everything. At a private hospital without ISP, your out-of-pocket exceeds $18,000. With ISP, it drops to ~$4,231. Source: MOH Bill Benchmarks (SH837P, 2023).
Which Ward Class Should You Choose?
Your choice of ward class has a dramatic effect on your out-of-pocket cost — far more than which prostate procedure you have. Here is how to think through it.
Public Ward B2 or C (subsidised) is the right choice if you do not have an ISP, if your MediSave balance is healthy, or if you are comfortable with a shared ward. At this level, the MediSave claim typically covers the entire bill for a TURP. The trade-off is longer waiting times, shared rooms, and less choice of surgeon.
Public Ward A or B1 (non-subsidised) works well if you have an ISP that covers these wards. Bills run significantly higher than subsidised wards because government subsidies no longer apply, but they are still substantially lower than private hospital bills. With an ISP and rider, your out-of-pocket at Ward A is typically $2,000–$3,000 for a TURP.
Private hospital gives you the most choice — your preferred surgeon, a single room, faster scheduling. But bills easily exceed $20,000 for TURP and can reach $70,000 for radical prostatectomy. Without a comprehensive ISP covering private hospital stays, the financial exposure is severe. With a good ISP and the new 5% rider, you typically pay $4,000–$5,500 out of pocket for TURP at a private hospital.
The most important planning step: know your ISP’s ward entitlement before you check in. If your plan covers Ward A at a public hospital but not private hospital stays, choosing a private hospital can leave you with tens of thousands in uninsured charges. See our MediSave hospitalisation guide 2026 for more on matching ward class to your ISP tier.
Pre-Surgery Checklist for MediSave and ISP Claims
Getting the claims process right before you check in prevents nasty surprises at discharge. Work through this checklist at least two weeks before your planned admission:
- Confirm your TOSP code with your urologist — ask which code (SH836P, SH837P, SH829P or SH830P) will be assigned and what table it falls under. This determines your MediSave surgical claim ceiling.
- Check your MediSave balance via CPF’s website or app. Your balance must cover at least the daily hospitalisation charges; if it is low, your family member’s MediSave can be used instead.
- Contact your ISP insurer for pre-authorisation — most insurers require pre-authorisation for planned inpatient surgery. Failure to pre-authorise can result in reduced coverage or claim rejection.
- Confirm your ISP’s ward entitlement — check whether your plan covers the ward class you intend to stay in (Ward A, B1 or private).
- Understand your deductible and copayment — with the April 2026 rider rules, you will pay the deductible (typically $3,500 at private hospital) plus 5% of the remaining eligible charges, up to a $6,000 annual cap.
- Get itemised estimates from the hospital — most Singapore hospitals will provide a treatment cost estimate. Surgeon fees are often billed separately from hospital fees at private hospitals.
Frequently Asked Questions
Can I use MediSave for prostate (BPH) surgery in Singapore?
What is the TOSP code and MediSave limit for TURP surgery?
Does my ISP cover prostate surgery at a private hospital?
What is the new ISP copayment rule from April 2026?
Is HoLEP (holmium laser) surgery covered by MediSave in Singapore?
Does ISP cover radical prostatectomy for prostate cancer?
Plan Your Coverage Before You Need It
Prostate surgery is one of the most common reasons older Singapore men are admitted to hospital. The gap between what MediSave covers and the full private hospital bill can exceed $18,000 — money most people are not prepared to pay out of pocket at short notice. The right Integrated Shield Plan, reviewed before a diagnosis, can cap your exposure at around $4,000–$5,000 regardless of where you choose to be treated.
For a full comparison of ISP plans, the differences between base plans and riders, and how to pick the right coverage tier for private hospital stays, read our complete ISP guide for Singapore 2026. And for the full picture of what MediSave covers across all surgery categories, start with our MediSave limit 2026 Singapore guide.
Data sources: MOH Table of Surgical Procedures (Nov 2026); MOH Bill Benchmarks — SH836P, SH837P, SH830P (2023 transaction data); MOH inpatient MediSave limits (updated 27 Aug 2026). ISP copayment rules per MOH / LIA Singapore announcements effective 1 April 2026.
Get Free Insurance Advice
Speak with a licensed insurance advisor. No obligation, no cost.
By submitting this form, you agree to our Privacy Policy.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.