Medisave Limit 2026: Should You Schedule Elective Surgery Before or After December 31?
Your ISP deductible resets on 1 January — the timing of your operation can save (or cost) you thousands.
If you hold an Integrated Shield Plan (ISP), your annual deductible resets on 1 January every year. If you’ve already paid your deductible in 2026, booking an elective surgery before 31 December means skipping it entirely and paying only a 5% co-payment on the remaining bill. If you haven’t met it yet, the calculation changes. This guide walks through the exact scenarios so you can decide whether to call the hospital today or wait until 2027.
Not financial or medical advice. All figures are for educational reference only. Data verified as at 13 November 2026.
How the ISP Deductible Works — and Why 1 January Matters
Your Integrated Shield Plan has two cost-sharing components that work in sequence.
The deductible is a fixed annual amount you pay first — out of your own pocket (or Medisave) — before your insurer picks up the bill. Under the new rider framework that took effect on 1 April 2026, the minimum deductible ranges from $1,500 to $3,500 per policy year, depending on your ward class. The critical word is annual: the deductible counter resets to zero on the first day of your new policy year, which for most annual ISP policies is 1 January.
The co-payment is a percentage of the remaining bill you share with your insurer after the deductible is paid. The minimum co-payment under the April 2026 rules is 5%.
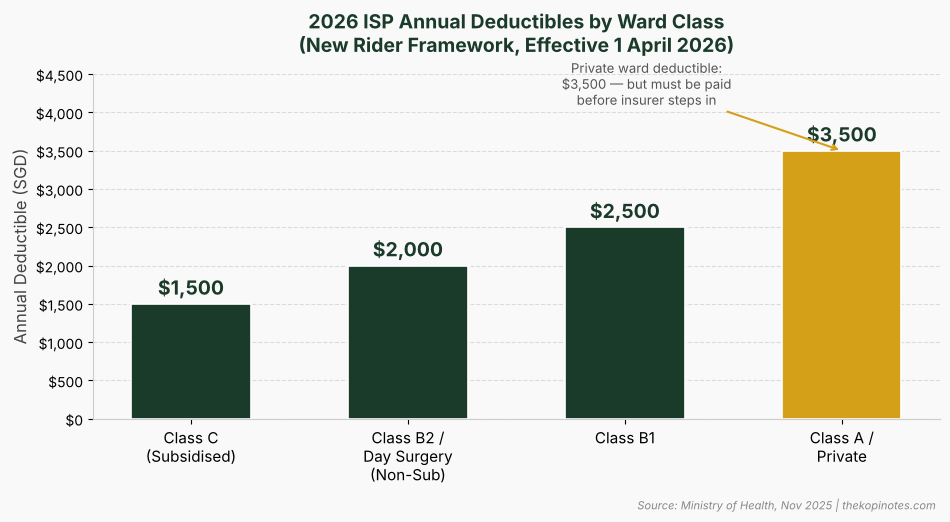
| Ward Class | Annual Deductible (2026) |
|---|---|
| Class C (subsidised) | $1,500 |
| Class B2 | $2,000 |
| Day surgery (non-subsidised) | $2,000 |
| Class B1 | $2,500 |
| Class A / Private | $3,500 |
Source: Ministry of Health, November 2025 — New IP rider requirements
Important change from April 2026: New ISP riders sold from 1 April 2026 are not permitted to cover the MOH minimum deductible. If you purchased a new rider after that date, you are responsible for the full deductible amount before your rider pays anything. Legacy riders (bought before 27 November 2025) may still cover part or all of the deductible under their existing contract — check your policy documents.
The Year-End Timing Calculation: Three Scenarios
Whether it makes financial sense to rush your elective surgery before December 31 depends on a single question: how much of your annual deductible have you already paid in 2026?
Scenario 1: Deductible Fully Met
If you’ve already paid your full deductible in 2026 — perhaps from an earlier hospitalisation or a prior elective procedure — booking surgery before December 31 means you owe only the 5% co-payment. No additional deductible.
Compare this to January 2027: your deductible resets to zero, and you’re back to paying the full deductible amount before your insurer steps in.
MOH illustration: Mrs B, 40, needs ACL reconstruction at a private hospital. The median 2024 bill for this procedure was $38,700. If her $3,500 deductible was already met earlier this year, her December surgery costs: 5% × $38,700 = $1,935. In January 2027, she’d pay: $3,500 (new deductible) + 5% × ($38,700 − $3,500) = $3,500 + $1,760 = $5,260. Timing the surgery before year-end saves her $3,325.
Scenario 2: Deductible Partially Met
If you’ve had hospital admissions in 2026 that have been counted toward your deductible — say, a minor surgery in March — the remaining deductible is lower than the annual maximum. MediShield Life accumulates deductible payments across multiple claims within a policy year.
Example: Your plan targets private ward (deductible $3,500). A day surgery in June cost $1,500 toward your deductible. A December elective surgery would only need you to cover the remaining $2,000 before the co-payment kicks in. Waiting until January resets you to $3,500.
Scenario 3: Deductible Not Yet Met
If you have no hospital admissions in 2026 and your deductible is at zero, the December/January timing makes no difference — you’ll pay the full deductible either way. The only exception: if you schedule two procedures in December, both bills in the same year count toward the same annual deductible.
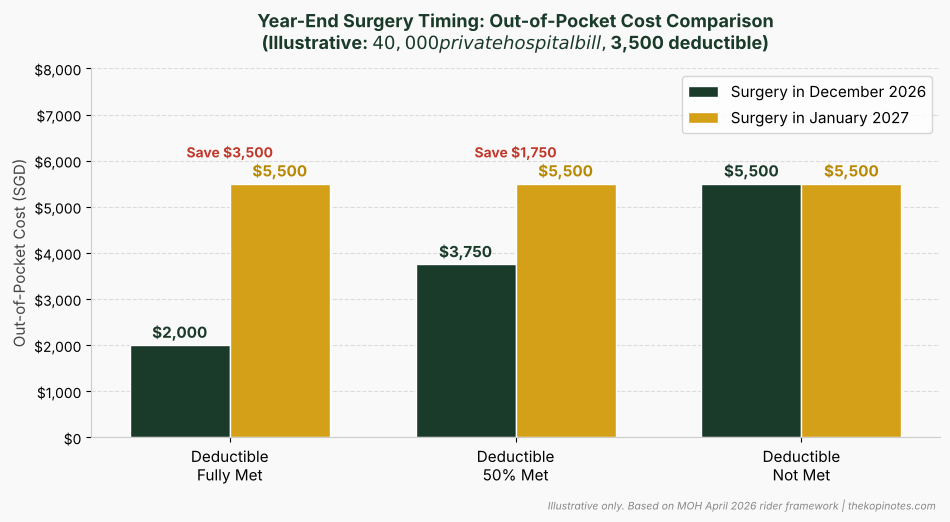
| Scenario | Surgery in Dec 2026 | Surgery in Jan 2027 | Timing Saving |
|---|---|---|---|
| Deductible fully met | $2,000 (5% co-pay only) | $5,500 (ded + co-pay) | $3,500 saved |
| Deductible 50% met ($1,750 paid) | $3,750 | $5,500 | $1,750 saved |
| Deductible not yet met | $5,500 | $5,500 | $0 |
Illustrative: $40,000 private hospital bill, $3,500 annual deductible, 5% co-payment. Based on MOH April 2026 rider framework. Individual bills will differ.
Important note on the co-payment cap: Under the new April 2026 framework, the annual co-payment cap (excluding the deductible) has been raised to a minimum of $6,000 per year for eligible claims such as panel or pre-authorised procedures. This means once you’ve paid $6,000 in co-payments in a policy year, your insurer covers eligible claims in full for the remainder of that year. The old cap was $3,000.
2026 MediSave Withdrawal Limits: What Gets Covered
Your ISP deductible and co-payment can both be paid using MediSave, subject to the prevailing withdrawal limits. For a typical surgical admission in 2026, MediSave covers the following amounts.
Daily hospitalisation charges (MediSave withdrawal per day):
- Days 1–2: up to $1,130 per day
- Day 3 onwards: up to $400 per day
- Day surgery episodes (same-day admission and discharge): up to $830 per day
- Approved community hospitals: up to $250 per day
On top of the daily hospital charge limit, MediSave also covers a surgical limit based on the TOSP (Table of Surgical Procedures) classification of your operation. The two amounts are added together for the total claimable per episode.
Source: Ministry of Health — MediSave for inpatient care, updated August 2026.
TOSP Surgical Limits: What MediSave Contributes per Operation
Every surgical procedure in Singapore is classified under a Table of Surgical Procedures (TOSP) category. The table determines the maximum MediSave withdrawal for the surgical component of your bill. Higher table numbers correspond to more complex procedures and higher MediSave limits.
| TOSP Classification | MediSave Surgical Limit (A / B / C) |
|---|---|
| Table 1 (A / B / C) | $240 / $420 / $490 |
| Table 2 (A / B / C) | $760 / $1,120 / $1,120 |
| Table 3 (A / B / C) | $1,390 / $1,740 / $1,920 |
| Table 4 (A / B / C) | $2,380 / $2,440 / $2,540 |
| Table 5 (A / B / C) | $2,610 / $2,660 / $2,770 |
| Table 6 (A / B / C) | $3,260 / $3,610 / $3,960 |
| Table 7 (A / B / C) | $4,340 / $4,830 / $5,290 |
Source: Ministry of Health — MediSave inpatient care limits, updated August 2026
For a 2-day private hospital stay involving a Table 7A procedure, MediSave can contribute up to $1,130 × 2 (hospital charges) + $4,340 (surgical limit) = $6,600 toward your total bill. This can cover a significant portion of the deductible and co-payment you are responsible for under the new 5% co-payment rule.
Your surgeon can confirm the TOSP classification of your planned operation before pre-admission. Always request this — it directly determines how much MediSave you can draw on.
Your 5-Step Year-End Decision Guide
Use this checklist to decide whether to book your elective surgery before December 31 or wait for 2027.
Step 1: Find Your Deductible Status
Log into your insurer’s policyholder portal — AIA, Income, Prudential, Great Eastern, Raffles Shield, AXA Shield, or HSBC Life — and look for “deductible paid” or “out-of-pocket tracking” for the current policy year. Alternatively, call your insurer’s customer service line and ask: “How much of my annual ISP deductible has been accumulated in 2026?”
Step 2: Confirm Your Plan’s Deductible Amount
Check whether your plan is targeted at Class B1, Class A, or a Private hospital. Use the table above: Class A/Private = $3,500, Class B1 = $2,500, Class B2 = $2,000. The applicable deductible is the lower of your plan’s target class and your actual ward class.
Step 3: Get a Bill Estimate
Contact your surgeon’s clinic or the hospital’s patient services team. Ask for a cost estimate letter that includes the TOSP classification and expected total bill. Most private hospitals in Singapore can provide a written estimate within 3–5 working days. This estimate is not binding but gives you a clear figure to run the calculation.
Step 4: Run the Timing Calculation
Using your figures: compare (remaining deductible) + 5% × (bill − remaining deductible) for December versus (full annual deductible) + 5% × (bill − full deductible) for January. If your deductible has been fully met, any December surgery saves you exactly the deductible amount compared to January.
Step 5: Check Your MediSave Balance
Your deductible and co-payment can be paid using MediSave. Log in to CPF digital services to check your Medisave balance before confirming your pre-admission date. If your balance is low, consider whether topping up your Medisave (up to the BHS of $79,000 for 2026) makes sense before the admission.
For a broader review of how to maximise your CPF before year-end, see our CPF investment strategy guide and the Singapore retirement planning calculator.
Review Your ISP Before Year-End
November is a good time to review not just your deductible status, but also whether your ISP still fits your needs. If you bought a rider after 1 April 2026, you are on the new framework — you hold the deductible responsibility. If you’re on a legacy rider, check the insurer’s migration timeline: from the first renewal after 1 April 2028, all policyholders must move to compliant riders.
For a full comparison of all seven ISP options in Singapore, including their deductible policies, panel doctor requirements, and premium changes, see our complete guide to the best Integrated Shield Plans in Singapore.
If you’re also planning your hospitalisation timeline for the November–December period, our Medisave limit 2026 November December planning guide covers the full pre-admission checklist and how to coordinate with your insurer in the final weeks of the year.
Beyond health insurance, keeping your savings working hard outside of Medisave matters too. If you’re parking emergency funds or medium-term savings while waiting for planned medical expenses, platforms such as Endowus (referral code: 2V343) and Syfe (referral code: SRPRFFFCD) offer CPF-integrated and cash management options that earn more than a standard bank account.
Frequently Asked Questions
Does the ISP deductible reset on the same date for everyone?
Can I use MediSave to pay my ISP deductible and co-payment?
What happens if my annual co-payment exceeds $6,000 in 2026?
Can I find out my TOSP classification before booking surgery?
If I have a legacy rider that covers my deductible, does the year-end timing still matter?
How do multiple hospital admissions in one year affect the deductible?
Get Free Insurance Advice
Speak with a licensed insurance advisor. No obligation, no cost.
By submitting this form, you agree to our Privacy Policy.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.