Medisave Limit 2026: Covering Cancer Treatment Costs With Your ISP
Why your Integrated Shield Plan rider is the most critical layer when cancer bills hit six figures
The Kopi Notes · October 2026
A cancer diagnosis in Singapore can mean bills of $98,000 to $273,000 over 18 months at a private hospital. Singapore’s Medisave limit 2026 covers only your daily ward and hospitalisation component — your Integrated Shield Plan (ISP) rider is what determines whether that bill is manageable or financially devastating. This guide breaks down exactly how each layer works together, with a real $184,000 breast cancer bill as a worked example.
Not financial advice. All figures are for educational reference only. Data verified as at October 2026 unless otherwise stated.
In This Article
- Why Cancer Bills Break Every Budget
- What the Medisave Limit 2026 Covers
- MediShield Life: The Foundation and Its Limits
- How Your ISP Bridges the Cancer Gap
- Worked Example: $184,000 Breast Cancer Bill
- Cancer Drug Treatment: Special Medisave Rules
- 5 Cancer Coverage Gaps to Watch
- Action Checklist: What to Do Now
- Frequently Asked Questions
Why Cancer Bills Break Every Healthcare Budget
Cancer is consistently Singapore’s most feared health event — and the treatment bills confirm why. Based on Singlife claims data, the total treatment costs over 18 months at a private hospital break down as follows:
| Cancer Type | Private Hospital (18 mths) | Drug Treatments Alone |
|---|---|---|
| Lung Cancer | ~$273,000 | ~$190,000 |
| Breast Cancer | ~$184,000 | ~$156,000 |
| Colorectal Cancer | ~$128,000 | ~$65,000 |
| Prostate Cancer | ~$98,000 | ~$87,000 |
Source: Singlife claims data via SmartWealth.sg, 2024. Private hospital, pre-subsidy figures. Public hospital subsidised costs are significantly lower.
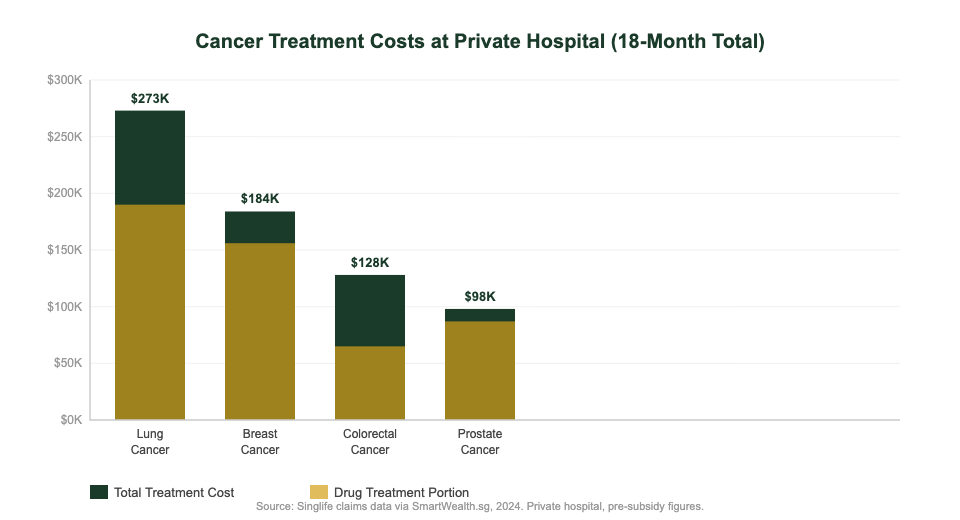
These numbers explain why an ISP is not optional for most Singapore households — it is the most important financial safety net you hold. But knowing which layer of protection covers which part of the bill is critical to avoiding nasty surprises at the hospital billing counter.
What the Medisave Limit 2026 Covers for Cancer Patients
The Medisave limit 2026 works differently for cancer treatment depending on whether you are receiving inpatient or outpatient care. Many patients assume Medisave covers their entire hospital bill — it does not.
Inpatient Hospitalisation Withdrawal Limits (2026)
When you are admitted to hospital for cancer surgery or inpatient treatment, Medisave can be withdrawn at these rates:
| Type of Care | Medisave Withdrawal Limit (2026) |
|---|---|
| Normal Ward (all classes A, B1, B2, C) | $700 per day |
| Intensive Care Unit (ICU) | $900 per day |
| Surgical Procedures (Table 7A/7B — complex surgery) | Up to $7,550 |
| Outpatient Cancer Drug Treatment | $600–$1,200 per month |
Source: CPF Board / sgfinancecalculators.com, as at 2026. Verify current figures at cpf.gov.sg.
Consider this: a 10-day private hospital stay for cancer surgery at $2,500 per day costs $25,000 in ward charges alone. Medisave covers $700 × 10 = $7,000 — just 28% of the ward bill. For the remaining $18,000, your MediShield Life and ISP must step in. This is precisely where the ISP co-payment mechanism determines your actual out-of-pocket exposure.
MediShield Life: The Foundation and Its Hard Limits
Every Singapore citizen and PR has MediShield Life as a baseline. Following the enhancements that took effect in April 2025, both the coverage limits and deductibles have increased significantly.
| MediShield Life Parameter | 2026 Amount |
|---|---|
| Annual Claim Limit | Up to $200,000 |
| Daily Ward Claim Limit (Normal) | $1,630 per day |
| ICU Claim Limit | $5,140 per day |
| Inpatient Deductible (Private Hospital) | $3,500 per policy year |
| Co-insurance (after deductible) | 3%–10% of remaining bill |
| Outpatient Deductible (from January 2026) | $500 per year (via Medisave) |
Source: DBS / MediShield Life Council enhancements, effective April 2025. Verify at moh.gov.sg/medishieldlife.
The critical insight: MediShield Life’s annual claim limit of $200,000 is substantial, but it only pays after you clear the deductible. For cancer patients at a private hospital, that $3,500 annual deductible resets every policy year — meaning if treatment spans two policy years, you pay $3,500 twice. This is one reason why understanding how the Medisave limit behaves across multiple hospitalisations is so important for cancer patients expecting ongoing treatment.
If you have ever questioned whether your ISP rider is worth the additional premium, a prolonged cancer treatment scenario is the definitive test case.
How Your ISP Bridges the Cancer Coverage Gap
An Integrated Shield Plan sits on top of MediShield Life and raises the coverage ceiling substantially. When you add an ISP rider — the optional cash-funded add-on — the financial picture for a cancer patient changes dramatically.
Here is what a comprehensive ISP with a full rider provides specifically for cancer treatment:
- Higher annual claim limits — most Class A/Private ISPs offer unlimited annual coverage or multi-million-dollar ceilings, compared to MediShield Life’s $200,000.
- Rider absorbs the annual deductible — the $3,500 you owe before MediShield Life pays is covered by full ISP riders (subject to 5%–10% co-payment).
- Daily ward benefit extended — MediShield Life claims $1,630/day on ward charges, but a private hospital room costs $3,000–$5,000/day. Your ISP base plan covers the gap.
- Cancer drug coverage up to 5× MediShield Life — ISP drug riders can pay up to five times what MediShield Life covers for approved cancer drugs on the Positive Drug List.
- Access to private oncologists — without ISP, private specialist fees are fully out-of-pocket. With an ISP covering private hospital class, specialist fees fall within plan limits.
The best ISP for comprehensive cancer protection in 2026 combines a strong base plan (Class A or Private) with a drug rider that covers positive-list drugs at minimal co-payment and a lifetime or annual limit high enough for multi-year treatment.
Worked Example: A $184,000 Breast Cancer Bill at a Private Hospital
Meet Rachel, 45, diagnosed with breast cancer. She chooses treatment at a private hospital and holds a Class A ISP with a full rider (e.g. AIA HealthShield Gold Max A with rider). Total 18-month bill: $184,000 — split between $28,000 inpatient surgery and ward costs, and $156,000 outpatient drug treatment (chemotherapy).
Coverage Breakdown for Rachel’s $184,000 Bill
| Coverage Layer | Amount Paid | Notes |
|---|---|---|
| MediShield Life | ~$18,500 | After $3,500 deductible; within annual claim limits |
| ISP Base Plan (top-up) | ~$6,000 | Covers gap between MediShield Life limits and actual bill |
| ISP Rider (deductible + co-ins + drugs) | ~$156,150 | Absorbs deductible and majority of drug treatment bills |
| Rachel pays (cash) | ~$3,350 | ~5–10% co-payment on rider portion only |
Illustrative example. Actual figures vary by hospital, room type, surgeon fees, drug protocol and plan terms. Data as at October 2026.
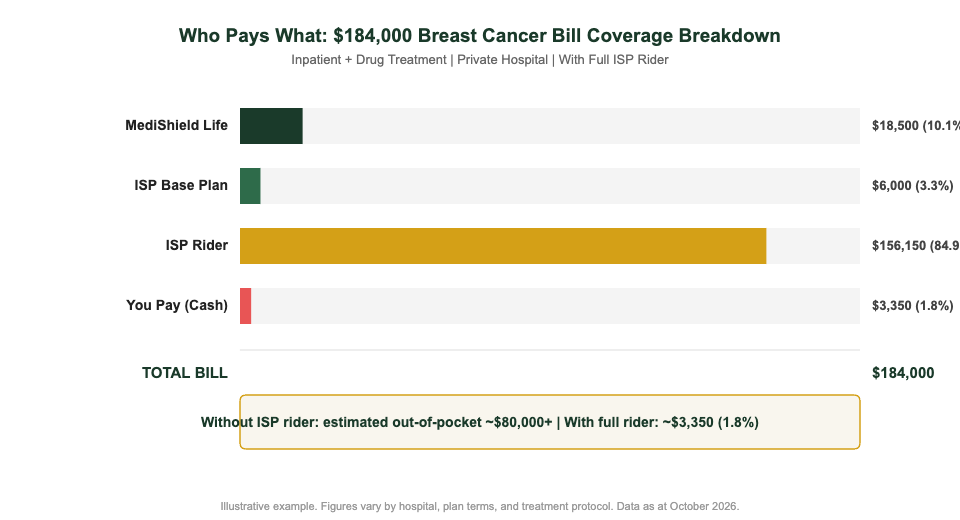
Net out-of-pocket for Rachel: approximately $3,350 over 18 months — versus an estimated $80,000 or more without an ISP rider. The rider is what collapses an otherwise catastrophic financial event into a manageable one.
For the step-by-step process of how to actually file an ISP claim when hospitalised at a private hospital, the ISP claim process guide for private hospitals walks through each stage from admission to final billing.
Cancer Drug Treatment: Special Medisave Rules for 2026
Outpatient cancer drug treatment follows different Medisave withdrawal rules from standard hospitalisation. These are among the least-understood rules in Singapore’s healthcare financing system, yet they matter enormously for cancer patients on long-term drug protocols.
Since the 2022 restructuring, cancer drugs are categorised on a Positive Drug List. The Medisave withdrawal limit per month depends on the drug’s MediShield Life claim limit tier:
- Drugs with MediShield Life claim limit above $5,400/month → Medisave withdrawal: $1,200/month
- Drugs with MediShield Life claim limit $5,400 or below/month → Medisave withdrawal: $600/month
- Cancer drug services (scans, blood tests, consultations): additional $600 per year from Medisave
From January 2026, a new $500/year outpatient deductible (payable via Medisave) applies to outpatient cancer treatment under MediShield Life. Most full ISP riders absorb this deductible, so check your policy documents.
For ISP policyholders, the cancer drug coverage under ISP is capped at up to 5× the relevant MediShield Life drug limit for each positive-list drug. Drugs NOT on the positive list are not covered by MediShield Life or ISP — they must be funded 100% from cash savings. Always ask your oncologist which drugs in your protocol are positive-list approved, and which are off-list.
For a full breakdown of how your Medisave balance is drawn down across all types of hospitalisation, see the Medisave hospitalisation coverage guide.
5 Cancer Coverage Gaps That Catch People Off-Guard
Even with a comprehensive ISP and full rider, cancer patients in Singapore routinely encounter unexpected costs. Here are the five most common gaps:
1. Off-label and non-positive-list drugs
Your oncologist may recommend a drug not on the Positive Drug List. Neither MediShield Life nor ISP covers it — you pay 100% in cash. These drugs can cost $10,000–$50,000 per cycle. Budgeting a cash reserve for this possibility is essential.
2. Pre- and post-hospitalisation outpatient consultations
Specialist consultations are typically covered only within a defined window (commonly 90 days before and 180 days after admission) under ISP. Bills outside this window are fully out-of-pocket.
3. ISP waiting periods for new diagnoses
Most ISPs have a 90-day waiting period for illness claims. If you are diagnosed within this window of purchasing or upgrading your plan, the cancer claim will be rejected. Always upgrade your ISP before any symptoms appear — never wait.
4. Rider co-payment must be paid in cash
The 5%–10% co-payment on your ISP rider must be paid in cash — Medisave cannot cover it. For a $184,000 bill, a 5% co-payment is $9,200 in cash. Budget for this separately from your Medisave balance.
5. Annual deductible resets each policy year
Cancer treatment often spans multiple years. Each policy year resets the deductible. A patient undergoing treatment from October 2026 to March 2027 crosses a policy year boundary and owes the deductible twice. Use your Singapore retirement planning calculator to model how your healthcare reserves track against multi-year treatment scenarios.
Action Checklist: Protect Your Coverage Before a Cancer Diagnosis
The best time to review your ISP is before you ever need it. Use this checklist today:
- ✅ Confirm you hold an ISP with a rider — not just base MediShield Life. Log into your insurer’s portal or call to verify your policy tier and rider status.
- ✅ Check your ISP ward class — Class A or Private Hospital is recommended for full flexibility in choosing your oncologist and hospital.
- ✅ Review your rider’s cancer drug coverage — does it cover positive-list drugs? At what co-payment percentage? Are there per-drug monthly limits?
- ✅ Know your Medisave balance — log in to CPF.gov.sg to check how much you have available for outpatient deductibles and inpatient withdrawals.
- ✅ Never let your ISP or rider lapse — reinstating after a lapse may require medical underwriting. A past cancer history creates exclusion clauses.
- ✅ Keep 6 months of cash reserve — for rider co-payments, non-positive-list drugs, and daily living expenses during treatment and recovery.
Frequently Asked Questions
Does MediShield Life cover all cancer drug treatments?
What is the Medisave withdrawal limit for outpatient chemotherapy in 2026?
Can I use Medisave to pay the ISP rider co-payment for cancer treatment?
Will my ISP cover cancer treatment at a private hospital?
What happens if my cancer treatment costs exceed my ISP annual limit?
Does my critical illness (CI) rider replace the need for an ISP during cancer treatment?
Key Takeaways: Medisave Limit 2026 and Cancer Treatment
- Private hospital cancer bills reach $98,000–$273,000 over 18 months. Medisave’s $700/day withdrawal limit covers only the ward component — a fraction of the total.
- MediShield Life’s 2026 annual claim limit is $200,000, but the $3,500 annual deductible must be cleared first, and it resets every policy year.
- An ISP with a full rider is what absorbs the deductible, extends annual coverage, and covers cancer drug treatments up to 5× MediShield Life limits.
- A new $500/year outpatient deductible (payable via Medisave) applies from January 2026 for cancer drug treatment under MediShield Life.
- Non-positive-list drugs, rider co-payments, and treatment beyond plan limits must come from cash savings — keep six months of reserves specifically for this.
This article is for general education only and does not constitute financial or medical advice. All figures are as at October 2026 and may change. Please consult a licensed financial adviser for personalised guidance on your ISP coverage needs.
Get Free Insurance Advice
Speak with a licensed insurance advisor. No obligation, no cost.
By submitting this form, you agree to our Privacy Policy.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.