UOB Fixed Deposit Rate (October 2026): Is 1.70% Worth It vs T-Bills at 1.95%?
With Singapore’s 6-month T-bill hitting a new 2026 high of 1.95% on 22 October, we break down exactly how UOB’s current promotional FD rates stack up — and who should still pick the FD.
UOB’s current fixed deposit promotion (23 September – 31 October 2026) offers up to 1.70% p.a. for a 12-month SGD fixed deposit with a minimum of S$10,000 in fresh funds. That’s a solid guaranteed rate — but Singapore’s 6-month T-bill just cut off at 1.95% on 22 October, a new 2026 high. Whether UOB FD or T-bills make more sense depends on four things: how much you’re depositing, whether you have a CDP account, your liquidity needs, and how comfortable you are with competitive bidding.
Not financial advice. All figures are for educational reference only. Data verified as at 25 October 2026.
UOB Fixed Deposit Rates: Full October 2026 Table
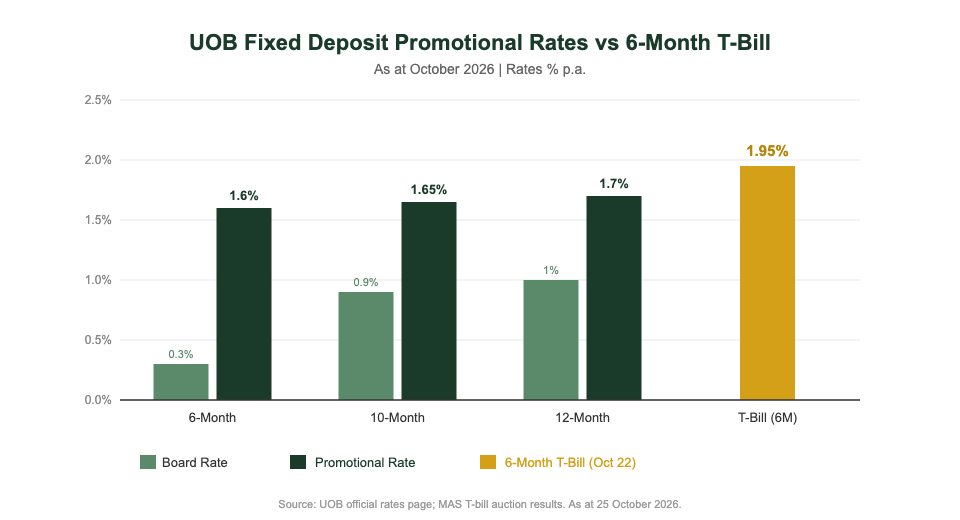
UOB’s promotional rates are available from 23 September to 31 October 2026 only — that’s 6 days left as of today. Here’s the full picture, showing both the “board rate” (what you get without the promotion) and the current promotional rate:
| Tenure | Board Rate | Promotional Rate | Verdict |
|---|---|---|---|
| 1–2 months | 0.05% p.a. | — | Skip |
| 3–5 months | 0.10–0.15% p.a. | — | Skip |
| 6 months ★ | 0.30% p.a. | 1.60% p.a. | Good |
| 7–9 months | 0.50–0.80% p.a. | — | Skip |
| 10 months ★ | 0.90% p.a. | 1.65% p.a. | Good |
| 12 months ★★ | 1.00% p.a. | 1.70% p.a. | Best UOB Rate |
| 13–36 months | 1.00% p.a. | — | Skip |
Source: UOB official rates page. Promotional rates valid 23 September – 31 October 2026. Board rates are indicative. ★ = promotional rate available.
Key conditions: Minimum S$10,000 per placement. Fresh funds required — cannot transfer from existing UOB accounts. Hold to full maturity or forfeit all interest. SDIC coverage up to S$100,000 per depositor. Early closure within 6 months incurs a S$30 fee.
UOB Fixed Deposit vs T-Bills: Side-by-Side Comparison
The 6-month Singapore T-bill auction on 22 October 2026 cut off at 1.95% p.a. — a new 2026 high, and 25 basis points above UOB’s best 12-month FD promotional rate. But rate alone doesn’t tell the full story:
| Factor | UOB 12M Fixed Deposit | 6-Month T-Bill |
|---|---|---|
| Current Rate | 1.70% p.a. | 1.95% p.a.* |
| Rate Certainty | ✅ Fixed at placement | ⚠️ Set at auction |
| Minimum Amount | S$10,000 | S$1,000 (multiples) |
| Account Required | UOB account | CDP + bank account |
| CPF-OA / SRS eligible | ❌ No (fresh funds only) | ✅ Yes |
| Tenor | 12 months fixed | 6 months (re-tender) |
| Early Exit | ❌ Forfeit interest + S$30 | ✅ Secondary market sale |
| Deposit Insurance | SDIC up to S$100k | Singapore Govt backed |
| Interest Taxes (SG) | Not taxable | Not taxable |
| Fresh Funds Needed | ⚠️ Yes (promo condition) | ✅ No restriction |
*T-bill rate from 22 October 2026 auction cut-off. Future rates may differ. Source: MAS, UOB. Data as at 25 October 2026.
How Much More Does the T-Bill Actually Pay?
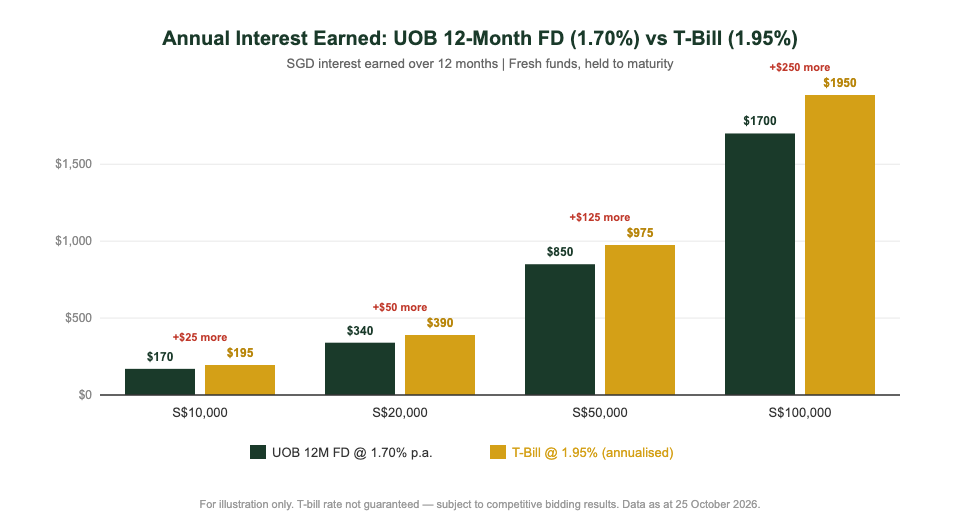
The 25 basis point yield gap between T-bills (1.95%) and UOB’s 12-month FD (1.70%) translates into real dollars. The table below compares annual interest assuming two 6-month T-bill rollovers at 1.95% vs one 12-month UOB FD at 1.70%:
| Deposit Amount | UOB FD @ 1.70% (12M) | T-Bill @ 1.95% (12M equiv.) | T-Bill Advantage |
|---|---|---|---|
| S$10,000 | S$170 | S$195 | +S$25 |
| S$20,000 | S$340 | S$390 | +S$50 |
| S$50,000 | S$850 | S$975 | +S$125 |
| S$100,000 | S$1,700 | S$1,950 | +S$250 |
For illustration only. T-bill rate assumes 1.95% sustained across two 6-month auctions — not guaranteed. Both instruments are non-taxable for Singapore residents. Data as at 25 October 2026.
At S$10,000, the T-bill earns just S$25 more per year — the cost of a hawker meal. At S$100,000, the gap is S$250: meaningful, but not transformative. The question is whether that extra yield justifies the added complexity of CDP setup, bidding, and the uncertainty of future auction rates.
When UOB Fixed Deposit Makes More Sense
1. You Don’t Have a CDP Account
Buying T-bills requires a Central Depository (CDP) account linked to a bank. Opening one takes days to weeks. If you need to deploy cash now and don’t have CDP access, UOB FD is the simpler, faster route. Our step-by-step guide on how to buy Singapore T-bills in 2026 covers the full setup process across DBS, OCBC, and UOB.
2. You Want a Rate Locked In Today
UOB FD locks in 1.70% the moment you place the deposit. T-bills require you to bid and accept the cut-off rate — which changes every two weeks at auction. If you believe rates are near a peak, locking in UOB’s FD gives certainty. One auction difference won’t be dramatic, but a sustained rate decline over 12 months could mean the T-bill roll strategy underperforms your locked-in FD rate.
3. You’re Already a UOB Customer with Outside Funds
If you already bank with UOB and have idle cash in DBS, OCBC, or Maybank, the UOB FD is minutes away via UOB TMRW. No new account, no CDP, no bidding portal. The fresh funds requirement turns what sounds like a restriction into an opportunity: it specifically rewards those who are already diversified across banks.
4. Your Sum Is S$10,000 to S$50,000
At S$10,000, the T-bill earns S$25 more per year. That translates to S$2.08 per month. For most savers, the time cost of CDP setup, non-competitive bid submissions, and monitoring the ATM queue twice a year isn’t worth S$25. At S$50,000, the advantage grows to S$125 — still modest for the added operational complexity. The T-bill’s edge becomes meaningfully large only above S$100,000.
When T-Bills Are the Better Choice
1. You Already Have CDP Set Up
For experienced T-bill buyers, the extra 25 bps is straightforward to capture. Using the non-competitive bid route (submitting without specifying a yield), you get a guaranteed allotment at the cut-off rate — currently 1.95%. With the next auction coming every two weeks, you can act quickly. Our T-bill vs SSB vs fixed deposit comparison covers the bidding process in detail.
2. You Want to Use CPF-OA or SRS Funds
UOB’s FD promotion requires fresh non-UOB cash. CPF-OA and SRS money doesn’t qualify. T-bills are fully eligible for CPF-OA and SRS subscriptions, and at 1.95%, they comfortably make sense as a short-term parking vehicle. See our guide on buying T-bills with CPF-OA and SRS for the step-by-step process.
3. You Have More Than S$100,000
SDIC covers only S$100,000 per depositor per institution. Above that, UOB FD exposure is uninsured. T-bills carry no such ceiling — they are direct Singapore government obligations. For sums above S$200,000, splitting across institutions is cumbersome; T-bills are the cleaner answer.
4. You Want Six-Month Liquidity Windows
The UOB 12-month FD locks you in fully — any early exit forfeits all interest and costs S$30. T-bills mature every 6 months, giving you a natural decision point. If your financial situation might change (unexpected expense, investment opportunity), the 6-month T-bill cycle is far more forgiving.
Our Recommendation
Pick UOB FD if: You already bank with UOB, you have S$10,000–S$100,000 in fresh (non-UOB) funds, you don’t have CDP set up, and you want a guaranteed 1.70% without any bidding process. The promotion ends 31 October 2026 — 6 days left.
Pick T-bills if: You already have CDP set up, you’re deploying above S$100,000, you want to use CPF-OA or SRS funds, or you want liquidity flexibility at the 6-month mark. At 1.95%, T-bills are the higher-yield option for those who can access them.
There’s also a third option worth considering: GXS Boost Pocket currently offers up to 2.00% p.a. for an 18-month lock-in — 30 bps above UOB and 5 bps above the latest T-bill, with no fresh funds requirement. We compared the two products in detail in our GXS Boost Pocket vs UOB Fixed Deposit October 2026 comparison.
For a full view of where every major Singapore bank stands on fixed deposits right now, see our regularly updated SGD fixed deposit rate comparison for 2026.
Frequently Asked Questions
What is the current UOB fixed deposit promotional rate in October 2026?
Is UOB fixed deposit better than T-bills right now?
Can I use CPF-OA or SRS money for the UOB FD promotion?
Can I use CPF-OA or SRS money for the UOB FD promotion?
What happens if I withdraw my UOB fixed deposit early?
When does the UOB FD promotion end?
How does the UOB 12-month FD compare to GXS Boost Pocket?
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.