How to Buy Singapore T-Bills in 2026: Step-by-Step Guide (DBS, OCBC, UOB)
Table of Contents
- What Are Singapore T-Bills?
- T-Bill Rates & Yields in 2026
- How to Buy T-Bills via DBS (Step-by-Step)
- How to Buy T-Bills via OCBC
- How to Buy T-Bills via UOB
- Using CPF-OA or SRS to Buy T-Bills
- Competitive vs Non-Competitive Bids: Which to Choose
- Allotment, Settlement & What Happens After
- Frequently Asked Questions
Singapore T-bills (Treasury Bills) are short-term government securities issued by the Monetary Authority of Singapore (MAS), available in 6-month and 1-year tenors. They are capital-guaranteed by the Singapore Government and currently offer a cut-off yield of around 1.95% p.a. (October 2026). Singapore investors can buy T-bills through DBS, OCBC, or UOB using cash, CPF-OA, or SRS funds — with zero transaction fees and a minimum bid of SGD 1,000.
Not financial advice. All figures are for educational reference only. Data as at October 2026 unless noted.
What Are Singapore T-Bills?
Singapore Treasury Bills (T-bills) are short-term debt securities issued by the Singapore Government through MAS. Unlike Singapore Savings Bonds (SSB), T-bills are sold at a discount and redeemed at face value — meaning you pay less upfront and receive the full face value at maturity. The difference is your return.
T-bills are available in two tenors: 6-month and 1-year. The 6-month T-bill is auctioned twice a month, while the 1-year T-bill is auctioned monthly. Both are considered among the safest investments available in Singapore, backed by the full faith of the Singapore Government.
Unlike the Singapore Savings Bonds guide which offers a step-up interest structure over 10 years, T-bills are a pure short-term instrument — ideal for parking emergency funds or short-term savings at competitive rates. For long-term wealth building, see our guide to passive income strategies in Singapore.
T-Bill Rates & Yields in 2026
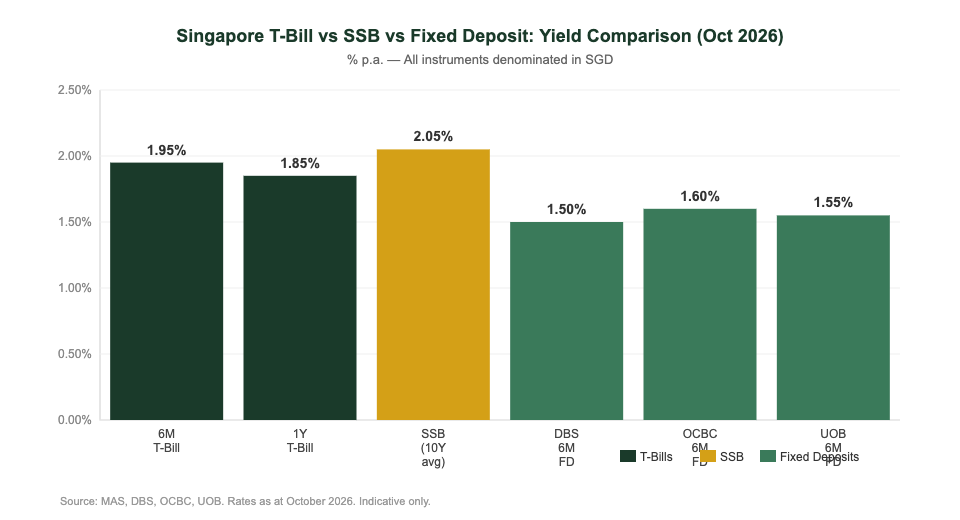
The cut-off yield for Singapore 6-month T-bills has been hovering in the 1.80–2.00% p.a. range through 2026, reflecting the lower global interest rate environment as central banks pivot from the rate hike cycle of 2022–2024. The most recent 6-month T-bill auction (October 2026) closed at a cut-off yield of 1.95% p.a.
Here’s how T-bills compare to other short-term savings options in Singapore as at October 2026:
| Instrument | Tenor | Rate (% p.a.) | Capital Guaranteed? | CPF/SRS Eligible? |
|---|---|---|---|---|
| 6-Month T-Bill | 6 months | 1.95% | Yes (SG Govt) | Yes |
| 1-Year T-Bill | 1 year | 1.85% | Yes (SG Govt) | Yes |
| SSB (10-yr avg) | Up to 10 yrs | 2.05% | Yes (SG Govt) | No |
| DBS 6M Fixed Deposit | 6 months | 1.50% | Yes (SDIC) | No |
| OCBC 6M Fixed Deposit | 6 months | 1.60% | Yes (SDIC) | No |
Source: MAS T-bill auction results, DBS/OCBC/UOB deposit rates. All rates as at October 2026 and subject to change.
How to Buy T-Bills via DBS (Step-by-Step)
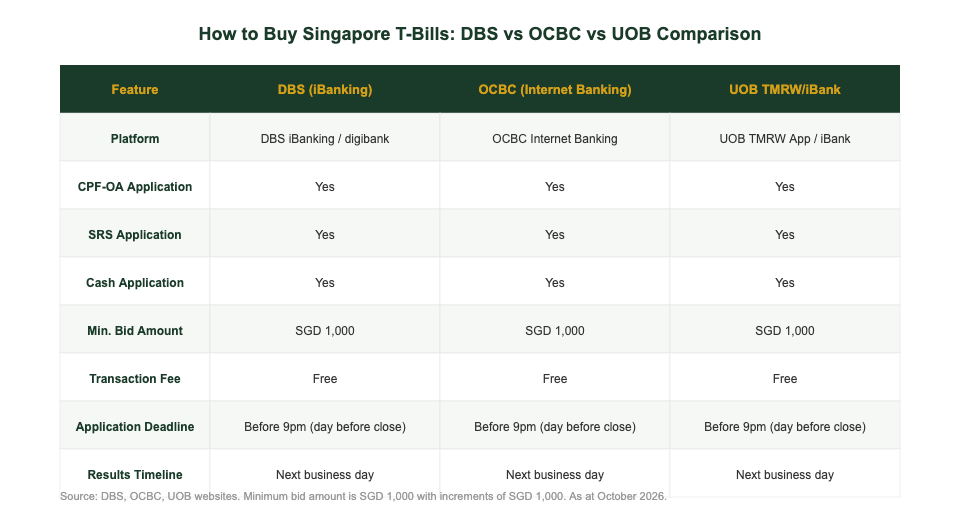
DBS is the most popular platform for buying Singapore T-bills, supporting applications via DBS iBanking (desktop) and the DBS digibank mobile app. Here’s the exact process:
DBS iBanking (Desktop)
- Log in to DBS iBanking
- Navigate to Invest → Bonds, T-Bills & SSB → Singapore T-Bills
- Select the tenor you want — 6-Month or 1-Year
- Choose your funding source: Cash, CPF-OA, or SRS
- Enter your bid amount (minimum SGD 1,000, multiples of SGD 1,000)
- Choose your bid type: Non-Competitive (recommended for most investors) or Competitive (enter a yield)
- Review and confirm your application
- Save your acknowledgement number as proof
DBS digibank App (Mobile)
- Open the DBS digibank app and log in
- Tap Invest in the bottom navigation
- Select Fixed Income & SSB
- Tap Singapore Government Securities → T-Bills
- Choose your tenor, funding source, and bid amount
- Review and submit. You’ll receive an SMS confirmation.
Important DBS deadline: Applications must be submitted before 9:00pm on the business day before the auction closes. Check the MAS website for the exact auction schedule. Results are typically released by the next business day.
How to Buy T-Bills via OCBC
OCBC Internet Banking supports T-bill applications for cash, CPF-OA, and SRS funds. The process is similar to DBS:
- Log in to OCBC Internet Banking
- Go to Invest → Singapore Savings & Bonds → T-Bills
- Select the current auction and your preferred tenor
- Choose your funding: Cash, CPF-OA, or SRS
- Enter bid amount (minimum SGD 1,000)
- Select Non-Competitive or Competitive bid
- Review terms, confirm and submit
- Note your reference number
OCBC also has a mobile banking app where you can apply. Navigate to Investments → Singapore Government Securities from the app menu.
How to Buy T-Bills via UOB
UOB supports T-bill applications through both the UOB TMRW app and UOB Personal Internet Banking:
UOB TMRW App
- Open UOB TMRW and tap Invest
- Select Singapore Government Securities
- Tap Apply next to the T-bill auction you want
- Choose tenor, funding source, and bid amount
- Select bid type and confirm
UOB Personal Internet Banking
- Log in at UOB Personal Internet Banking
- Click Investments → Singapore Government Securities & SSB
- Select the active T-bill auction
- Fill in bid details and submit before the 9pm deadline
Using CPF-OA or SRS to Buy T-Bills
One of the key advantages of Singapore T-bills over overseas ETFs is the ability to use CPF Ordinary Account (CPF-OA) or Supplementary Retirement Scheme (SRS) funds. This makes T-bills particularly valuable for retirement planning.
Buying T-Bills with CPF-OA
CPF-OA funds currently earn 2.5% p.a. interest. When T-bill yields are below 2.5%, using cash to buy T-bills and keeping CPF-OA untouched is more efficient. However, if you have excess CPF-OA above the required housing and insurance amounts, and T-bill yields are attractive, it may still make sense to invest.
To use CPF-OA: select “CPF-OA” as the funding source during the application on DBS, OCBC, or UOB. Your bank must be linked to your CPF account. You’ll need at least SGD 1,000 in investable CPF-OA (above the required savings).
See our comprehensive guide to CPF investment strategy in Singapore for a full breakdown of when to invest vs keep funds in OA.
Buying T-Bills with SRS
If you have SRS funds (typically from annual top-ups for tax relief), T-bills are one of the best options for deploying those funds productively. SRS money sitting in cash earns only 0.05% p.a. — parking it in T-bills at ~1.95% is a significant improvement.
To use SRS: during the T-bill application, select “SRS” as the funding source. Your SRS operator (DBS, OCBC, or UOB) will debit the funds from your SRS account on the application date.
Use our Singapore retirement calculator to see how T-bill investments within SRS can boost your retirement nest egg over time.
Competitive vs Non-Competitive Bids: Which to Choose?
When applying for T-bills, you must choose between two bid types. For most retail investors, the answer is clear:
| Bid Type | Who It’s For | Yield Received | Allotment Risk | Recommendation |
|---|---|---|---|---|
| Non-Competitive | Retail investors | Cut-off yield (market rate) | Low — guaranteed partial allotment up to SGD 1M | ✓ Recommended |
| Competitive | Institutions / Experienced investors | Your specified yield (may be lower than cut-off) | High — rejected if bid is above cut-off yield | Only if you have strong yield forecasting ability |
Source: MAS T-bill FAQ. Non-competitive bids are guaranteed allotment for amounts up to SGD 1,000,000 per auction per investor.
Key insight: A non-competitive bid means you accept whatever yield the market determines (the cut-off yield). You are guaranteed to receive T-bills at that rate, up to SGD 1 million. For competitive bids, if your stated yield is above the cut-off (meaning you demanded a higher yield), your bid is rejected and you receive nothing. This is the opposite of what many first-time investors expect.
For most Singaporeans investing SGD 1,000–50,000, always choose non-competitive bid. You’ll receive the cut-off yield regardless.
Allotment, Settlement & What Happens After
After submitting your T-bill application, here’s what to expect:
Auction day: MAS runs the auction and determines the cut-off yield based on competitive bids received. Non-competitive bids are allocated first, then competitive bids from lowest to highest yield until the total issue amount is filled.
Results announced: Auction results are typically published on the MAS website by the next business day. You can also check via your bank’s internet banking portal.
Settlement (2 business days later): If your bid is successful, the discounted purchase price is deducted from your account and the T-bill is credited to your CDP (Central Depository) account — or your CPF/SRS account if you used those funds.
At maturity: The face value (SGD 1,000 per unit) is credited back to your bank account, CPF-OA, or SRS account on the maturity date. No action required on your part.
For those building a systematic approach to savings and investing, check out our guide to the Singapore T-bills complete guide and compare T-bills with the best Syfe referral code for cash management alternatives that offer similar returns with daily liquidity.
If you’re using a robo-advisor for your broader portfolio, our Endowus referral code gives you SGD 20 off management fees when you start investing your cash, CPF, or SRS funds.
Frequently Asked Questions
What is the minimum amount to buy Singapore T-bills?
Can I buy T-bills without a CDP account?
What happens if my T-bill bid is not allotted?
Are Singapore T-bill returns taxable in Singapore?
How do I check my T-bill application status?
What is the difference between a T-bill and a Singapore Savings Bond (SSB)?
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.