GXS Bank Singapore (2026): Complete Guide — Accounts, Rates, FlexiLoan & Referral Code
Everything you need to know about Singapore’s MAS-licensed digital bank: savings rates, Boost Pockets, FlexiLoan, FlexiCard, and how to claim your referral bonus. Data verified as at 30 September 2026.
GXS Bank is a MAS-licensed Digital Full Bank in Singapore, jointly owned by Grab and Singtel. It offers a savings account with a 0.88% p.a. base rate (no minimum balance), Boost Pockets earning up to 1.75% p.a. on a 12-month fixed tenure, a personal loan (FlexiLoan) from 2.88% p.a. EIR 5.45% p.a., and a credit card (FlexiCard) with unlimited cashback. All GXS Bank deposits are SDIC-insured up to S$100,000 per depositor.
Not financial advice. All figures are for educational reference only. Data verified as at 30 September 2026 from GXS Bank official sources (gxs.com.sg) unless otherwise noted.
Table of Contents
- What Is GXS Bank Singapore?
- GXS Savings Account: Base Rate & Boost Pockets
- GXS FlexiLoan: Personal Loan Rates & Eligibility
- GXS FlexiCard: Cashback Credit Card
- Is GXS Bank Safe? (MAS Licence + SDIC)
- GXS Bank vs MariBank vs Trust Bank
- GXS Bank Referral Code (Earn Bonus)
- Verdict: Who Should Use GXS Bank?
- Frequently Asked Questions
1. What Is GXS Bank Singapore?
GXS Bank Pte Ltd is one of only four institutions in Singapore to have been awarded a Digital Full Bank (DFB) licence by the Monetary Authority of Singapore (MAS). The bank is a joint venture between Grab (Southeast Asia’s largest superapp) and Singtel (Singapore’s leading telecommunications group), and it commenced retail banking operations in 2023.
Being a Digital Full Bank means GXS is permitted to accept deposits from retail customers — the same regulatory category as DBS, OCBC, and UOB — but operates entirely online with no physical branch network. Its products are managed through the GXS app, available on iOS and Android.
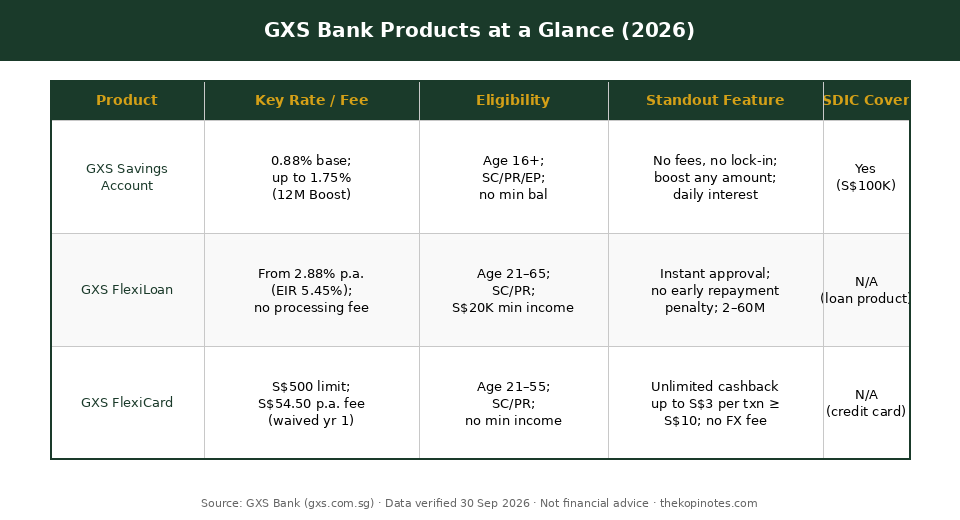
GXS focuses on three core products: a savings account with flexible Boost Pockets, a personal loan (FlexiLoan), and a credit card (FlexiCard). Unlike some neobanks, GXS does not currently offer a debit card with spending rewards, making it primarily a savings and credit product for Singaporeans who want a clean digital banking experience.
The bank’s backing by Grab and Singtel provides an added layer of institutional credibility and financial strength beyond what many standalone fintech startups offer. This has helped GXS build trust among Singapore consumers relatively quickly since its launch.
| Detail | Information |
|---|---|
| Full Name | GXS Bank Pte Ltd |
| Licence Type | MAS Digital Full Bank (DFB) |
| Shareholders | Grab Financial Group & Singtel |
| Retail Launch | 2023 |
| Products | Savings Account, FlexiLoan, FlexiCard |
| Deposit Insurance | SDIC up to S$100,000 per depositor per bank |
Source: MAS, GXS Bank official website. Data verified 30 Sep 2026.
2. GXS Savings Account: Base Rate & Boost Pockets
The GXS Savings Account is the bank’s flagship product and its most compelling offering for Singapore savers. Here is what makes it stand out.
Base Rate: 0.88% p.a.
The main account earns a 0.88% p.a. base interest rate, credited daily to your account. There is no minimum balance requirement, no minimum deposit to open, and no monthly service fee. Interest is calculated daily, which means your balance starts earning from day one.
Compared to the 0.05% p.a. most traditional banks offer on their basic savings accounts, GXS’s base rate is meaningfully higher — and without any salary crediting, bill payment, or card spend conditions attached.
Boost Pockets: Up to 1.75% p.a.
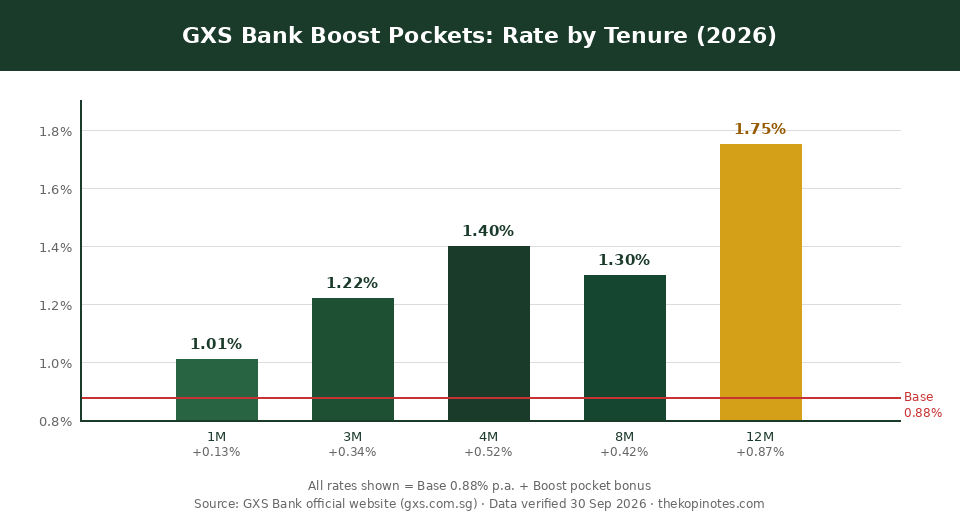
Boost Pockets let you lock a portion of your savings for a fixed term, earning a bonus rate on top of the base 0.88% p.a. You can have up to 8 Boost Pockets simultaneously, each with its own tenure and amount.
As of 30 September 2026, the Boost Pocket rates are:
| Tenure | Bonus Rate | Total Rate (Base + Bonus) |
|---|---|---|
| 1 Month | +0.13% p.a. | ~1.01% p.a. |
| 3 Months | +0.34% p.a. | ~1.22% p.a. |
| 4 Months | +0.52% p.a. | ~1.40% p.a. |
| 8 Months | +0.42% p.a. | ~1.30% p.a. |
| 12 Months | +0.87% p.a. | ~1.75% p.a. ★ Best Rate |
Source: GXS Bank (gxs.com.sg/savings-account). Data verified 30 Sep 2026. Boost Pocket rates may change; check the app for current rates before committing.
Note that the 4-month Boost Pocket (1.40%) currently offers better returns than the 8-month pocket (1.30%), so if you are comparing mid-term options, the 4-month tenure is the better deal at current rates.
Key Features of the GXS Savings Account
- No minimum balance — even S$1 earns 0.88% p.a.
- Daily interest crediting — you see interest accumulate every day, not just at month-end
- No lock-in on the main account — only your Boost Pocket funds are locked
- Up to 8 simultaneous Boost Pockets — ladder your savings across multiple tenures
- No fees — no account fee, no deposit fee, no withdrawal fee
- SDIC insured up to S$100,000 per depositor per bank
For Singapore savers looking for a simple, low-friction home for their emergency fund or short-term savings, GXS’s savings account is worth considering — especially if you do not want to jump through the hoops that bonus-rate accounts at traditional banks require.
If you want to compare how GXS stacks up against other high-yield options, our guide on Singapore Savings Bonds in 2026 and our Singapore T-bills 2026 guide give you the full picture on government-backed alternatives with higher rates.
3. GXS FlexiLoan: Personal Loan Rates & Eligibility
GXS FlexiLoan is a fully digital personal loan designed for Singapore Citizens and Permanent Residents. It stands out for its competitive promotional rate and complete absence of administrative fees.
GXS FlexiLoan Interest Rates
| Rate Type | Flat Rate (p.a.) | EIR (p.a.) |
|---|---|---|
| Promotional Rate | From 2.88% | From 5.45% |
| Standard Rate | 2.99% | 5.65% |
Source: GXS Bank (gxs.com.sg/flexiloan). Data verified 30 Sep 2026. Rates shown are illustrative; actual rate depends on creditworthiness.
The Effective Interest Rate (EIR) is the true cost of borrowing after accounting for compounding — always compare EIR when shopping for personal loans across banks. GXS’s 5.45% EIR promotional rate is competitive versus the market average of ~6–7% EIR for unsecured personal loans in Singapore.
GXS FlexiLoan Eligibility
- Age: 21–65 years old
- Citizenship: Singapore Citizen or Permanent Resident
- Minimum annual income: S$20,000
GXS FlexiLoan Key Features
- Loan tenure: 2 to 60 months — wide range suits short-term and medium-term needs
- No annual fee, no processing fee, no early repayment fee — full transparency
- No late payment charges — GXS does not charge a late fee (though interest continues to accrue)
- Balance Transfer available at 0% interest with a one-time processing fee
- Instant digital approval and disbursement — no physical paperwork
The absence of any processing fees is a genuine differentiator. At many traditional banks, a S$20,000 personal loan comes with a S$150–200 processing fee. GXS charges nothing beyond the interest itself.
For context on how personal loans fit into your broader financial picture, our guide on CPF investment strategy explains when you might want to pay down debt versus invest the difference.
4. GXS FlexiCard: Cashback Credit Card
GXS FlexiCard is a credit card designed with simplicity at its core. Its headline feature is unlimited instant cashback — but with a cap per eligible transaction that makes it most rewarding on mid-sized everyday spending rather than large purchases.
GXS FlexiCard Key Rates & Fees
| Feature | Detail |
|---|---|
| Credit Limit | S$500 |
| Annual Fee | S$54.50 (waived in Year 1) |
| Cashback | Up to S$3 per eligible transaction ≥ S$10 |
| Foreign Transaction Fee | None |
| Flexi Fee (pay later) | S$5/month (opt-in partial payment) |
| Minimum Income | None required |
Source: GXS Bank (gxs.com.sg/flexicard). Data verified 30 Sep 2026.
Understanding the FlexiCard Cashback
GXS FlexiCard offers unlimited cashback of up to S$3 per eligible transaction of S$10 or more. The “unlimited” part means there is no monthly cap on the number of transactions that qualify — which is rare among Singapore cashback cards that typically cap total monthly cashback at S$25–80.
The practical implication: the FlexiCard rewards you best on multiple smaller transactions (groceries, hawker PayNow, kopitiam coffees, public transport) rather than one large purchase. A S$3 cap per transaction means a S$3,000 purchase earns the same S$3 as a S$10 purchase.
The Flexi Fee: Interest-Free Option
The FlexiCard’s most unusual feature is its Flexi Fee model. Instead of charging interest (typically 27% p.a.) when you carry a balance, GXS lets you opt in to a flat S$5/month fee to pay just the minimum each month. This effectively replaces traditional credit card interest charges for those who occasionally need more time to pay.
GXS FlexiCard Eligibility
- Age: 21–55 years old
- Citizenship: Singapore Citizen or Permanent Resident
- No minimum income requirement
The low credit limit of S$500 makes this an approachable starter card for those building a credit history, or a supplementary card for small daily purchases alongside a higher-limit card from a traditional bank.
5. Is GXS Bank Safe?
This is the most common question from Singaporeans considering a digital bank: is my money safe? The short answer is yes — with important caveats to understand.
MAS Digital Full Bank Licence
GXS Bank holds a Digital Full Bank (DFB) licence issued by the Monetary Authority of Singapore (MAS). This is the highest category of banking licence MAS issues. It places GXS under exactly the same regulatory framework as DBS, OCBC, and UOB, including capital adequacy requirements, liquidity coverage rules, and MAS supervisory oversight.
Only four institutions received DFB licences in Singapore’s 2022 digital banking initiative: GXS Bank and Trust Bank (from Singapore; serving retail customers) and two Wholesale Digital Banks (serving business customers only). The rigour of MAS’s licensing process is globally respected.
SDIC Deposit Insurance
GXS Bank deposits are protected by the Singapore Deposit Insurance Corporation (SDIC), up to S$100,000 per depositor per bank. This means if GXS Bank were ever to fail, your first S$100,000 in deposits would be returned to you by the SDIC within a specified timeframe.
Practically: if you keep S$60,000 across your GXS main account and Boost Pockets, all of it is insured. If you have S$150,000, only the first S$100,000 is protected — the remaining S$50,000 carries the same risk as an uninsured bank deposit anywhere.
Grab + Singtel Backing
GXS is backed by two of Southeast Asia’s strongest institutions. Singtel’s market capitalisation exceeds S$30 billion and it has been listed on the SGX since 1993. Grab is publicly listed on NASDAQ and is the dominant superapp across the region. Neither is a startup without resources — this provides additional comfort beyond the regulatory protections alone.
Bottom line: GXS Bank is as safe as any other MAS-licensed bank in Singapore for deposits up to S$100,000. For amounts above S$100,000, consider splitting across banks to maximise SDIC coverage — as you would with DBS, OCBC, or any other bank.
6. GXS Bank vs MariBank vs Trust Bank (2026)
Singapore now has two retail Digital Full Banks — GXS and Trust Bank — plus MariBank (a Qualifying Full Bank licence from MAS, owned by Sea Limited / Shopee). Here is how they compare on savings rates, accessibility, and product range.
| Feature | GXS Bank | MariBank | Trust Bank |
|---|---|---|---|
| MAS Licence | Digital Full Bank | Qualifying Full Bank | Digital Full Bank |
| Base Savings Rate | 0.88% p.a. | 2.88% p.a. (standard) | Up to 2.5%+ with conditions |
| Top Savings Rate | 1.75% p.a. (12M Boost) | Up to 3.28% (qualifying txns) | Varies by spend tier |
| Min Balance | None | None | None for base |
| Personal Loan | FlexiLoan from 2.88% p.a. | MariBank Loan available | Trust Personal Loan |
| Credit Card | FlexiCard (S$3 cashback/txn) | No card currently | Trust Card (cashback/miles) |
| SDIC Cover | Yes (S$100K) | Yes (S$100K) | Yes (S$100K) |
| Best For | Fee-free savings + loan without conditions | High savers who qualify for top rates | FairPrice shoppers & cashback card users |
Sources: GXS Bank, MariBank, Trust Bank official websites. Rates are indicative and subject to change. Data verified 30 Sep 2026. Not financial advice.
The Verdict on Comparison
GXS’s base savings rate of 0.88% p.a. is lower than MariBank’s headline 2.88% — but MariBank’s higher rates come with qualifying transaction requirements. GXS wins on simplicity and product breadth (it is the only digital bank offering both a competitive personal loan and a credit card). Trust Bank wins for FairPrice shoppers and those who want a richer cashback card experience.
Many Singapore savers use two or more of these accounts simultaneously — the lack of minimum balance requirements means there is no cost to keeping them all open.
For building long-term wealth beyond savings accounts, explore our guides on passive income in Singapore and Singapore retirement planning.
7. GXS Bank Referral Code: YONG477
When signing up for GXS Bank, you can enter a referral code to receive a welcome bonus. Use referral code YONG477 when registering for your GXS account to unlock your referral reward.
To apply the code: open the GXS app → tap Sign Up → complete your identity verification → enter YONG477 in the referral code field during account setup.
Referral bonus terms and amounts are determined by GXS Bank and may change. Check the GXS app for current referral terms at the time of sign-up.
8. Verdict: Who Should Use GXS Bank?
GXS Bank is a well-rounded digital banking option for Singaporeans who want simplicity, zero fees, and regulatory peace of mind. Here is who it suits best — and who might be better served elsewhere.
GXS Bank Is a Good Fit If You:
- Want a fee-free savings account that earns meaningful interest without salary crediting or spend conditions
- Are building an emergency fund and want daily interest on any balance
- Need a fixed-term savings option (Boost Pockets) with competitive rates for 1–12 months
- Are looking for a personal loan with no processing fees and a genuinely transparent interest rate
- Want a starter credit card with no minimum income requirement and a simple cashback model
- Are already a Grab user and want to integrate banking into your existing financial apps
Consider Alternatives If You:
- Want the highest possible savings rate — MariBank currently leads on headline rates with qualifying conditions, and Singapore T-bills offer higher risk-free returns
- Need a high credit limit card — GXS’s S$500 limit is low for large-ticket spending
- Want investment products integrated in one app — GXS has GXS Invest but it is still developing its investment product range
- Prefer face-to-face service — GXS is digital-only
Our Syfe referral code guide and Endowus referral code guide are useful reads if you are looking to put your savings to work in a robo-advisory platform once your emergency fund is sorted.
For a brokerage to invest your savings in ETFs or REITs, the moomoo Singapore review covers one of the most popular low-cost platforms for Singapore retail investors.
9. Frequently Asked Questions
Is GXS Bank licensed by MAS?
Yes. GXS Bank Pte Ltd holds a Digital Full Bank (DFB) licence issued by the Monetary Authority of Singapore (MAS). This is the same regulatory category as Singapore’s traditional banks (DBS, OCBC, UOB), and subjects GXS to MAS capital adequacy and supervisory requirements.
Are GXS Bank deposits insured?
Yes. GXS Bank deposits are insured by the Singapore Deposit Insurance Corporation (SDIC) up to S$100,000 per depositor per bank. This means if GXS Bank were to fail, you would receive back up to S$100,000 of your deposits from the SDIC.
What is the highest rate I can earn with GXS Bank?
As of 30 September 2026, the highest rate available is 1.75% p.a. via a 12-month Boost Pocket (0.88% base + 0.87% bonus). This requires locking funds for 12 months. The main account earns 0.88% p.a. with no conditions or lock-in.
Can I withdraw money from a Boost Pocket early?
Boost Pockets are fixed-term — once you lock funds for a selected tenure (e.g. 3 months, 12 months), the money is generally not accessible until maturity. Check the GXS app’s terms for the latest early withdrawal policy, as this can change. Only funds in your main GXS Savings Account are freely accessible at any time.
What is the GXS Bank referral code?
The referral code for The Kopi Notes readers is YONG477. Enter it during GXS account sign-up to claim your referral reward. Referral bonuses are set by GXS Bank and are subject to change — check the app at the time of registration for current terms.
Does GXS FlexiLoan charge any processing fees?
No. GXS FlexiLoan has no annual fee, no processing fee, no early repayment fee, and no late payment fee. You pay only the interest on the outstanding principal. This makes it genuinely more transparent than many traditional bank personal loans that include processing fees of S$100–200.
Who is eligible for the GXS FlexiCard?
The GXS FlexiCard is open to Singapore Citizens and Permanent Residents aged 21–55. Notably, there is no minimum income requirement, making it accessible to self-employed individuals, part-time workers, or those in their first job. The credit limit is S$500.
The Kopi Notes provides personal finance education for Singapore investors. This article is for informational purposes only and does not constitute financial advice. All figures verified as at 30 September 2026. Rates and terms are subject to change — always verify directly with GXS Bank before making financial decisions. The Kopi Notes may earn referral fees from sign-ups using our referral codes.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.