GXS Bank Savings Account Rates (September 2026): Boost Pockets Now at 1.75% p.a.
Full breakdown of Main Account, Saving Pockets, and Boost Pocket rates — plus the new Save & Invest promotion at up to 3.2% p.a. Data verified as at 26 September 2026.
GXS Bank is a Singapore digital bank offering a savings account with no minimum balance and no lock-in conditions on its main tier. In September 2026, GXS Boost Pockets now pay up to 1.75% p.a. on a 12-month tenure — up from a previous maximum of 1.30% p.a. — while a new Save & Invest promotion offers up to 3.2% p.a. when combined with qualifying GXS Invest fund investments.
Not financial advice. All figures are for educational reference only. Data verified as at 26 September 2026 from GXS Bank official sources.
Table of Contents
Contents — Click to expand
- What’s Changed: GXS Rates in September 2026
- GXS Main Account: 0.88% p.a.
- GXS Saving Pockets: Now 1.2% p.a. (Promotional)
- GXS Boost Pockets: Up to 1.75% p.a.
- GXS Save & Invest Promotion: Up to 3.2% p.a.
- GXS vs Other Digital Banks (September 2026)
- GXS Bank Referral Code
- Is GXS Still Worth It? Our Verdict
- Frequently Asked Questions
What’s Changed: GXS Bank Rates in September 2026
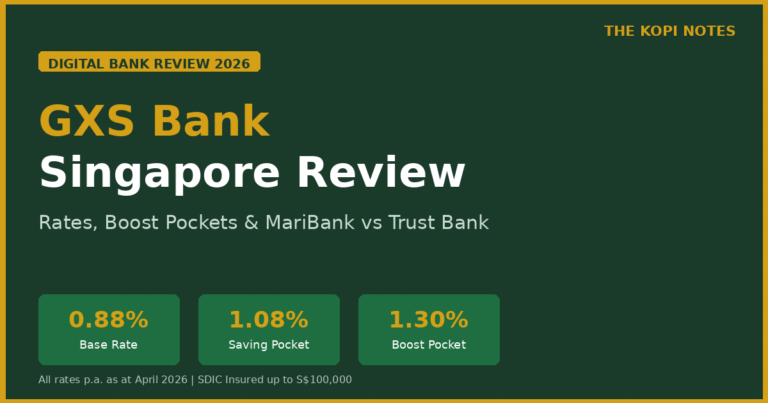
When we published our GXS Bank review in April 2026, the best rate you could get without a lock-in was 1.08% p.a. on Saving Pockets, or up to 1.30% p.a. on 8-month Boost Pockets. Since then, GXS has meaningfully updated its rates — and introduced a brand-new promotional product.
Here’s a side-by-side comparison of the old and new rates:
| Product | April 2026 Rate | September 2026 Rate | Change |
|---|---|---|---|
| Main Account | 0.88% p.a. | 0.88% p.a. | No change |
| Saving Pockets | 1.08% p.a. | 1.2% p.a. (promo) | +0.12% |
| Boost Pockets (max) | 1.30% p.a. (8-month) | 1.75% p.a. (12-month) | +0.45% |
| Save & Invest Promo | Not available | Up to 3.2% p.a. | New product |
Source: GXS Bank official website (gxs.com.sg), verified 26 September 2026.
The standout change is Boost Pockets. The previous maximum was 1.30% on an 8-month tenure. GXS has now added a 12-month tenure that reaches 1.75% p.a. — a 45 basis point increase on the headline rate. For savers comfortable locking away funds for a year, this meaningfully changes the value proposition compared to six months ago.
GXS Main Account: 0.88% p.a.
The GXS Main Account remains at 0.88% p.a. with daily interest crediting — unchanged since April 2026. There is no minimum balance requirement and no conditions to meet. Interest is calculated daily and paid into your account each day.
At 0.88% p.a., the Main Account is best suited for emergency funds or money you need instant access to at any moment. It is not competitive against fixed deposits, T-bills, or even GXS’s own Saving Pockets. If you have funds sitting idle in the Main Account for more than a few days, moving them to a Saving Pocket gives you an immediate rate improvement with zero lock-in.
For context, if you hold S$10,000 in the GXS Main Account for a full year, you earn approximately S$88 in interest before tax. Moving the same amount to a 12-month Boost Pocket at 1.75% p.a. would return approximately S$175 — nearly double. You can model the long-term impact of these rate differences using our Singapore retirement planning calculator.
GXS Saving Pockets: Now 1.2% p.a. (Promotional)
Saving Pockets currently earn 1.2% p.a. under a limited-time promotional rate, up from the standard 1.08% p.a. Interest is credited daily, and there is no lock-in — you can withdraw funds from a Saving Pocket at any time without penalty.
Saving Pockets are GXS’s most flexible savings product. You can create multiple named pockets within the app (for example, “Holiday Fund”, “Emergency Buffer”) and track them separately. The 1.2% rate applies across all Saving Pockets.
The key trade-off versus Boost Pockets: Saving Pockets offer full liquidity at a lower rate. If you might need to access funds within the next few months, Saving Pockets are the right choice. If you can commit for a fixed term, Boost Pockets offer meaningfully higher rates.
Note: The 1.2% promotional rate may revert to 1.08% once the promotion ends. Check GXS Bank’s official rates page for the current Saving Pocket rate before making decisions.
GXS Boost Pockets: Up to 1.75% p.a.
Boost Pockets are GXS’s fixed-term savings product. You commit a lump sum for a chosen tenure, and at maturity you receive your principal plus a bonus interest payment. The total rate is your base rate (0.88%) plus a tenure-specific bonus.
Here are all current Boost Pocket rates by tenure:
| Tenure | Base Rate | Bonus at Maturity | Total Rate (p.a.) | S$10,000 Earns |
|---|---|---|---|---|
| 1 month | 0.88% | 0.13% | 1.01% p.a. | ~S$8.40 |
| 3 months | 0.88% | 0.34% | 1.22% p.a. | ~S$30.50 |
| 4 months | 0.88% | 0.52% | 1.40% p.a. | ~S$46.70 |
| 8 months | 0.88% | 0.42% | 1.30% p.a. | ~S$86.70 |
| 12 months | 0.88% | 0.87% | 1.75% p.a. ★ Best Rate | ~S$175.00 |
Source: GXS Bank official website (gxs.com.sg/savings-account), verified 26 September 2026. S$10,000 interest figures are approximate, calculated on a simple annual basis for comparison. Actual returns may vary.
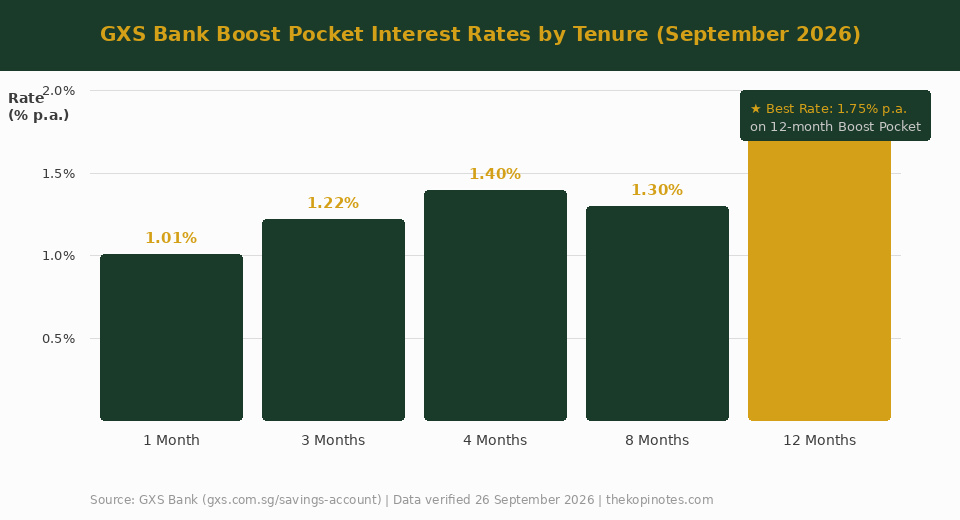
A few observations worth noting:
The 8-month pocket is anomalous. At 1.30% p.a., the 8-month tenure actually pays less than the 4-month option (1.40% p.a.), and significantly less than the 12-month option (1.75% p.a.). Unless you have a specific need for an 8-month maturity, either the 4-month or 12-month tenure will serve you better on a rate basis.
The 12-month rate is genuinely competitive for a no-conditions account. Most banks that offer 1.75%+ p.a. require salary crediting, minimum card spend, or other engagement criteria. GXS asks for none of these — you simply deposit into a 12-month Boost Pocket and earn 1.75% p.a. without further action. For those comparing against Singapore T-bills, the 12-month Boost Pocket competes reasonably well in the current environment, particularly given the S$500 minimum deposit (versus S$1,000 for T-bills).
GXS Save & Invest Promotion: Up to 3.2% p.a.
This is the new addition that changes the calculus for investors who also want market exposure. GXS’s Save & Invest promotion (running through September 2026) offers a significantly elevated rate when you combine a Boost Pocket deposit with an investment in qualifying GXS Invest funds.
| Tier | Boost Pocket Amount | GXS Invest Amount | Effective Rate (p.a.) |
|---|---|---|---|
| Tier 1 | S$5,000+ | S$5,000+ | 3.0% p.a. |
| Tier 2 | S$5,000+ | S$10,000+ | 3.2% p.a. |
Source: GXS Bank Save & Invest promotion terms, September 2026. Rate applies to the Boost Pocket deposit only. Check gxs.com.sg for current promotion validity.
Important caveats to understand before committing: The elevated rate (3.0% or 3.2% p.a.) applies to the Boost Pocket portion of your funds. The GXS Invest portion is invested in fund products that carry market risk — their returns are not guaranteed, and you may receive back less than you invested.
This promotion may appeal to those already planning to invest in GXS Invest funds who want to maximise returns on their cash component simultaneously. For pure savings without investment exposure, the 12-month Boost Pocket at 1.75% p.a. remains the better benchmark. Those considering the Save & Invest route should weigh their risk tolerance and compare against other passive income options in Singapore that also blend fixed and variable returns.
GXS vs Other Digital Banks (September 2026)
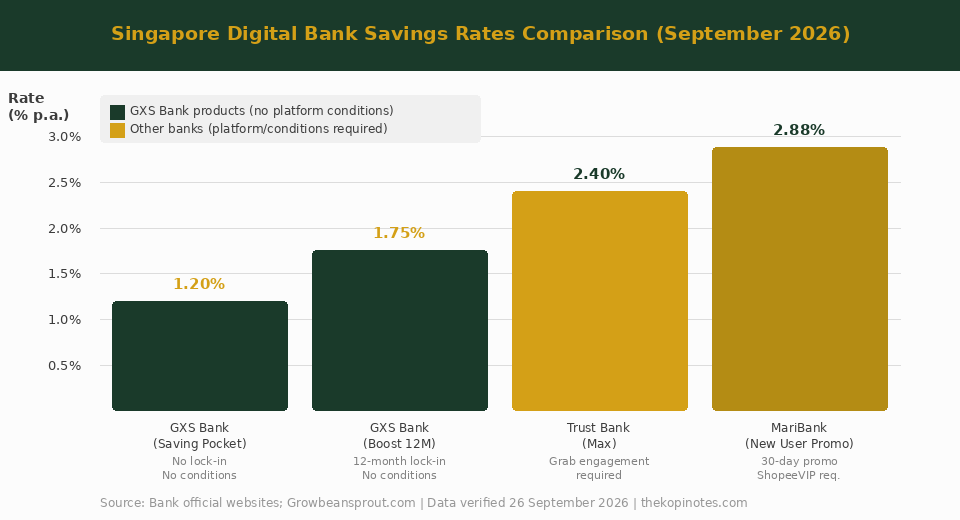
How does GXS stack up against MariBank and Trust Bank — Singapore’s other major digital banks — in September 2026?
| Bank | Best Rate | Conditions | Lock-in? | Minimum |
|---|---|---|---|---|
| GXS Bank (Boost Pocket) | 1.75% p.a. | None | Yes (12 months) | S$500 |
| GXS Bank (Saving Pocket) | 1.2% p.a. (promo) | None | No | S$1 |
| MariBank | 0.88% p.a. standard Up to 2.88% (new users, 30 days) |
ShopeeVIP required for promo | No | S$0 |
| Trust Bank | Up to 2.40% p.a. | Tiered based on Grab engagement | No | S$0 |
Source: Individual bank official websites; Growbeansprout.com savings comparison. Verified 26 September 2026. Rates subject to change without notice.
The key differentiator for GXS is the absence of conditions. Both MariBank and GXS start at the same 0.88% p.a. base rate. But GXS’s Boost Pockets let any customer earn 1.75% p.a. without needing to be a Shopee or Grab user, credit a salary, or make minimum card transactions.
Trust Bank’s maximum of 2.40% p.a. and MariBank’s 30-day new-user promo of 2.88% both exceed GXS’s 1.75% headline. However, those rates come with platform dependency — you need to be an active Grab user (Trust Bank) or a ShopeeVIP Shopee user (MariBank) to access the top tiers. GXS’s proposition is for savers who want straightforward fixed-term returns without bundling with a ride-hailing or e-commerce platform.
For those building an emergency fund or comparing all options, also consider non-digital alternatives. Singapore Savings Bonds offer competitive long-term rates with monthly liquidity and government backing — worth comparing against any GXS Saving Pocket allocation.
GXS Bank Referral Code (September 2026)
If you’re opening a new GXS Bank account, use referral code YONG477 to potentially unlock sign-up bonuses. Referral promotions are updated periodically — check the GXS app for current new-user terms when signing up. You can also read our full GXS Bank review for a comprehensive look at the account’s features, limits, and what you can expect as a new user.
Is GXS Still Worth It? Our Verdict
The September 2026 rate changes make GXS Bank a more compelling option than it was six months ago, particularly for savers willing to commit to a 12-month Boost Pocket. Here is our practical take for different saver profiles:
For emergency funds (high liquidity needed): GXS Saving Pockets at 1.2% p.a. are decent for money you may need to access at any time. However, if you want slightly better returns with monthly liquidity, Singapore Savings Bonds remain worth comparing side-by-side.
For surplus cash with a 12-month time horizon: The 12-month Boost Pocket at 1.75% p.a. with no conditions is a genuine competitive option. You don’t need to be on Grab or Shopee, and there’s no salary crediting requirement. The S$500 minimum deposit makes it accessible for most savers.
For Grab and Shopee users: Trust Bank and MariBank respectively may offer better headline rates if you are already engaged on those platforms. Compare your actual achievable rate — not just the advertised maximum — before committing.
For investors who also want to save: The Save & Invest promotion at up to 3.2% p.a. is worth considering, but only if you were already planning to invest in GXS funds. Do not invest in market products purely to unlock a savings rate bonus unless you are genuinely comfortable with the investment risk involved. Those seeking structured long-term wealth-building may also find value in reviewing a CPF investment strategy to complement any cash savings.
Overall: GXS has improved its positioning in 2026 without abandoning its core no-conditions proposition. For savers who value simplicity and guaranteed returns without platform dependencies, GXS Boost Pockets now offer genuine value at the 12-month tier.
Frequently Asked Questions
What is the GXS Bank savings account interest rate in September 2026?
GXS Bank offers three savings tiers in September 2026: the Main Account at 0.88% p.a. (daily crediting, no lock-in), Saving Pockets at 1.2% p.a. under a current promotional rate (daily crediting, no lock-in), and Boost Pockets at 1.01% to 1.75% p.a. depending on tenure (1 to 12 months). The highest rate — 1.75% p.a. — requires a 12-month Boost Pocket commitment with a minimum deposit of S$500.
What is GXS Bank's Boost Pocket rate?
GXS Boost Pocket rates vary by tenure: 1-month (1.01% p.a.), 3-month (1.22% p.a.), 4-month (1.40% p.a.), 8-month (1.30% p.a.), and 12-month (1.75% p.a.). The 12-month option offers the highest rate. All Boost Pocket rates combine a 0.88% base rate with a tenure-specific bonus interest paid at maturity.
Is there a lock-in period for GXS Bank savings?
It depends on the product. GXS Main Account and Saving Pockets have no lock-in — you can deposit and withdraw at any time. GXS Boost Pockets have a fixed tenure (1, 3, 4, 8, or 12 months). During a Boost Pocket’s tenure, your funds are locked in. If you withdraw early, you will not receive the bonus interest portion; only the base 0.88% p.a. rate may apply. Check GXS’s terms for the exact early redemption policy.
How does GXS Bank compare to MariBank and Trust Bank?
As at September 2026: GXS offers up to 1.75% p.a. (12-month Boost Pocket, no conditions required). Trust Bank offers up to 2.40% p.a. with Grab engagement tiers. MariBank offers 0.88% p.a. standard, or up to 2.88% p.a. for new ShopeeVIP users in the first 30 days. GXS’s advantage is simplicity — no platform dependency is required to earn the headline rate.
What is GXS Bank's Save and Invest promotion?
The GXS Save & Invest promotion (valid through September 2026) offers an elevated Boost Pocket rate of 3.0% to 3.2% p.a. when you simultaneously invest in qualifying GXS Invest funds. Tier 1 requires a minimum S$5,000 Boost Pocket deposit plus S$5,000 in GXS Invest (earning 3.0% p.a. on savings). Tier 2 requires S$5,000 Boost Pocket plus S$10,000 in GXS Invest (earning 3.2% p.a.). The investment component carries market risk and is not guaranteed.
What is the GXS Bank referral code?
The referral code for GXS Bank is YONG477. Enter this when signing up for a new GXS Bank account. Referral bonuses vary by promotion period — check the GXS app at the time of sign-up for current new-user offers.
Is GXS Bank safe? Is it MAS-regulated?
Yes. GXS Bank Pte. Ltd. holds a Digital Full Bank (DFB) licence issued by the Monetary Authority of Singapore (MAS), allowing it to serve retail customers. Deposits are protected by the Singapore Deposit Insurance Corporation (SDIC) up to S$100,000 per depositor. GXS Bank is a joint venture between Grab and Singtel. For more information, see the MAS website and SDIC website.
The Kopi Notes is an independent Singapore personal finance blog. This article is for educational and informational purposes only and does not constitute financial advice. Always verify current rates at the official GXS Bank website (gxs.com.sg) before making financial decisions. Data verified as at 26 September 2026. Rates are subject to change at the bank’s discretion.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.