OCBC 360 Interest Rate (November 2026): Every Bonus Tier and What You Really Earn
The six OCBC 360 bonus categories, the limited-time Save promo running to 31 December 2026, what S$20,000 to S$250,000 actually earns, and when the account stops being worth the effort.
The OCBC 360 interest rate in November 2026 is a 0.05% p.a. base rate plus bonuses on your first S$100,000: Salary (1.25% effective), Save (0.40%, or 0.65% under a promo to 31 December 2026), Spend (0.25%), Insure (1.25%), Invest (1.25%) and Grow (1.20% if your balance is at least S$250,000). Most salaried savers can realistically earn 1.70% to 1.95% p.a.; the headline maximum is 4.45%, or 4.70% during the Save promo.
Not financial advice. All figures are for educational reference only. Data verified as at 15 November 2026 against OCBC’s official 360 Account page and the 360 Account Save Bonus Promotion (August 2026) terms. Banks can change rates at any time.
Table of Contents
Contents — Click to expand
- OCBC 360 Interest Rate Table (November 2026)
- How to Qualify for Each OCBC 360 Bonus
- The 0.65% Save Bonus Promotion (to 31 Dec 2026)
- How Much Interest Will You Actually Earn?
- Is the 4.70% OCBC 360 Maximum Realistic?
- Fees, Eligibility and the New-Customer Offer
- OCBC 360 vs Other Places to Park Cash
- Is the OCBC 360 Account Worth It?
- Frequently Asked Questions
OCBC 360 Interest Rate Table (November 2026)
The OCBC 360 Account is OCBC’s flagship “do more, earn more” savings account. Instead of one flat rate, you earn a tiny base rate on everything and then stack bonus interest each month for every category you meet. Bonuses are paid only on the first S$100,000 of your balance, split into two slices: the first S$75,000 and the next S$25,000. The second slice usually earns double, which is why OCBC quotes an “effective” rate across the full S$100,000.
These are the rates shown on the official OCBC 360 Account page and in the 360 Account Save Bonus Promotion terms, both checked on 15 November 2026:
| Bonus category | First S$75,000 | Next S$25,000 | Effective rate on first S$100,000 |
|---|---|---|---|
| Salary | 1.00% | 2.00% | 1.25% |
| Save (standard) | 0.40% | 0.40% | 0.40% |
| Save (promo, 1 Aug to 31 Dec 2026) | 0.50% | 1.10% | 0.65% |
| Spend | 0.25% | 0.25% | 0.25% |
| Insure | 1.00% | 2.00% | 1.25% |
| Invest | 1.00% | 2.00% | 1.25% |
| Grow (balance of S$250,000 or more) | 1.20% | 1.20% | 1.20% |
| Base interest | 0.05% on the whole balance | 0.05% | 0.05% |
Source: OCBC 360 Account page and 360 Account Save Bonus Promotion (August 2026) T&Cs, ocbc.com, checked 15 November 2026. All rates per annum.
Two things are worth noticing. First, Salary, Insure and Invest are the heavy hitters, each worth 1.25% effective. Save and Spend are small top-ups. Second, the effective rates only work out cleanly if your balance is at least S$100,000. With S$50,000 in the account, you never touch the higher “next S$25,000” slice, so the Salary bonus is really 1.00%, not 1.25%.
If you are comparing OCBC 360 against its two big-bank rivals, our DBS Multiplier vs OCBC 360 vs UOB One comparison walks through how each account rewards salary crediting differently.
How to Qualify for Each OCBC 360 Bonus
Each bonus is assessed monthly and paid only for the months you qualify. Missing a category one month does not affect the others, so you can treat the account as a menu rather than an all-or-nothing deal.
| Category | What you need to do each month | Notes |
|---|---|---|
| Salary | Credit a salary of at least S$1,800 via GIRO, FAST or PayNow | The transfer must carry a salary transaction code (OCBC lists examples such as GIRO-SALARY and SAL) |
| Save | Increase your average daily balance by at least S$500 versus the previous month | Withdrawals that pull your monthly average below last month’s level cost you the bonus |
| Spend | Spend at least S$500 on eligible OCBC credit cards | OCBC’s FAQ lists cards including 365, INFINITY, NXT, 90°N and Rewards |
| Insure | Buy an eligible OCBC insurance product | Minimum premium amounts apply by product; the bonus runs for 12 consecutive months |
| Invest | Buy an eligible OCBC investment product | Bonus runs for 12 consecutive months |
| Grow | Keep an average daily balance of at least S$250,000 | No other action needed once you are above the threshold |
Source: OCBC 360 Account page and FAQ, ocbc.com, checked 15 November 2026.
Salary: the bonus most people should chase first
For a typical working adult in Singapore, Salary is the easiest high-value bonus. If your employer pays you through GIRO with the right code, it happens automatically. Self-employed people and freelancers often find their transfers do not count, because the bank looks for a salary-coded transaction rather than any incoming money. If that is you, our guide to the best savings accounts in Singapore without salary credit covers better-suited options.
Save: simple, but it needs discipline
The Save bonus rewards a growing balance. Your average daily balance this month must be at least S$500 higher than last month. A practical way to do this is to set up a standing instruction that moves S$500 or more into the account on payday and to avoid big withdrawals. One large month of spending, such as paying for a holiday, can wipe out the Save bonus for that month.
Spend: only worth it if the card already suits you
The Spend bonus is just 0.25% effective, or S$250 a year on a S$100,000 balance. It makes sense if you already use an OCBC card for daily spending. It does not make sense to switch away from a better cashback or miles card just for this. If you are weighing the OCBC 365 card, see our breakdown of the OCBC 365 cashback revamp.
Insure and Invest: big numbers, bigger commitments
Insure and Invest each add 1.25% effective, but only after you buy an eligible OCBC product, and the bonus lasts 12 consecutive months. That is a product purchase, not a savings habit. Never buy a policy or fund just to earn bonus interest; judge it on its own costs and merits first.
The 0.65% Save Bonus Promotion (to 31 December 2026)
From 1 August to 31 December 2026, OCBC is paying a higher Save bonus. The qualifying rule is unchanged: grow your average daily balance by at least S$500 over the previous calendar month. What changes is the rate.
| Balance slice | Standard Save bonus | Promo Save bonus | Extra interest per year from promo |
|---|---|---|---|
| First S$75,000 | 0.40% | 0.50% | Up to S$75 |
| Next S$25,000 | 0.40% | 1.10% | Up to S$175 |
| Effective on first S$100,000 | 0.40% | 0.65% | Up to S$250 |
Source: OCBC 360 Account Save Bonus Promotion (August 2026) T&Cs, clause 2.1, checked 15 November 2026. Extra interest is a The Kopi Notes calculation on full slices for a full year.
The promo is modest for smaller balances. On S$30,000, it adds 0.10% p.a., about S$2.50 a month. The real uplift sits in the S$75,000 to S$100,000 slice, where the Save bonus jumps from 0.40% to 1.10%.
A few conditions from the promotion T&Cs are worth knowing. Interest is calculated on the month-end average daily balance and credited around the seventh business day of the following month. OCBC can end the promo early or claw back bonus interest at its discretion. Because the promo is due to end on 31 December 2026, do not build a long-term plan around the 0.65% figure.
How Much Interest Will You Actually Earn?
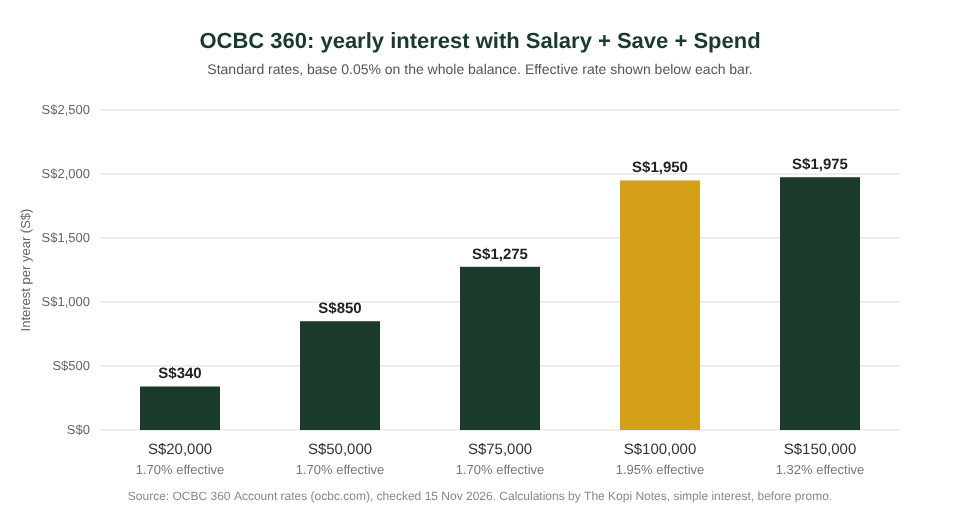
Headline rates hide how the tiers work, so here is what a salaried saver who meets Salary, Save and Spend every month would earn over a year. These are our own calculations from OCBC’s published rates.
| Average balance | Salary + Save + Spend (standard) | Effective rate | With Save promo | Effective rate (promo) |
|---|---|---|---|---|
| S$20,000 | S$340 | 1.70% | S$360 | 1.80% |
| S$50,000 | S$850 | 1.70% | S$900 | 1.80% |
| S$75,000 | S$1,275 | 1.70% | S$1,350 | 1.80% |
| S$100,000 | S$1,950 | 1.95% | S$2,200 | 2.20% |
| S$150,000 | S$1,975 | 1.32% | S$2,225 | 1.48% |
| S$250,000 (adds Grow) | S$3,225 | 1.29% | S$3,475 | 1.39% |
Source: The Kopi Notes calculations using OCBC 360 rates checked 15 November 2026. Simple interest over 12 months, constant balance, base 0.05% on the full balance, bonuses on the first S$100,000 only. Actual interest is calculated monthly and will differ slightly.
Take a Singapore saver with S$50,000 who credits a S$4,500 salary, adds S$500 a month and spends S$600 on an OCBC card. She earns about S$850 a year at standard rates: S$500 from Salary, S$200 from Save, S$125 from Spend and S$25 base. That is 1.70% effective, not the 1.95% headline, because her balance never reaches the higher-paying S$75,000 to S$100,000 slice.
The sweet spot is exactly S$100,000. Above that, every extra dollar earns only the 0.05% base rate, so the effective rate falls quickly. At S$150,000, the extra S$50,000 adds just S$25 a year. Unless you qualify for Grow at S$250,000, money above S$100,000 is usually better placed elsewhere.
Is the 4.70% OCBC 360 Maximum Realistic?
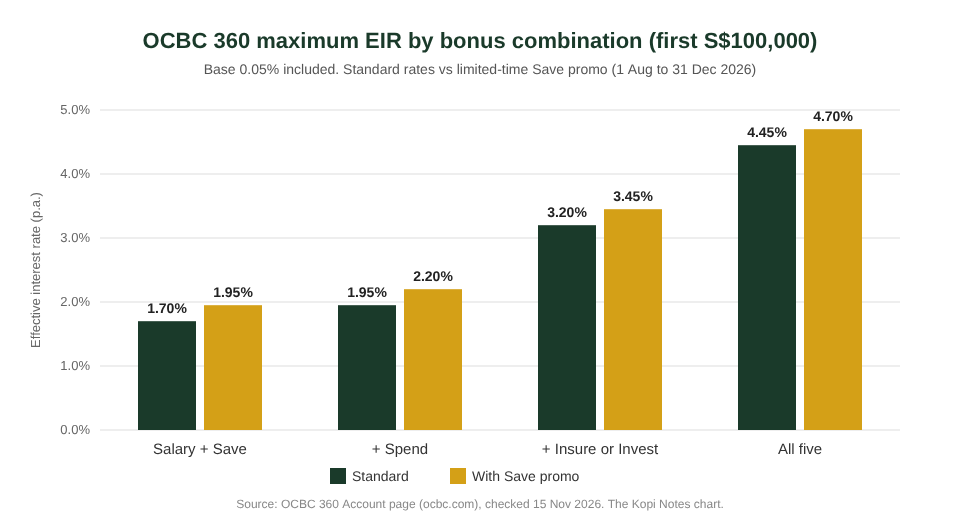
OCBC’s own footnote lists the maximum effective interest rates on the first S$100,000, base included: 1.70% for Salary and Save (1.95% with the promo), 1.95% adding Spend (2.20%), 3.20% adding Insure or Invest (3.45%), and 4.45% with all five (4.70%). OCBC’s FAQ illustrates the full menu as up to S$5,600 a year in bonus interest on S$100,000 when Grow is also counted.
In practice, very few people earn the top figure. To get 4.45% or 4.70%, you need a qualifying salary, a growing balance, S$500 of card spend, and both an insurance and an investment purchase in the past 12 months, all at once. Grow needs a S$250,000 balance, at which point the effective rate on the whole balance is much lower, as our table shows.
A more honest planning number for most salaried savers is 1.70% to 1.95% at standard rates. If you already own an OCBC-sold insurance plan or investment that qualifies, you can add 1.25% for the months it counts. Always weigh any product’s fees against the bonus: an endowment or unit trust with high charges can easily cost more than S$1,250 a year in bonus interest is worth.
Fees, Eligibility and the New-Customer Offer
| Item | OCBC 360 Account |
|---|---|
| Initial deposit | S$1,000 |
| Minimum average daily balance | S$3,000 |
| Fall-below fee | S$2 a month (waived for the first year) |
| Cheque book | S$10 (optional) |
| Statements | E-statements only |
| Eligibility | Age 18 and above; Singaporeans, PRs and foreigners with a valid pass |
| New-to-360 cash reward (1 Nov to 31 Dec 2026) | Up to S$210, subject to salary credit and balance conditions |
Source: OCBC 360 Account page, ocbc.com, checked 15 November 2026.
The fall-below fee matters most for younger savers. If your average balance dips below S$3,000 after the first year, you pay S$2 a month, which at small balances can wipe out a big chunk of your interest.
For customers new to the 360 Account who sign up between 1 November and 31 December 2026, OCBC advertises up to S$210 in cash. According to the account page, that is S$60 for crediting a salary of at least S$1,800 for three consecutive months, plus either S$50 for keeping an average daily balance of at least S$10,000 or S$150 for at least S$25,000, over the qualifying months. Read the campaign T&Cs on OCBC’s site for the exact qualifying months before you rely on it.
OCBC 360 vs Other Places to Park Cash
OCBC 360 suits people who already bank with OCBC, credit their salary there and keep around S$50,000 to S$100,000 in cash. It is less attractive if you cannot credit a salary, if you keep well above S$100,000, or if you dislike managing monthly conditions.
Digital banks are the main no-strings alternative. They usually pay a simpler rate with fewer hoops, and rates change often, so compare them on the same day you decide. Our best digital bank in Singapore guide compares the current options. If you open one, you can use our MariBank referral code 2DCT80WQ, Trust Bank referral code HTWYQP95 or GXS Bank referral code YONG477.
Among the big-bank bonus accounts, the Standard Chartered Bonus$aver interest rate guide covers an account built around card spend, while the CIMB FastSaver interest rate guide covers a tiered account with no salary requirement. For money you will not touch for a while, T-bills and fixed deposits are worth a look too.
A simple structure many Singapore savers use is to keep up to S$100,000 in OCBC 360 to max out the bonus slices, park any excess in a digital bank or short-term fixed deposit, and invest long-term money separately. To see how your cash fits a long-term plan, try our Singapore retirement planning calculator.
Is the OCBC 360 Account Worth It?
For a salaried saver with S$50,000 to S$100,000 who already credits salary to OCBC, yes: 1.70% to 1.95% p.a. with Salary, Save and Spend is a solid return for cash you can withdraw anytime, and the Save promo nudges that to 1.80% to 2.20% until 31 December 2026.
It is weaker in three situations. If you cannot credit a salary, you lose the biggest bonus and are left with at most 0.70% effective at standard rates (0.95% during the Save promo). If you keep far above S$100,000, the extra cash earns only 0.05%. And if the only way to reach the higher tiers is buying insurance or investments you do not need, the “bonus” can cost you money.
The best approach is to decide which categories you will meet naturally, run your own balance through the tables above, and compare that number, not the 4.70% headline, with simpler accounts.
Frequently Asked Questions
What is the OCBC 360 interest rate in November 2026?
The base rate is 0.05% p.a. Bonuses on the first S$100,000 are Salary 1.25% effective, Save 0.40% (0.65% under a promo to 31 December 2026), Spend 0.25%, Insure 1.25%, Invest 1.25% and Grow 1.20%, according to OCBC’s 360 Account page checked on 15 November 2026.
What is the maximum OCBC 360 interest rate?
OCBC quotes a maximum effective rate of 4.45% p.a. on the first S$100,000 with Salary, Save, Spend, Insure and Invest, or 4.70% p.a. during the Save promo from 1 August to 31 December 2026.
How much salary do I need to credit for the OCBC 360 Salary bonus?
At least S$1,800 a month, credited via GIRO, FAST or PayNow with a salary transaction code. Ordinary transfers without a salary code generally do not qualify.
How does the OCBC 360 Save bonus work?
Your average daily balance this month must be at least S$500 higher than last month. If it is, you earn 0.40% p.a. on the first S$100,000, or 0.50% on the first S$75,000 and 1.10% on the next S$25,000 during the promo to 31 December 2026.
How much interest does S$50,000 earn in OCBC 360?
About S$850 a year with Salary, Save and Spend at standard rates, an effective 1.70% p.a., or about S$900 with the Save promo. These are The Kopi Notes calculations assuming a constant balance.
Is there a fall-below fee for OCBC 360?
Yes. The minimum average daily balance is S$3,000. Below that, OCBC charges S$2 a month, waived for the first year. The initial deposit is S$1,000.
Does OCBC 360 pay bonus interest above S$100,000?
Bonus interest applies only to the first S$100,000. Money above that earns the 0.05% base rate, unless your balance is at least S$250,000, which unlocks the Grow bonus of 1.20% on the first S$100,000.
Is OCBC 360 better than a digital bank?
It depends on your situation. OCBC 360 can pay more if you credit a salary and keep close to S$100,000. Digital banks often suit people without salary crediting or who want fewer conditions. Compare current rates on the day you decide.
Disclaimer: This article was researched and drafted with the help of AI tools and checked against OCBC’s official 360 Account page and the 360 Account Save Bonus Promotion (August 2026) terms on 15 November 2026. It is general information, not financial advice. Interest rates, eligibility rules and promotions can change without notice. Always confirm the latest terms on the bank’s website before opening an account or moving money. The Kopi Notes may earn referral rewards from some links.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.