Trust Bank vs moomoo Singapore 2026: Guaranteed Savings Rate or Self-Directed Investing?
Two very different products that both park your spare cash — a digital bank savings account versus a brokerage cash sweep. Here’s which one actually suits you.
Trust Bank is a full digital bank savings account (SDIC-insured to S$100,000) offering a Flex plan up to 2.40% p.a. with effort, or a realistic no-fuss rate of around 0.85% p.a. moomoo’s Cash Plus is a brokerage cash-sweep into the Fullerton SGD Cash Fund yielding roughly 1.32% p.a., with no SDIC insurance but direct CPFIA and SRS investing access. Pick Trust Bank for guaranteed, insured capital; pick moomoo if your cash is already sitting in a brokerage account waiting to be invested.
Not financial advice. All figures are for educational reference only. Data as at November 2026 unless noted.
Table of Contents
Quick Answer: Trust Bank vs moomoo
These two aren’t really competing for the same job. Trust Bank is a standalone digital bank — a partnership between Standard Chartered and FairPrice Group — built around a savings account that pays bonus interest for things like salary credit, card spend and referrals, with your principal protected by the Singapore Deposit Insurance Corporation (SDIC) up to S$100,000. moomoo’s Cash Plus, on the other hand, is a sweep feature inside a brokerage account: idle cash you haven’t invested yet automatically earns a money market fund yield instead of sitting at 0%, with no SDIC coverage because it isn’t a bank deposit at all.
For a Singapore saver with no brokerage account and no intention of opening one, Trust Bank is the more natural home for an emergency fund — it’s a bank, it’s insured, and the Flex plan’s achievable rate of 0.85% p.a. (Union members) or 0.75% p.a. (non-Union, no referral) beats most savings accounts without a salary-crediting requirement. For an investor who already parks cash at moomoo between trades or while funding a CPFIA or SRS position, Cash Plus is simply the better home for that specific pool — the yield is close to Trust’s achievable rate, with zero scoops to chase, though you give up deposit insurance.
Key Differences at a Glance
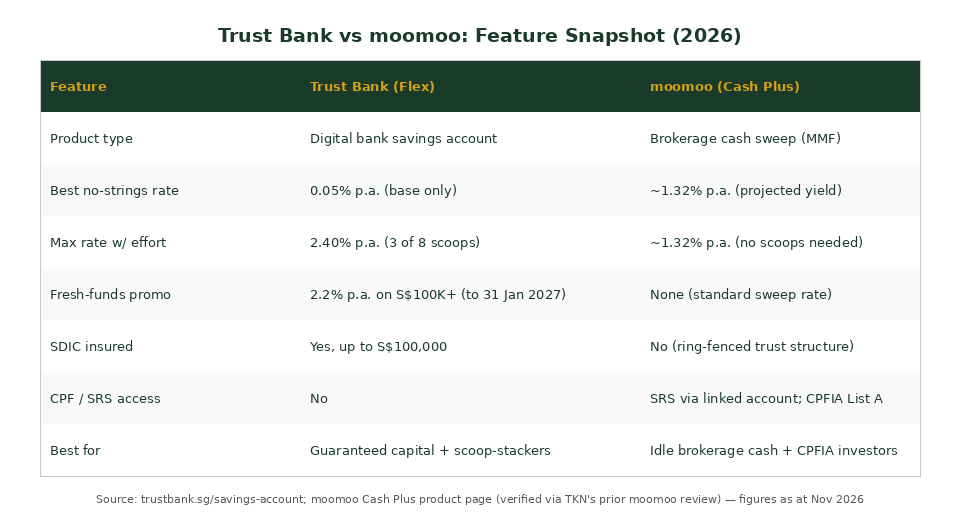
| Feature | Trust Bank | moomoo (Cash Plus) |
|---|---|---|
| Product type | Full digital bank savings account | Brokerage cash-sweep into a money market fund |
| Regulator / backer | MAS full bank licence (Standard Chartered + FairPrice Group) | MAS Capital Markets Services licence (moomoo SG) |
| Base rate (no effort) | 0.05% p.a. (Flex/Signature) or 0.40% p.a. flat (Zen) | ~1.32% p.a. (Fullerton SGD Cash Fund, floats daily) |
| Max achievable rate | Up to 2.40% p.a. (3 of 8 monthly “scoops”) | ~1.32% p.a. (no scoops, no action required) |
| Current promo | 2.2% p.a. guaranteed on S$100K+ fresh funds (to 31 Jan 2027) | None — standard sweep rate |
| Deposit insurance | SDIC-insured up to S$100,000 | Not SDIC-insured; ring-fenced in a custodian trust structure |
| CPF / SRS access | None — savings account only | SRS via a linked account; CPFIA List A ETFs/shares |
| Deposit cap for best rate | First S$1.2M of balance earns the Flex plan rate | No stated cap; yield floats with fund performance |
| Debit/payment features | Debit card, PayNow, FAST, FairPrice Group spend rewards | None — cash must be withdrawn to a linked bank account to spend |
| Best for | An insured emergency fund or primary savings account | Idle brokerage cash already waiting to be invested |
Source: trustbank.sg/savings-account, November 2026; moomoo Cash Plus Fullerton SGD Cash Fund yield reused from TKN’s moomoo Cash Plus review, cross-checked November 2026.
Insurance, Tax & CPF/SRS Access
The single biggest structural difference is what happens to your money if the institution itself runs into trouble. Trust Bank holds a full MAS banking licence, which means Singapore-dollar deposits are automatically covered by the SDIC Deposit Insurance Scheme up to S$100,000 in aggregate per depositor per Scheme member — no opt-in required, no fee. moomoo’s Cash Plus money market fund is not a bank deposit, so it carries no SDIC protection; instead, the cash sits in a custodian trust structure that is legally ring-fenced from moomoo’s own balance sheet, meaning it shouldn’t be clawed back by moomoo’s creditors if the brokerage itself fails, but it is not government-guaranteed the way a Trust Bank deposit is.
Neither product changes your Singapore tax position — interest earned on both is not taxable for individuals in Singapore, since Singapore does not tax personal interest or dividend income by default. Where they diverge sharply is CPF and SRS access. Trust Bank’s savings account cannot hold CPF Ordinary Account, Special Account or SRS funds at all; it is strictly a cash account funded from your take-home pay. moomoo, by contrast, lets you invest SRS funds via a linked account and trade CPF Investment Scheme (CPFIS) List A unit trusts or, through its CPFIA offering, a curated list of ETFs and shares — a meaningful advantage if you’re trying to put idle CPF-OA or SRS money to work rather than leaving it as cash.
Rates Compared: Headline vs Achievable
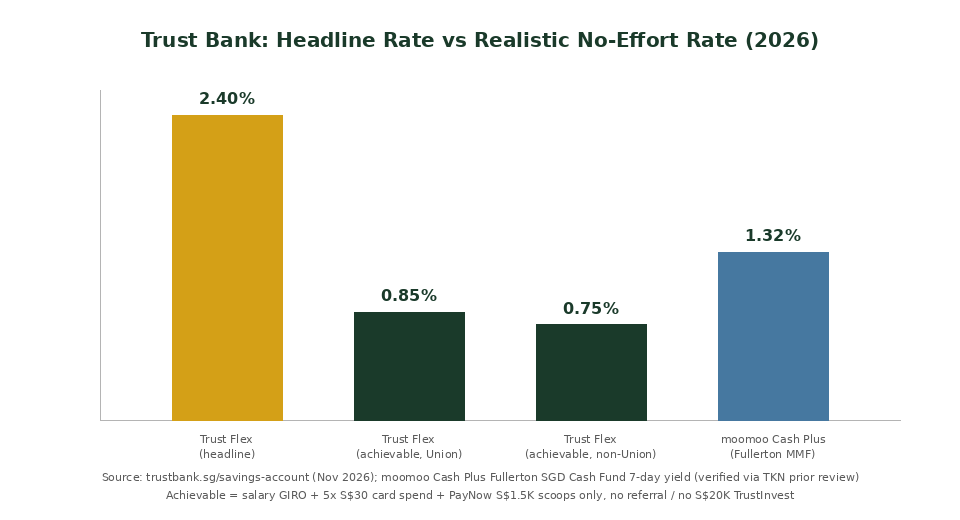
Trust Bank’s marketing leads with “up to 2.40% p.a.” on the Flex plan, but that figure assumes you unlock any 3 of 8 monthly “scoops” — and the two biggest scoops are the hardest to repeat every month: referring a new Trust credit card customer (+1.20% p.a.) and investing a fresh S$20,000 into TrustInvest funds every single month (+0.70% p.a., and note the invested capital itself isn’t SDIC-insured and earns no interest while invested). Strip those two out and an ordinary saver doing only the “free” scoops — salary credit via GIRO (+0.45%), 5 card spends of S$30 (+0.20% for NTUC Union members, +0.10% otherwise) and S$1,500 incoming PayNow (+0.15%) — lands on roughly 0.85% p.a. (Union) or 0.75% p.a. (non-Union) once you add the 0.05% base rate.
moomoo’s Cash Plus has no scoops to chase at all. The Fullerton SGD Cash Fund it sweeps into has been yielding around 1.32% p.a. (7-day annualised, floating with the fund’s underlying short-term instruments), which sits comfortably above Trust Bank’s realistic achievable rate and requires zero behavioural conditions — you don’t need a salary credit, a referral, or a minimum card spend. The trade-off is that this yield is not guaranteed and will drift with short-term interest rates, whereas Trust Bank’s scoops, once unlocked, are contractually fixed for that month.
There is one genuine headline-beats-moomoo scenario right now: Trust Bank’s time-limited promotion pays a guaranteed 2.2% p.a. on S$100,000 or more in fresh funds (2.0% p.a. on S$25,000+) until 31 January 2027, stacked on top of the usual plan. For a saver who can genuinely move S$100K of new money into Trust Bank before the promo ends, this briefly makes Trust Bank the clear winner on rate — but it’s a limited-time offer, not the account’s steady state.
Total Cost and Effort Comparison
Both products are free to open and carry no monthly account fee. The real “cost” is effort and flexibility. Trust Bank’s Flex plan requires you to actively choose and re-choose 3 scoops every month via the Trust App — miss a month’s salary credit or card spend and that month’s bonus interest simply doesn’t apply (though it isn’t retroactively clawed back once unlocked). moomoo’s Cash Plus requires no monthly action: cash sweeps in and out automatically as you buy and sell securities, and the yield applies continuously with no behavioural gate.
On a S$50,000 balance, the difference between Trust Bank’s realistic 0.85% p.a. and moomoo’s ~1.32% p.a. works out to roughly S$235 a year in moomoo’s favour — not a large sum, but it adds up for cash that would otherwise sit at 0% between trades. On the same S$50,000, Trust Bank’s maximum 2.40% p.a. (if all three higher-effort scoops are hit every month, including the S$20,000 TrustInvest scoop) would pay S$1,200 a year, but that requires locking S$20,000 into market-risk investments monthly just to keep the scoop alive — a very different risk profile from simply holding the cash.
Who Should Pick Which?
Trust Bank is the better fit if: you want a single, insured account to receive your salary, pay bills by debit card or PayNow, and earn bonus interest along the way — essentially a primary bank account that happens to pay more than a typical savings account. It also wins outright for anyone able to park S$100,000+ in fresh funds before the 31 January 2027 promo deadline, or anyone who values SDIC protection above a slightly higher floating yield.
moomoo’s Cash Plus is the better fit if: you already have (or plan to open) a moomoo brokerage account for CPFIA, SRS or general stock investing, and you simply want your un-invested cash to earn something close to 1.3% instead of sitting idle at 0% between trades. It’s not designed to be a standalone savings account — there’s no debit card, no bill payments, and withdrawing to spend means transferring back to a linked bank account first.
Many Singapore savers end up using both: Trust Bank (or another SDIC-insured account) as the core emergency fund, and moomoo’s Cash Plus purely as the parking spot for cash inside the brokerage while deciding what to invest next. For a broader look at where idle cash can go, see our MariBank vs moomoo Singapore 2026 comparison and our GXS Bank Singapore complete guide, which cover two more pieces of the same cash-parking puzzle. If you’re mapping this against a longer-term retirement timeline, our Singapore retirement calculator and CPF investment strategy guide are good next stops.
Frequently Asked Questions
Is Trust Bank or moomoo's Cash Plus better for an emergency fund?
Trust Bank is the better choice for an emergency fund because it is SDIC-insured up to S$100,000 and functions as a full bank account with a debit card and bill-payment features. moomoo’s Cash Plus is a brokerage sweep with no deposit insurance — fine for cash you’re about to invest, but not ideal as your sole emergency reserve.
Is moomoo's Cash Plus SDIC insured like Trust Bank?
No. moomoo Cash Plus sweeps your cash into the Fullerton SGD Cash Fund, a money market fund, not a bank deposit, so it is not covered by the Singapore Deposit Insurance Corporation. The cash is held in a ring-fenced custodian trust structure instead, which protects it from moomoo’s own creditors but is not a government guarantee the way SDIC coverage is.
What is a realistic Trust Bank interest rate without chasing every scoop?
Using only the easiest free scoops — salary credit via GIRO, five S$30 card spends, and S$1,500 incoming PayNow — a Trust Bank Flex plan saver can realistically earn about 0.85% p.a. as an NTUC Union member or 0.75% p.a. otherwise, well below the advertised “up to 2.40% p.a.” headline, which requires a monthly referral and a S$20,000 TrustInvest purchase.
Can I use CPF or SRS funds with Trust Bank or moomoo?
Trust Bank’s savings account does not accept CPF or SRS funds at all — it only holds cash from your take-home pay. moomoo does support SRS investing via a linked SRS account and offers CPF Investment Scheme (CPFIA) access to a curated list of ETFs and shares, making it the more relevant platform if you want to put CPF-OA or SRS money to work rather than Trust Bank.
Should I use both Trust Bank and moomoo at the same time?
Yes, this is common practice. Many Singapore savers keep their core emergency fund and salary account at an SDIC-insured bank like Trust Bank, while letting moomoo’s Cash Plus automatically earn yield on cash that’s simply waiting inside their brokerage account to be invested. The two products serve different jobs and aren’t mutually exclusive.
Is Trust Bank's 2.2% promo rate better than moomoo's Cash Plus yield?
For a limited time (until 31 January 2027), Trust Bank pays a guaranteed 2.2% p.a. on S$100,000 or more in fresh funds, which is meaningfully higher than moomoo Cash Plus’s roughly 1.32% p.a. floating yield. This is a time-limited new-money promotion, however, not Trust Bank’s everyday rate, so it should be evaluated as a temporary opportunity rather than a permanent advantage.
Ready to Park Your Cash Smarter?
Open an account with Trust Bank or moomoo using our referral links below for sign-up perks.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.