CIMB FastSaver Interest Rate (November 2026): Every Tier and How to Earn Up to 2.78% p.a.
The four FastSaver balance tiers, the November 2026 fresh-funds bonus, what S$10,000 to S$100,000 actually earns, and the catches to know before you move your cash.
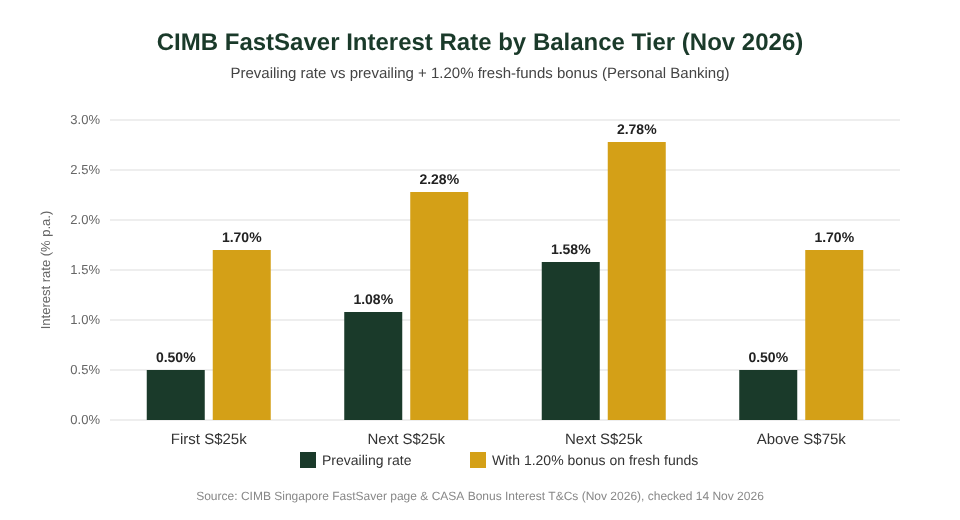
The CIMB FastSaver interest rate in November 2026 is tiered: 0.50% p.a. on the first S$25,000, 1.08% on the next S$25,000, 1.58% on the next S$25,000 and 0.50% above S$75,000. CIMB advertises up to 2.78% p.a. (2.88% for Preferred Banking) by adding a 1.20% bonus on at least S$10,000 of fresh funds deposited from 1 to 30 November 2026. There are no fall-below fees and no salary credit is needed for the base tiers.
Not financial advice. All figures are for educational reference only. Data verified as at 14 November 2026 against CIMB Singapore’s official FastSaver page and the CASA Bonus Interest Promotion (November 2026) terms. Banks can change rates at any time.
Table of Contents
Contents — Click to expand
- CIMB FastSaver Interest Rate Tiers (November 2026)
- The November 2026 Fresh-Funds Bonus Explained
- How Much Interest Will You Actually Earn?
- Salary/GIRO and Credit Card Add-Ons
- Fees, Eligibility and Account Rules
- CIMB FastSaver vs Other Singapore Savings Options
- Is CIMB FastSaver Worth It?
- Frequently Asked Questions
CIMB FastSaver Interest Rate Tiers (November 2026)
CIMB FastSaver is CIMB Singapore’s main no-frills savings account. Unlike the big “do more, earn more” bonus accounts at DBS, OCBC or UOB, it does not require you to credit your salary, buy insurance or invest to earn its base rates. You simply park cash and the balance is split into tiers, with each slice earning its own rate.
According to the CIMB FastSaver product page and clause 7 of the CIMB CASA Bonus Interest Promotion terms (November 2026), both checked on 14 November 2026, the prevailing rates are:
| Balance tier | Prevailing interest (p.a.) | Interest on a full tier per year |
|---|---|---|
| First S$25,000 | 0.50% | S$125 |
| Next S$25,000 (S$25,001 to S$50,000) | 1.08% | S$270 |
| Next S$25,000 (S$50,001 to S$75,000) | 1.58% | S$395 |
| Above S$75,000 | 0.50% | S$5 per S$1,000 |
Source: CIMB Singapore FastSaver page and CASA Bonus Interest Promotion T&Cs, “Information is correct as at 1 November 2026”, checked 14 November 2026. Yearly figures are The Kopi Notes calculations.
Two things stand out. First, the best rate (1.58%) only applies to the slice between S$50,000 and S$75,000. Second, the rate drops back to 0.50% above S$75,000, so FastSaver gets less attractive the more cash you hold beyond that point. Interest is accrued daily on your end-of-day balance and credited monthly, according to CIMB.
This tiered structure means the headline numbers you see in ads are always “up to” figures. Your blended, or effective, rate depends on your total balance, which we work out below.
The November 2026 Fresh-Funds Bonus Explained
The “up to 2.78% p.a.” headline comes from a promotion layered on top of the prevailing tiers. Under the CASA Bonus Interest/Profit Promotion, November 2026, you earn extra interest on incremental fresh funds you add to the account.
| Promotion detail | What CIMB’s terms say |
|---|---|
| Deposit window | 1 November 2026 to 30 November 2026 (both dates inclusive) |
| Minimum fresh funds | S$10,000 incremental balance, maintained through the bonus earning period |
| Bonus rate: Personal Banking | 1.20% p.a. (CIMB advertises up to 2.78% p.a. total) |
| Bonus rate: Preferred Banking | 1.30% p.a. (CIMB advertises up to 2.88% p.a. total) |
| Bonus cap | Incremental balance up to S$1,000,000 per eligible account |
| Comparison balance | Your end-of-day balance on 31 October 2026 (S$0 for new customers) |
| Bonus earning period (per T&Cs) | November 2026, December 2026 and January 2027 |
| Bonus credited | 1 March 2027 (next working day if it falls on a weekend or public holiday) |
| Who is excluded | Customers who already added S$10,000+ incremental fresh funds from 1 to 31 October 2026 |
Source: CIMB CASA Bonus Interest/Profit Promotion, November 2026 T&Cs (clauses 1 to 11) and CIMB FastSaver page, checked 14 November 2026.
The 2.78% figure is simply the top prevailing tier (1.58%) plus the 1.20% bonus. It is a marginal rate on a specific slice of money, not what your whole balance earns.
“Fresh funds” means money that does not come from any existing CIMB current, savings or fixed deposit account. Funds you withdraw and redeposit within the period also don’t count. CIMB checks both a month-end incremental balance and a daily incremental balance against your 31 October 2026 balance, so if you dip below the S$10,000 increase, you can lose the bonus.
One wording note: the FastSaver web page lists the bonus period as 1 to 30 November 2026, while the legal T&Cs describe a bonus earning period covering November 2026 to January 2027 for funds deposited in November. Treat the T&Cs as the governing document and keep your fresh funds in place until the end of January 2027 if you want the full bonus.
How Much Interest Will You Actually Earn?
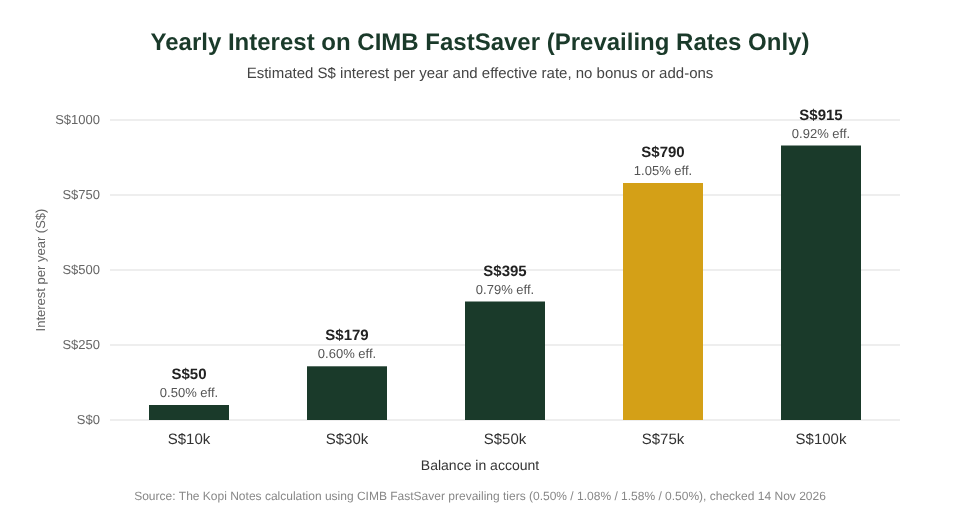
Here is what the CIMB FastSaver interest rate works out to at common balances, using only the prevailing tiers (no bonus, no add-ons). These are The Kopi Notes calculations based on CIMB’s published tiers.
| Balance | Yearly interest (prevailing) | Effective rate (p.a.) |
|---|---|---|
| S$10,000 | S$50 | 0.50% |
| S$30,000 | S$179 | 0.60% |
| S$50,000 | S$395 | 0.79% |
| S$75,000 | S$790 | 1.05% |
| S$100,000 | S$915 | 0.92% |
Source: The Kopi Notes calculations using CIMB FastSaver prevailing tiers (0.50% / 1.08% / 1.58% / 0.50%), checked 14 November 2026. Simple interest, ignores monthly compounding.
The sweet spot is a balance of about S$75,000, where the blended rate peaks at roughly 1.05% p.a. Beyond that, every extra dollar earns only 0.50%, so the effective rate falls.
Worked example: adding S$10,000 of fresh funds in November
Say you had S$40,000 in FastSaver on 31 October 2026 and moved in S$10,000 of fresh funds from another bank in November. Your new S$10,000 slice sits in the S$40,001 to S$50,000 band, earning 1.08% prevailing plus the 1.20% Personal Banking bonus, or 2.28% p.a. on that slice. Over the three bonus months (92 days), the bonus portion alone is about S$10,000 × 1.20% × 92/365 ≈ S$30, paid on 1 March 2027.
Now scale it up. If a new customer opens FastSaver and deposits S$50,000 of fresh funds in November, the bonus on the full S$50,000 over 92 days is about S$50,000 × 1.20% × 92/365 ≈ S$151, on top of roughly S$100 of prevailing interest over the same three months. That’s useful, but it is a short-term boost rather than a permanent rate.
Salary/GIRO and Credit Card Add-Ons
The FastSaver page also lists two extra-interest options, each governed by its own separate terms:
- 0.50% p.a. extra when you credit your salary or set up a recurring GIRO transfer of at least S$1,000, under the CIMB FastSaver/FastSaver-i Salary Crediting and Savings Promotion 2026.
- 1.00% p.a. extra with at least S$800 of monthly eligible spend on the CIMB Visa Signature Credit Card, under the CIMB Bundle Promotion (July to December 2026).
We did not review the separate terms for these two add-ons, so we can’t confirm which balance they apply to, how they stack with the November bonus, or what counts as eligible spend. Read both T&Cs on the FastSaver page before you change your salary crediting or card habits just for these rates. The card promotion is also time-limited to the end of December 2026.
Fees, Eligibility and Account Rules
| Item | CIMB FastSaver (November 2026) |
|---|---|
| Minimum age | 16 |
| Minimum initial deposit | S$1,000 via FAST from a single-name personal account (joint accounts: S$1,000 combined) |
| Fall-below fee | None (“No Fall-Below Fees”) |
| Monthly fee / lock-in | None |
| Internet banking deposits and withdrawals | Free |
| Over-the-counter deposit or withdrawal | S$5 each |
| ATM card | S$10 one-time (new card) and/or S$10 one-time (linking to an existing card) |
| Interest calculation | Accrued daily on end-of-day balance, credited monthly |
Source: CIMB Singapore FastSaver page (product details and FAQ), checked 14 November 2026.
The fee structure is one of FastSaver’s strongest points. There’s no minimum average balance to maintain after opening, so you won’t be charged if your balance drops. The main costs only apply if you bank at a branch counter or want a physical ATM card.
On deposit protection, Singapore dollar deposits at Scheme members are covered by the Singapore Deposit Insurance Corporation up to S$100,000 per depositor per Scheme member. Check the current list of members on the SDIC website.
CIMB FastSaver vs Other Singapore Savings Options
FastSaver sits between two groups of accounts. On one side are the bank bonus accounts, like the Standard Chartered Bonus$aver interest rate breakdown we covered yesterday, which can pay more but need salary credit, card spend or investments. On the other side are the digital banks, which offer simple, condition-light rates.
If you want a no-strings account, compare FastSaver with the MariBank interest rate and the Trust Bank interest rate guides, and our ranking of the best digital bank in Singapore. New users can claim sign-up perks with the MariBank referral code 2DCT80WQ, the Trust Bank referral code HTWYQP95 or the GXS Bank referral code YONG477.
If you can lock money away, CIMB’s own fixed deposits may suit you better for a fixed term. See our CIMB fixed deposit rate guide for the latest board and promo rates. And if your employer can’t credit salary to a new bank, our list of the best savings accounts in Singapore without salary credit is a good next stop.
Rates at all of these banks change often, so compare them on the same day before moving money.
Is CIMB FastSaver Worth It?
FastSaver makes sense if: you want a simple account for S$25,000 to S$75,000 of cash, you don’t want to move your salary or meet spending targets, and you value having no fall-below fee. At S$75,000 the prevailing tiers pay about S$790 a year, and the November fresh-funds bonus can add a little more if you bring in new money this month.
Look elsewhere if: you hold well above S$75,000 in cash (the excess earns just 0.50%), you already meet the salary and spend conditions of a bonus account elsewhere, or you can commit money for a fixed term. For longer-term savings, Singapore T-bills or fixed deposits may offer a better locked-in return.
Your savings account is just the cash layer of your plan. Use our Singapore retirement calculator to work out how much to keep in cash and how much to invest for the long run.
Frequently Asked Questions
What is the CIMB FastSaver interest rate in November 2026?
The prevailing CIMB FastSaver interest rate is 0.50% p.a. on the first S$25,000, 1.08% p.a. on the next S$25,000, 1.58% p.a. on the next S$25,000 and 0.50% p.a. above S$75,000, according to CIMB’s FastSaver page and November 2026 promotion terms.
How do I get the 2.78% p.a. CIMB FastSaver rate?
Deposit at least S$10,000 of incremental fresh funds between 1 and 30 November 2026 and keep it there. Personal Banking customers earn a 1.20% p.a. bonus on the incremental balance; added to the 1.58% top tier, that gives the advertised 2.78% p.a. Preferred Banking customers get 1.30%, or up to 2.88% p.a.
Does CIMB FastSaver have a fall-below fee?
No. CIMB states there are no fall-below fees, no lock-in period and no monthly fees. You need S$1,000 to open the account via FAST.
Do I need to credit my salary to CIMB FastSaver?
No. The tiered prevailing rates apply without salary credit. CIMB offers an extra 0.50% p.a. if you credit salary or set up a recurring GIRO of at least S$1,000, under separate promotion terms.
When is the CIMB FastSaver November bonus interest paid?
According to the November 2026 promotion T&Cs, the bonus is credited on 1 March 2027. You must keep the account open, because closed accounts do not receive the bonus.
What counts as fresh funds for the CIMB bonus?
Fresh funds are money that does not come from any existing CIMB current, savings or fixed deposit account, including funds withdrawn and redeposited during the promotion period. Transfer in from another bank to qualify.
How much interest does S$50,000 earn in CIMB FastSaver?
About S$395 a year at prevailing rates (S$125 on the first S$25,000 plus S$270 on the next S$25,000), an effective rate of about 0.79% p.a. This is a The Kopi Notes calculation and ignores the bonus and add-ons.
Is CIMB FastSaver better than a digital bank account?
It depends on your balance. FastSaver peaks at about 1.05% effective at S$75,000, with no conditions. Compare it with current MariBank, Trust Bank and GXS rates on the same day, since all of them change often.
Disclaimer: This article was researched and drafted with the help of AI tools and checked against CIMB Singapore’s official FastSaver page and CASA Bonus Interest Promotion (November 2026) terms on 14 November 2026. It is general information, not financial advice. Interest rates, eligibility rules and promotions can change without notice. Always confirm the latest terms on the bank’s website before opening an account or moving money. The Kopi Notes may earn referral rewards from some links.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.