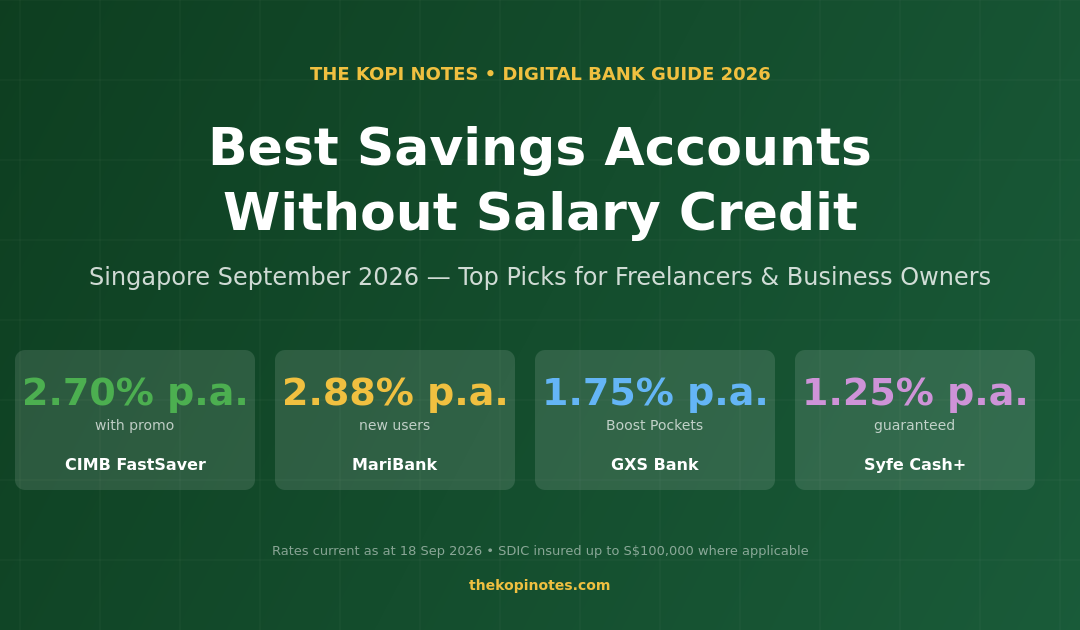
DIGITAL BANK GUIDE · SEPTEMBER 2026
Best Savings Accounts in Singapore
Without Salary Credit
For Freelancers, Self-Employed & Business Owners
MariBank (New Users) · No Salary Required · SDIC Insured
Data verified as at 18 Sep 2026 from official bank websites (maribank.sg, gxs.com.sg, cimb.com.sg, syfe.com). Interest rates are subject to change. This article contains referral links — see disclosure at end.
Quick Summary — Top Picks (September 2026)
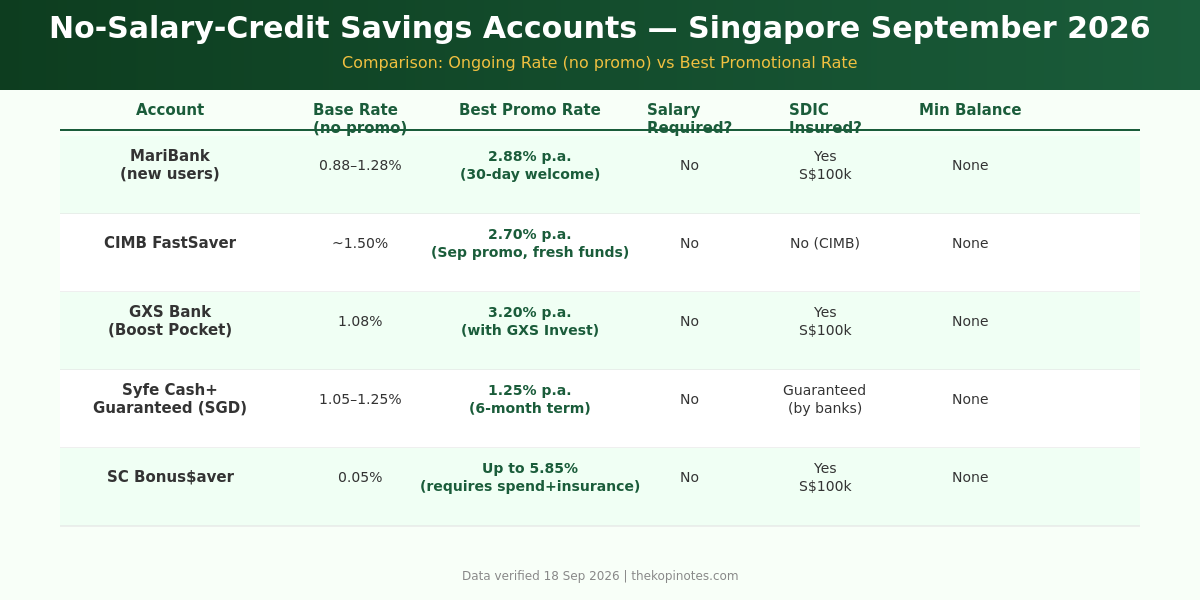
| Account | Best Rate | Ongoing (No Promo) | SDIC? | Min. Balance |
| MariBank | 2.88% p.a. (30-day welcome) | 0.88–1.28% p.a. | ✅ S$100k | None |
| CIMB FastSaver | 2.70% p.a. (Sep promo) | ~1.50% p.a. | ✅ S$100k | None |
| GXS Bank | 1.75% p.a. (Boost Pockets) | 1.08% p.a. | ✅ S$100k | None |
| Syfe Cash+ Guaranteed | 1.25% p.a. (6-month) | 1.05–1.25% p.a. | ⚠️ Guaranteed* | None |
*Syfe Cash+ Guaranteed is not SDIC, but principal + returns are guaranteed by partner banks (SDIC members).
📋 Table of Contents
Why You Need a No-Salary-Credit Savings Account
Most high-interest savings accounts in Singapore — OCBC 360, UOB One, DBS Multiplier — require monthly salary crediting to unlock bonus interest. For salaried employees this is simple, but a growing segment of Singaporeans earns income differently:
- Freelancers and gig workers — income arrives irregularly from multiple clients
- Self-employed and business owners — income may go through a business account first
- Retirees and homemakers — no salary, but want their cash to work harder
- Part-timers and students — working hours don’t meet income thresholds some banks require
- Expats mid-transition — between jobs or recently relocated to Singapore
The good news: Singapore’s digital banking landscape has made no-conditions savings genuinely competitive. You don’t need to credit salary to earn above 1.50% p.a. — and with the right account and timing, you can earn close to 3%.
1. MariBank — Best Rate for New Users (2.88% p.a.)
MariBank is backed by Sea Group (Shopee’s parent), holds a full bank licence from MAS, and is SDIC-insured to S$100,000. It is the only digital bank in Singapore that actively offers a high interest rate with zero hoops — no salary credit, no card spend, no minimum transactions.
Current Rates (September 2026)
| Tier | Rate | Condition |
| Base rate | 0.88% p.a. | All accounts, no conditions |
| ShopeeVIP bonus | +0.40% p.a. | Active Shopee VIP subscription |
| New user welcome | +1.60% p.a. | First 30 days only |
| Max without salary | 2.88% p.a. | New user + ShopeeVIP (first 30 days) |
After the welcome period, your ongoing rate without salary crediting is 0.88% + 0.40% (ShopeeVIP) = 1.28% p.a. — still competitive for a no-conditions account. Interest is calculated daily and credited the following day. No minimum balance, no fall-below fees.
2. CIMB FastSaver — Best Ongoing No-Conditions Rate
The CIMB FastSaver is the go-to account for Singaporeans who want decent interest with minimal complexity. CIMB Bank Berhad Singapore Branch is a licensed bank under MAS and SDIC-insured to S$100,000.
September 2026 Rates
- Base rate (no conditions): ~1.50% p.a. on first S$75,000 — no salary credit, no spend required
- September 2026 promo: Up to 2.70% p.a. with at least S$10,000 fresh funds deposited (1–30 Sep 2026)
The key advantage over MariBank: CIMB FastSaver’s base rate persists indefinitely without any welcome-period expiry. No minimum balance requirement and no monthly fees.
3. GXS Bank — Best Flexible Digital Savings
GXS Bank is backed by Grab and Singtel, holds a full digital bank licence from MAS, and is SDIC-insured to S$100,000. It offers the most flexible savings structure among Singapore’s digital banks.
Rate Structure (September 2026)
| Product | Rate | Notes |
| Main account | 0.88% p.a. | Daily interest, fully liquid |
| Saving Pockets | 1.08% p.a. | Goal-based savings, daily interest |
| Boost Pockets | Up to 1.75% p.a. | Fixed tenures: 1, 3, 4, 8, or 12 months |
| Sep 2026 promo | 3.20% p.a. | 4-month Boost Pocket + qualifying GXS Invest product |
None of GXS Bank’s savings rates require salary crediting. You can open a Boost Pocket directly in the GXS app and earn daily interest immediately.
4. Syfe Cash+ Guaranteed — Safest Guaranteed Option
Syfe Cash+ Guaranteed places your funds with regulated partner banks for a fixed term (1, 3, 6, or 12 months). Both your principal and returns are guaranteed at maturity.
SGD Rates (September 2026)
| Term | Rate p.a. |
| 1 month | 1.05% p.a. |
| 3 months | 1.15% p.a. |
| 6 months | 1.25% p.a. |
| 12 months | ~1.30% p.a. |
While these rates are lower than MariBank or CIMB FastSaver, Syfe Cash+ Guaranteed is the most conservative option: no market risk, guaranteed returns, zero conditions. Good for emergency funds or capital you cannot afford to lose.
Our Verdict: Which Should You Use?
🥇 Best for new users who want the highest rate: MariBank
If you’re opening a new account, MariBank’s 2.88% p.a. welcome rate (first 30 days) with zero conditions is unbeatable. Use referral code 2DCT80WQ. After 30 days, consider moving funds to CIMB FastSaver or a GXS Boost Pocket.
🥈 Best ongoing no-conditions rate: CIMB FastSaver
For a rate that never expires without conditions, CIMB FastSaver (~1.50% base, no salary needed) is the most reliable choice. In September 2026, top up fresh funds to access 2.70% p.a. on up to S$25,000.
🥉 Best flexible digital savings: GXS Bank
GXS Boost Pockets at 1.75% p.a. (up to 3.20% with GXS Invest promo) offer great flexibility with no salary requirement. Boost Pockets have fixed tenures of 1–12 months — ideal if you know when you’ll need the money. Referral code: YONG477.
🛡️ Best for guaranteed safety: Syfe Cash+ Guaranteed
If you want guaranteed principal and returns with no conditions, Syfe Cash+ Guaranteed (1.05–1.30% p.a.) is the safest choice. Best for emergency funds or capital you cannot risk. Referral code: SRPRFFFCD.
📌 Recommended Strategy for Freelancers (September 2026)
- New users: Open MariBank first — park up to S$100k for 30 days at 2.88% p.a. (code: 2DCT80WQ)
- Ongoing: CIMB FastSaver for first S$25,000 (~1.50% ongoing, no conditions)
- Medium-term: GXS Boost Pockets at 1.75% for 1–12 month tenures (code: YONG477)
- Emergency fund: Syfe Cash+ Guaranteed, 1-month term, fully guaranteed (code: SRPRFFFCD)
Frequently Asked Questions
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.