Standard Chartered Bonus$aver Interest Rate (November 2026): How to Earn Up to 7.35% p.a.
Every Bonus$aver bonus category, the S$100,000 cap, what a normal saver actually earns, and how it compares with Standard Chartered’s own fixed deposits.
The Standard Chartered Bonus$aver interest rate is advertised at up to 7.35% p.a. in November 2026, but most savers will earn 0.95% to 1.85% p.a. You get 0.05% p.a. base interest, plus 0.90% p.a. for S$1,000 monthly card spend and 0.90% p.a. for a S$3,000 salary credit. Bonus interest only applies to the first S$100,000. The bigger insure and invest bonuses are temporary and need S$24,000 or S$30,000 commitments.
Not financial advice. All figures are for educational reference only. Data verified as at 13 November 2026 against Standard Chartered Singapore’s official Bonus$aver and time deposit pages. Banks can change rates at any time.
Table of Contents
Contents — Click to expand
- Bonus$aver Interest Rate Breakdown (November 2026)
- How Each Bonus Category Works
- What Rate Will You Actually Earn?
- Bonus$aver vs Standard Chartered Fixed Deposit
- Bonus$aver vs Digital Banks and Other Bonus Accounts
- Eligibility, Exclusions and Catches
- Is Bonus$aver Worth It?
- Frequently Asked Questions
Bonus$aver Interest Rate Breakdown (November 2026)
Bonus$aver is Standard Chartered Singapore’s main bonus-interest savings account. It works like the other big “do more, earn more” accounts in Singapore: you start with a very low base rate, then unlock extra interest each month by doing things with the bank, such as spending on its card or crediting your salary.
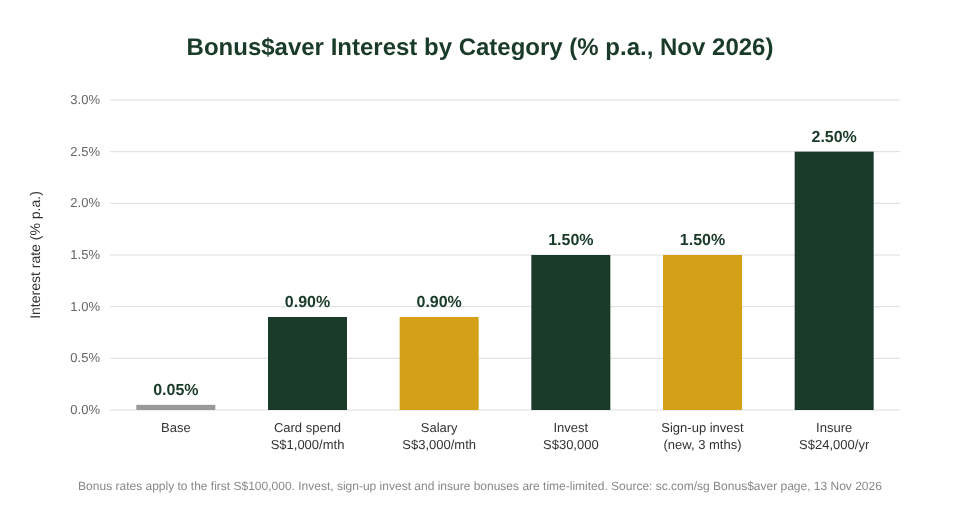
According to the Standard Chartered Bonus$aver page, checked on 13 November 2026, the headline offer is “up to 7.35% p.a.”, valid from 16 October 2026 to 1 February 2027. Here is how each piece is priced.
| Category | What you need to do | Interest (p.a.) | Applies to |
|---|---|---|---|
| Base (prevailing) interest | Nothing | 0.05% | Entire balance |
| Card spend | S$1,000+ eligible spend per calendar month on a Bonus$aver card | 0.90% | First S$100,000 |
| Salary credit | S$3,000+ nett monthly salary via GIRO, PayNow or FAST (purpose code SALA) | 0.90% | First S$100,000 |
| Invest | S$30,000 single eligible unit trust subscription, or S$30,000 cumulative Online Equities buy trades in a month | 1.50%, for 6 consecutive months | First S$100,000 |
| Sign-up invest (new-to-Bonus$aver customers) | Invest in an eligible unit trust or Online Equities | Extra 1.50%, for 3 months | First S$100,000 |
| Insure | Regular-premium life policy (Prudential) with S$24,000 annual premium | 2.50%, for 6 consecutive months | First S$100,000 |
Source: Standard Chartered Singapore Bonus$aver product page and product terms (section A1), accessed 13 November 2026
The 7.35% headline is the sum of every row in that table: 0.05% + 0.90% + 0.90% + 1.50% + 1.50% + 2.50%. Standard Chartered does not spell out that arithmetic on the page, so treat this as our reading of how the headline is built. In practice, very few people will hit every row at once, and three of the rows (invest, sign-up invest and insure) only last for a few months.
How Each Bonus Category Works
1. Card spend: 0.90% p.a. for S$1,000 a month
Spend at least S$1,000 per calendar month on a Bonus$aver card, counted by transaction posting date, and you earn a 0.90% p.a. bonus on the first S$100,000. Standard Chartered’s table puts the total at 0.95% p.a. including the 0.05% base. The bonus is credited one month after the spend month. Watch the posting date: a purchase made on the 30th may post in the next month and miss the cut-off.
The bank’s terms exclude a long list of transactions from the S$1,000 count, including balance transfers, ATM and NETS use, EasyPay instalments, online bill payments, income tax payments, loan and credit card repayments, EZ-Link and transit top-ups, stored-value and digital wallet top-ups, AXS payments, bank fees, reversed transactions and 0% instalment plan payments. If most of your monthly spending is bills and e-wallet top-ups, you may struggle to reach S$1,000 of qualifying spend.
2. Salary credit: 0.90% p.a. for S$3,000 a month
Credit a nett salary of at least S$3,000 a month by GIRO, PayNow or FAST with the purpose code “SALA” and you get another 0.90% p.a. on the first S$100,000. Self-employed people and freelancers who pay themselves by ordinary transfer usually won’t have the SALA code, so they may not qualify for this tier. If that is you, our guide to the best savings accounts in Singapore without salary credit is a better starting point.
3. Invest: 1.50% p.a. for 6 months
Put S$30,000 into a single eligible unit trust subscription, or make S$30,000 of buy trades through Standard Chartered Online Equities within a calendar month, and you earn 1.50% p.a. on the first S$100,000 for six consecutive months. You must hold the investment for the full six months. ETFs, regular savings plans and fund switches don’t count as eligible unit trust purchases.
New-to-Bonus$aver customers get an extra 1.50% p.a. “Sign-Up Invest” bonus for 3 months when they invest in an eligible unit trust or Online Equities.
4. Insure: 2.50% p.a. for 6 months
The biggest single bonus, 2.50% p.a. on the first S$100,000 for six consecutive months, needs a regular-premium life policy underwritten by Prudential with an annual premium of S$24,000. Note that the product terms say the policy must be maintained for at least 12 months. A S$24,000 yearly premium is a large, long-term commitment. Six months of 2.50% on S$100,000 works out to about S$1,250 of bonus interest, so only take the policy if you would have bought it anyway.
What Rate Will You Actually Earn?
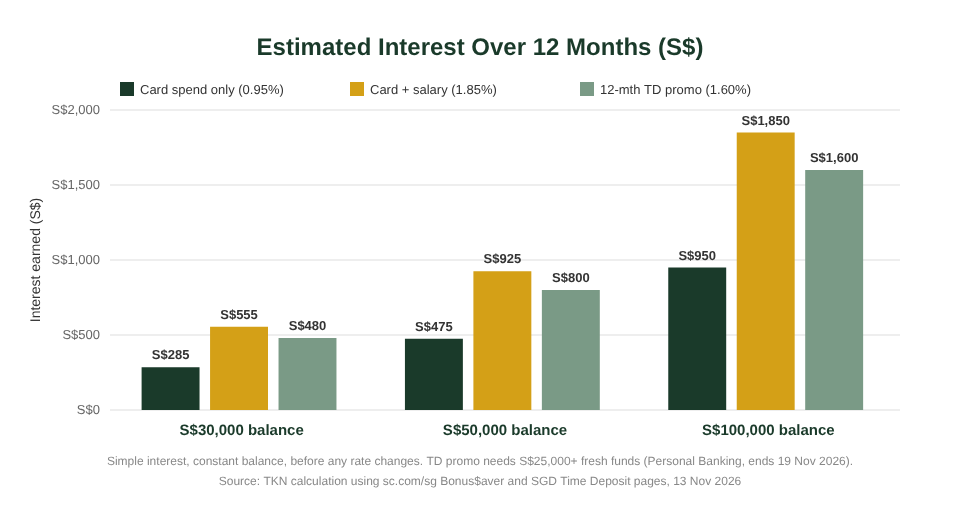
For a typical salaried Singaporean who is not buying a S$24,000-a-year insurance policy or investing S$30,000 in one go, the realistic Bonus$aver interest rate is either 0.95% p.a. (card spend only) or 1.85% p.a. (card spend plus salary credit) on the first S$100,000.
Here’s what that means in Singapore dollars over a year, assuming the balance stays the same and the rates don’t change.
| Balance | Card spend only (0.95%) | Card + salary (1.85%) | Base only (0.05%) |
|---|---|---|---|
| S$30,000 | S$285 | S$555 | S$15 |
| S$50,000 | S$475 | S$925 | S$25 |
| S$100,000 | S$950 | S$1,850 | S$50 |
| S$150,000 | S$975 | S$1,875 | S$75 |
Source: TKN calculation using Standard Chartered Bonus$aver rates as at 13 November 2026. Simple interest on a constant balance; bonus applies to the first S$100,000, base rate to the whole balance.
Two things stand out. First, the bonus cap matters: someone with S$150,000 meeting card and salary earns 1.85% on the first S$100,000 (S$1,850) and only the 0.05% base on the remaining S$50,000 (S$25), so the blended rate drops to about 1.25%. Second, if you only meet one category, your rate is under 1%. That is the same ballpark as Standard Chartered’s own board-rate fixed deposits.
Bonus$aver vs Standard Chartered Fixed Deposit
If you don’t want to spend S$1,000 a month on a card or move your salary, Standard Chartered’s time deposits are the obvious alternative. From 3 to 19 November 2026, the bank runs a 12-month SGD time deposit promotion for at least S$25,000 in fresh funds. Fresh funds means money from outside Standard Chartered that hasn’t been withdrawn and re-deposited in the last 30 days. Placement is through SC Mobile or Online Banking.
| Product | Tenor | Personal Banking | Priority Banking | Priority Private |
|---|---|---|---|---|
| SGD Time Deposit promo (S$25,000+ fresh funds, 3–19 Nov 2026) | 12 months | 1.60% | 1.70% | 1.80% |
| SGD Time Deposit board rate | 6 months | 0.30% | 0.30% | 0.30% |
| SGD Time Deposit board rate | 12 months | 0.60% | 0.60% | 0.60% |
| SGD Time Deposit board rate | 24 months | 1.00% | 1.00% | 1.00% |
| Bonus$aver (card + salary) | No lock-in | 1.85% on first S$100k | 1.85% on first S$100k | 1.85% on first S$100k |
Source: Standard Chartered Singapore SGD Time Deposit page and SGD Time Deposit Interest Rates FAQ, accessed 13 November 2026
So, for a Personal Banking customer with S$50,000, a 12-month promo time deposit at 1.60% p.a. pays about S$800 a year with no monthly hoops. Bonus$aver with card spend and salary credit pays about S$925. The catch is liquidity. Withdrawing a time deposit early means interest is “calculated at our sole discretion”, and the bank says you may get none at all. Bonus$aver money stays accessible, though the rates can change at any time. For more on time deposits, see our Standard Chartered fixed deposit rate guide.
Bonus$aver vs Digital Banks and Other Bonus Accounts
Bonus$aver competes with two groups of accounts.
Other bank bonus accounts. DBS Multiplier, OCBC 360 and UOB One all use the same idea of salary, card spend and other activity unlocking bonus tiers. We compare them in our DBS Multiplier vs OCBC 360 vs UOB One comparison. If you already credit your salary to one of those banks, switching it to Standard Chartered just to unlock 0.90% p.a. is rarely worth losing the bonus you have elsewhere.
Digital banks. MariBank, Trust Bank and GXS Bank pay interest with no spend or salary conditions. Their rates are lower than the best bonus-account tiers, but you don’t have to change how you spend or get paid. Our best digital bank in Singapore guide tracks the current rates. If you open one, you can use our MariBank referral code 2DCT80WQ, Trust Bank referral code HTWYQP95 or GXS Bank referral code YONG477 for a sign-up reward. TKN may earn a referral fee.
A common setup is to keep up to S$100,000 in Bonus$aver if you already spend S$1,000 a month on a Standard Chartered card, and put the rest in a digital bank, T-bills or a time deposit. The bonus stops at S$100,000, and money above that earns only 0.05%.
Eligibility, Exclusions and Catches
- Age. You must be at least 18 to open the account with a debit card, and 21 to 65 with a Bonus$aver credit card.
- Bonus cap. All bonus tiers apply only to the first S$100,000 of your average daily balance (ADB). The bonus is calculated monthly on ADB.
- Timing. Card-spend and salary bonuses are credited one month in arrears. Card spend counts by posting date, not transaction date.
- Time-limited tiers. Invest (6 months), sign-up invest (3 months) and insure (6 months) bonuses end. Don’t plan around 7.35% for the whole year.
- Minimum balance and fees. Standard Chartered’s terms mention a fall-below fee if your ADB drops below the required amount. Check the current figure on the Bonus$aver “Key Account Charges” section before opening.
- Insure and invest go to the primary holder. On joint accounts, only the primary account holder gets these bonuses.
- Deposit insurance. Singapore dollar deposits of non-bank depositors are insured by the Singapore Deposit Insurance Corporation up to S$100,000 in aggregate per depositor per Scheme member, according to Standard Chartered. See the SDIC website for details.
- Scam warning. Standard Chartered warns about fake SMS messages offering promotional deposit rates from +65 numbers, and says it never contacts customers from a +65 number.
There is also a sign-up promotion: S$100 cashback if you deposit and maintain S$50,000 in fresh funds when opening a Bonus$aver account and also sign up for a Bonus$aver World Mastercard Credit Card, during the 16 October 2026 to 1 February 2027 window. Read the full terms on the official Bonus$aver page before relying on it.
Is Bonus$aver Worth It?
Bonus$aver makes sense if: you already spend S$1,000 or more a month on a card you can move to Standard Chartered, you can credit S$3,000+ salary with the SALA code, and you keep around S$50,000 to S$100,000 in cash. At 1.85% p.a. on S$100,000, it pays about S$1,850 a year and you can withdraw at any time.
Look elsewhere if: your salary is already earning a bonus at another bank, you don’t spend S$1,000 a month on cards, or you hold well above S$100,000 in cash. A 12-month time deposit, Singapore T-bills or a no-strings digital bank may give similar returns for less effort.
Whichever you choose, your emergency fund and short-term cash are only one part of the plan. Use our Singapore retirement calculator to see how much of your savings should sit in cash and how much should be invested for the long term.
Frequently Asked Questions
What is the Standard Chartered Bonus$aver interest rate in November 2026?
The base rate is 0.05% p.a. Card spend of S$1,000 a month adds 0.90% p.a. and a S$3,000 salary credit adds another 0.90% p.a., both on the first S$100,000. Standard Chartered advertises up to 7.35% p.a. when temporary invest, sign-up invest and insure bonuses are included, under an offer valid from 16 October 2026 to 1 February 2027.
How is the 7.35% p.a. Bonus$aver rate calculated?
It is the sum of every tier: 0.05% base, 0.90% card spend, 0.90% salary, 1.50% invest, 1.50% sign-up invest for new customers and 2.50% insure. The invest and insure bonuses last only 6 months and the sign-up invest bonus 3 months, so few people earn 7.35% for a full year.
How much card spend do I need for the Bonus$aver bonus?
At least S$1,000 of eligible spend per calendar month on a Bonus$aver card, based on posting date. Bill payments, e-wallet top-ups, tax payments, transit top-ups and several other transaction types do not count.
Is there a cap on Bonus$aver bonus interest?
Yes. Bonus interest only applies to the first S$100,000 of your average daily balance. Money above that earns only the 0.05% p.a. base rate.
Is Bonus$aver better than a Standard Chartered fixed deposit?
For a Personal Banking customer with S$50,000, Bonus$aver with card spend and salary credit (1.85% p.a.) earns about S$925 a year, versus about S$800 on the 12-month promo time deposit at 1.60% p.a. Bonus$aver needs monthly activity but keeps your money accessible. The time deposit needs no activity but locks your money for 12 months.
Can I get the Bonus$aver salary bonus without a salary?
The salary bonus needs a nett monthly salary of at least S$3,000 credited by GIRO, PayNow or FAST with the purpose code SALA. Ordinary transfers without that code will generally not qualify.
Who is eligible to open a Bonus$aver account?
You must be at least 18 to open a Bonus$aver account with a debit card, or 21 to 65 with the Bonus$aver credit card. Insure and invest bonuses go only to the primary account holder.
Is my money in Bonus$aver insured?
Standard Chartered says Singapore dollar deposits of non-bank depositors are insured by the Singapore Deposit Insurance Corporation for up to S$100,000 in aggregate per depositor per Scheme member.
Disclaimer: This article was researched and drafted with the help of AI tools and checked against Standard Chartered Singapore’s official pages on 13 November 2026. It is general information, not financial advice. Interest rates, eligibility rules and promotions can change without notice. Always confirm the latest terms on the bank’s website before opening an account or moving money.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.