Syfe Retirement Decumulation 2026: Turning Your Portfolio Into Income
Decumulation means spending down a portfolio in retirement without running out of money. For Syfe users in Singapore, that means combining Cash+ Guaranteed (short-term spending), Syfe Income+ or Core (growth and monthly payouts), and CPF LIFE (a guaranteed lifetime floor) into one drawdown plan — so market swings don’t force you to sell at the wrong time.
Not financial advice. All figures are for educational reference only. Data as at November 2026 unless otherwise noted.
Table of Contents
Contents — Click to expand
- Why Decumulation Is Different From Accumulation
- The 3-Bucket Framework for Syfe Investors
- Bucket 1: Cash+ Guaranteed for Years 1-3
- Bucket 2: CPF LIFE — Your Guaranteed Floor
- Bucket 3: Income+ and Core as the Growth Engine
- Sequencing Risk: Why Order Matters
- Worked Example: $500,000 Portfolio at 65
- How This Compares to Endowus Decumulation
- Where to Start
- FAQ
Why Decumulation Is Different From Accumulation
Most retirement content focuses on accumulation — saving and investing while you’re working. Decumulation is the opposite problem: once you stop earning a salary, how do you draw down a portfolio for spending money without accidentally selling your growth assets during a downturn, or running out of money at 85?
This matters more for Syfe users than it first appears. Syfe’s Core and Income+ portfolios are unit-trust and ETF-based, so their value moves with markets — there’s no capital guarantee outside Cash+ Guaranteed. A retiree who withdraws a fixed dollar amount every month regardless of market conditions can lock in losses during a downturn, a problem known as sequencing risk (covered in detail below).
The 3-Bucket Framework for Syfe Investors
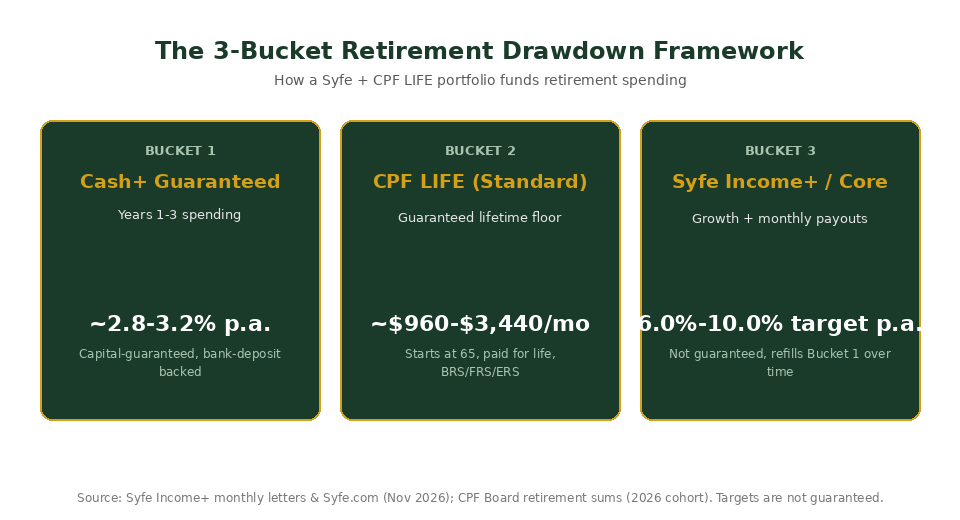
A bucket strategy splits your retirement portfolio by when you’ll need the money, not by asset class alone. For a Singapore investor using Syfe alongside CPF, the three buckets look like this:
| Bucket | Holds | Time Horizon | Target Yield |
|---|---|---|---|
| 1. Spending | Syfe Cash+ Guaranteed | Years 1-3 | ~2.8%-3.2% p.a., capital-guaranteed |
| 2. Floor | CPF LIFE (Standard Plan) | Lifetime, from age 65 | $960-$3,440/month, guaranteed |
| 3. Growth | Syfe Income+ / Core Equity100 | 10+ years | 6.0%-10.0% p.a. target, not guaranteed |
Source: Syfe.com product pages and Income+ monthly letters (Nov 2026); CPF Board retirement sums, 2026 cohort.
Bucket 1: Cash+ Guaranteed for Years 1-3
The first bucket exists to protect you from having to sell growth assets in a downturn. Syfe Cash+ Guaranteed is backed by bank deposits and the quoted rate is net of fees — you don’t pay a separate management fee on top, which makes it directly comparable to a fixed deposit or a high-yield digital bank account.
A retiree spending $3,000 a month would keep roughly $108,000 in this bucket (3 years of spending) and top it up annually from Bucket 3’s payouts, rather than drawing it down to zero and then being forced to sell Income+ or Core units at whatever price the market offers that week. If you’re also holding cash outside Syfe, it’s worth comparing Cash+ Guaranteed’s current rate against MariBank’s savings rate side by side before deciding where the spending bucket sits.
Bucket 2: CPF LIFE — Your Guaranteed Floor
CPF LIFE is the one part of this plan that isn’t invested at all — and that’s exactly the point. It’s a government-administered annuity that pays a fixed monthly amount for life from age 65, funded by the retirement sum you set aside at 55.
| Retirement Sum (2026 cohort) | Amount Set Aside at 55 | Est. CPF LIFE Standard Payout (from 65) |
|---|---|---|
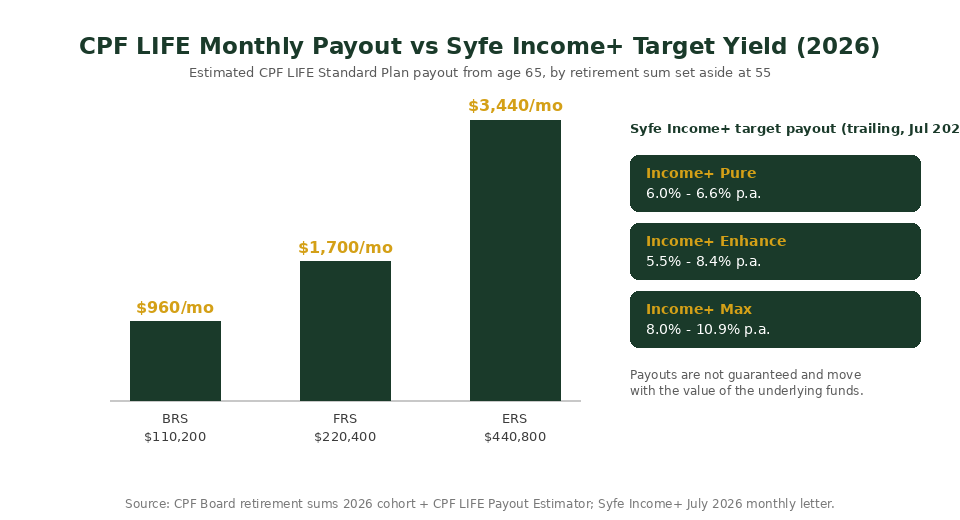
| Basic Retirement Sum (BRS) | $110,200 | ~$900-$960/month |
| Full Retirement Sum (FRS) | $220,400 | ~$1,640-$1,780/month |
| Enhanced Retirement Sum (ERS) | $440,800 | ~$3,150-$3,440/month |
Source: CPF Board 2026 cohort retirement sums; estimated payouts from the CPF LIFE Payout Estimator. Actual payouts depend on your cohort and plan (Standard, Basic or Escalating).
Because the BRS and FRS are fixed for your cohort year while the ERS ceiling is revised annually, topping up to the ERS before 31 December locks in that year’s cap — a detail worth checking against your CPF investment strategy if you’re deciding how much to top up versus leave invested.
Bucket 3: Income+ and Core as the Growth Engine
The third bucket is money you won’t touch for 10+ years, so it can stay invested for growth and refill Bucket 1 as the years pass. Syfe offers two routes here:
Syfe Income+ targets regular monthly distributions from a diversified bond and income-fund portfolio, with three tiers: Pure (6.0%-6.6% p.a. trailing distribution as at July 2026), Enhance (5.5%-8.4% p.a.) and Max (8.0%-10.9% p.a.). These are target payouts, not guarantees — Syfe is explicit that the underlying fund value moves, so your total return can be higher or lower than the distribution rate alone. Our Syfe Income+ review breaks down the fee and risk profile of each tier in more detail.
Syfe Core Equity100, by contrast, has no built-in payout mechanism — it’s a global equity portfolio you’d sell units from manually to generate income, which gives you more control over which units you sell (and the tax/timing implications) but requires more hands-on management in retirement than Income+’s automatic distributions.
Both carry Syfe’s tiered management fee — 0.65% p.a. below $20,000, down to 0.35%-0.50% p.a. above $100,000 — on top of the underlying fund TER. See our full Syfe fees breakdown for the exact tier schedule by portfolio.
Sequencing Risk: Why Order Matters
Sequencing risk is the danger that a market downturn early in retirement does outsized damage, because you’re forced to sell depressed units to fund spending — permanently shrinking the capital left to recover when markets rebound. Two retirees with identical average returns over 20 years can end up with very different outcomes purely because of when the bad years happened.
The 3-bucket structure addresses this directly: Bucket 1 (Cash+ Guaranteed) and Bucket 2 (CPF LIFE) cover 3+ years of spending without touching Bucket 3 at all. If markets fall 20% in year one of retirement, you simply draw from cash and CPF LIFE, leave Income+/Core alone to recover, and refill Bucket 1 from Bucket 3 only in years when markets have actually gone up.
Worked Example: $500,000 Portfolio at 65
Take a Singaporean retiring at 65 with $500,000 outside CPF, having set aside the Full Retirement Sum ($220,400) in CPF at 55. A simple allocation using this framework:
| Bucket | Allocation | Monthly Income Contribution |
|---|---|---|
| Cash+ Guaranteed (3yr spending) | $108,000 | Drawn down, ~2.8%-3.2% p.a. while held |
| CPF LIFE (FRS, Standard Plan) | $220,400 (already in CPF) | ~$1,640-$1,780/month, for life |
| Syfe Income+ Enhance (growth bucket) | $392,000 | ~$1,800-$2,740/month at 5.5%-8.4% target (not guaranteed) |
Illustrative only. Actual Income+ distributions and Cash+ rates vary and are not guaranteed. This is not a personalised recommendation.
On this illustrative split, the guaranteed floor (CPF LIFE) alone covers roughly $1,640-$1,780 a month for life, and the Income+ bucket’s target distributions could add $1,800-$2,740 a month more if targets hold — with Cash+ Guaranteed as the buffer that means a bad year for Income+ doesn’t force a forced sale. Use our retirement planning calculator to run your own numbers against your actual CPF balance and spending target.
How This Compares to Endowus Decumulation
Endowus has its own version of this framework using its Income Portfolio range alongside CPF LIFE — we covered that in detail in our Endowus retirement decumulation guide. The mechanics are similar (cash bucket, guaranteed floor, growth/income bucket), but the key practical difference is CPF eligibility: Endowus is CPFIS-approved and can hold CPF OA funds directly, while Syfe’s SRS support exists but Syfe does not accept CPF OA investments at all. If your retirement drawdown plan depends heavily on investing CPF OA (not just CPF LIFE from your Retirement Account), Endowus is the only one of the two that can hold that money.
Where to Start
If you’re still a decade or more from retirement, the priority is building Bucket 3 first — growth compounds longest when it has the most time. If you’re within 5 years of retiring, start shifting toward Cash+ Guaranteed to build out Bucket 1 before you need the income, so you’re not forced to sell into a downturn on day one of retirement.
Syfe Referral Code — Sign-Up Bonus
Open a Syfe account and fund your Cash+ or Income+ bucket with a referral bonus. Offers change monthly — check the current promotion below.
Also compare with other platforms we cover:
- Endowus Referral Code — for CPF OA & SRS decumulation
- MariBank Referral Code — SDIC-insured savings for your spending bucket
Frequently Asked Questions — Syfe Retirement Decumulation
What is decumulation and why does it need a different plan from saving?
Decumulation is the process of drawing down a retirement portfolio for spending, rather than growing it. It needs a different plan because withdrawing a fixed amount regardless of market conditions can lock in losses during a downturn (sequencing risk), whereas a bucket strategy covers near-term spending with guaranteed or low-volatility assets so growth assets have time to recover.
Can I use Syfe Income+ as my only retirement income source?
You can, but it’s risky on its own because Income+’s target payouts (6.0%-10.0% p.a. depending on tier) are not guaranteed and the underlying fund value moves with markets. Pairing Income+ with a guaranteed floor like CPF LIFE, plus a cash buffer like Cash+ Guaranteed, reduces the chance you’d need to sell Income+ units during a downturn to fund spending.
Does Syfe support CPF OA investing for retirement income?
No. Syfe supports SRS funding but does not accept CPF Ordinary Account (OA) investments. CPF LIFE payouts (from your Retirement Account) work alongside any Syfe portfolio regardless, but if you specifically want to invest CPF OA savings for retirement income, Endowus is the CPFIS-approved option — see our Endowus retirement decumulation guide for that route.
How much should I keep in Cash+ Guaranteed versus invested?
A common rule of thumb is 2-3 years of planned spending in a capital-guaranteed or near-cash bucket (like Cash+ Guaranteed), with the remainder invested for growth. The exact split depends on your other guaranteed income (CPF LIFE, pensions) and risk tolerance — the larger your guaranteed floor, the less cash buffer you may need.
When should I start CPF LIFE payouts?
CPF LIFE payouts can start as early as 65 or be deferred up to age 70, with payouts increasing by roughly 7% for each year of deferral. If your Syfe buckets can cover spending in the interim, deferring can meaningfully raise your lifetime guaranteed income — but it also means less time receiving CPF LIFE payouts if you don’t live to an above-average age.
What's the biggest mistake retirees make with a Syfe portfolio?
Treating Income+ or Core like a bank account — withdrawing a fixed amount every month without a cash buffer. This forces unit sales during downturns and permanently shrinks the portfolio’s ability to recover, which is the core problem a bucket strategy is designed to avoid.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.