Endowment Plan vs Robo Advisor Singapore 2026: Which Grows Your Money Faster?
Updated: October 2026 | 8 min read | Investment Insurance
Table of Contents
- Endowment Plan vs Robo Advisor: Key Differences at a Glance
- What Is an Endowment Plan?
- What Is a Robo Advisor?
- Returns Comparison: How Much Can You Actually Earn?
- Fee Comparison: What Does Each Really Cost?
- Flexibility, Liquidity and Lock-In Periods
- Who Should Choose an Endowment Plan vs Robo Advisor?
- Worked Example: SGD 50,000 Over 10 Years
- Conclusion: Which Wins?
- Frequently Asked Questions
When comparing an endowment plan vs robo advisor in Singapore, the core trade-off is certainty vs potential. Endowment plans offer a guaranteed capital return and a predictable illustrated yield of 3-5% p.a. over 10-25 years, with capital protection built in. Robo advisors like Endowus and Syfe offer no guarantees but can deliver higher long-term returns — typically 4.5-9% p.a. depending on portfolio risk — with full liquidity and no lock-in penalties.
Not financial advice. All figures are for educational reference only. Data verified as at October 2026 unless noted.
Endowment Plan vs Robo Advisor: Key Differences at a Glance
Both products help Singaporeans grow their savings, but they serve very different goals. Here is a side-by-side snapshot:
| Feature | Endowment Plan | Robo Advisor |
|---|---|---|
| Capital Guarantee | Yes (at maturity) | No |
| Guaranteed Return | ~1.5-2.5% p.a. | None |
| Illustrated Total Return | ~3-5% p.a. | 4.5-9% p.a. |
| Lock-In Period | 5-25 years | None |
| Liquidity | Low (early exit penalty) | High (T+3-5 days) |
| Annual Fee | ~1.5-2.5% embedded | 0.35-0.65% p.a. |
| Minimum Investment | From S$5,000/year | From S$1 (Syfe) / S$1,000 (Endowus) |
| CPF / SRS Compatible | SRS only (select plans) | CPF OA, SA and SRS |
| Death/TPD Coverage | Yes | No |
Source: MAS, insurer product illustrations, Endowus.com/pricing, Syfe.com/pricing. October 2026.
What Is an Endowment Plan?
An endowment plan is a life insurance savings product issued by insurers such as AIA, Great Eastern, Manulife, Prudential, and NTUC Income. You pay regular premiums over a set period, and at maturity you receive back your accumulated savings plus a non-guaranteed bonus from the insurer’s participating (par) fund.
Key characteristics of endowment plans:
- Guaranteed component: You are contractually promised a minimum payout at maturity — typically 100-105% of premiums paid. This is the “capital guarantee.”
- Non-guaranteed bonuses: The par fund invests in bonds, equities and properties. Reversionary and terminal bonuses are declared annually by the insurer based on par fund performance. These are non-guaranteed and can vary.
- Death and TPD coverage: Most endowment plans include basic life insurance coverage, making them a hybrid savings-and-protection product.
- Illustrated returns: Insurers present two scenarios per MAS guidelines — 4.75% and 3.25% investment return assumptions. Actual total illustrated yields to policyholders after charges typically range from 3-5% p.a. over a full term.
- Lock-in period: Surrendering early — especially in the first five years — often results in a surrender value below total premiums paid. Many plans require 10-25 years to realise the full illustrated benefit.
Endowment plans are regulated by MAS under the Insurance Act. Policyholders are protected by the Singapore Deposit Insurance Corporation (SDIC) up to S$100,000 per policy owner per insurer for guaranteed benefits.
What Is a Robo Advisor?
A robo advisor is a digital investment platform that uses algorithm-driven portfolio management to invest your money in diversified funds — typically globally diversified ETFs and institutional unit trusts. In Singapore, the two most established robo advisors are Endowus and Syfe, both licensed by MAS as Capital Markets Services (CMS) holders.
Key characteristics of robo advisors:
- Market-linked returns: Your money is invested in real assets — global equities, bonds, REITs — so returns move with markets. No guarantee, but historically superior to savings products over 10+ year horizons.
- Low, transparent fees: Endowus charges 0.30-0.60% p.a. depending on account type and AUM; Syfe charges 0.25-0.65% p.a. depending on tier. Both charge significantly less than endowment plans with embedded costs of 1.5-2.5% p.a.
- No lock-in: You can withdraw at any time (typically T+3 to T+5 business days), making them far more flexible for life emergencies or changing financial goals.
- CPF and SRS compatibility: A major differentiator — Endowus allows you to invest CPF OA, CPF SA and SRS monies in institutional-grade funds. Endowment plans can only accept SRS, and only selected plans do so.
- No sales charges: Unlike traditional insurance products, robo advisors charge zero sales charges. You start earning returns on Day 1 with 100% of your capital invested.
For Singapore investors looking to maximise the potential of their CPF investment strategy, Endowus is particularly strong — it is the only robo advisor in Singapore with direct CPF Board authorisation to invest your OA and SA monies.
Returns Comparison: How Much Can You Actually Earn?
This is the question every Singaporean saver wants answered. The honest answer: it depends on your time horizon, risk tolerance, and whether you need a capital guarantee.
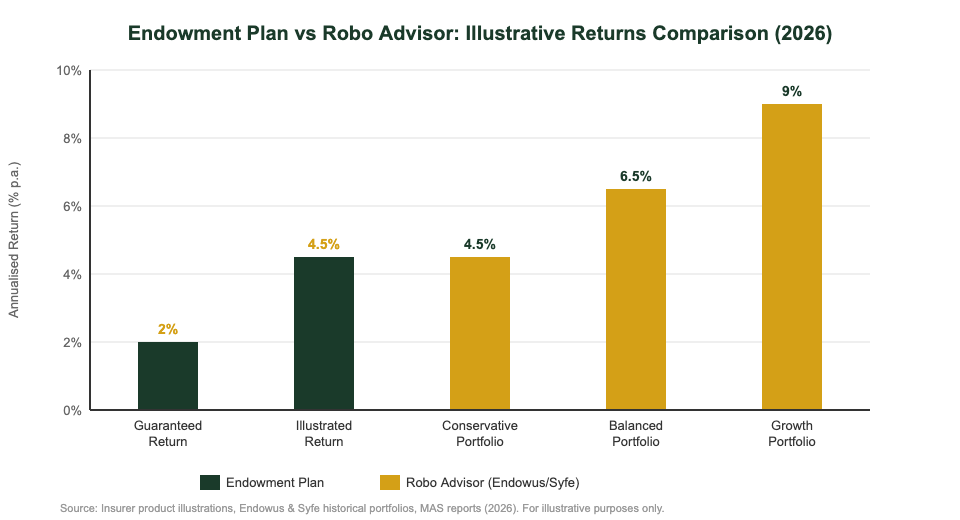
Source: Insurer product illustrations (MAS 4.75%/3.25% scenarios), Endowus and Syfe historical portfolio data, October 2026.
Endowment Plan Returns
Under MAS regulations, insurers must illustrate returns at two investment return scenarios. After deducting insurer expenses, policyholder charges, and distribution costs, the net illustrated yield to the policyholder typically works out to:
- Guaranteed return: ~1.5-2.5% p.a. (the contractually locked-in floor)
- Non-guaranteed bonus (par fund): ~1.5-2.0% p.a. additional (based on recent par fund declarations)
- Total illustrated yield (4.75% scenario): ~4-5% p.a. over a 20-year term
- Total illustrated yield (3.25% scenario): ~3-3.5% p.a. over a 20-year term
Robo Advisor Returns (Endowus and Syfe)
Robo advisor returns are entirely market-linked. Historical (not guaranteed) performance figures for Singapore-based portfolios:
| Portfolio Type | Endowus (Est.) | Syfe (Est.) | Risk Level |
|---|---|---|---|
| Cash / Short-Term | ~3.8% p.a. | ~3.5% p.a. | Very Low |
| Conservative (30/70) | ~4.5% p.a. | ~4.0% p.a. | Low |
| Balanced (60/40) | ~6.5% p.a. | ~6.0% p.a. | Medium |
| Growth / 100% Equity | ~9.0% p.a. | ~8.5% p.a. | High |
Source: Endowus and Syfe platform portfolio return data (annualised, based on historical performance). Past performance does not guarantee future results.
Bottom line on returns: If you can tolerate market volatility and have a time horizon of 10+ years, a balanced-to-growth robo advisor portfolio historically outperforms the illustrated returns of most endowment plans. However, if you need a guaranteed floor for a fixed-date goal, the endowment’s capital guarantee has genuine value.
Fee Comparison: What Does Each Really Cost?
One of the least-understood aspects of endowment plans is that their costs are embedded — you never see a fee deducted from your account. Instead, the insurer earns revenue through the spread between what the par fund generates and what it pays you, plus mortality and expense charges built into the premium structure.
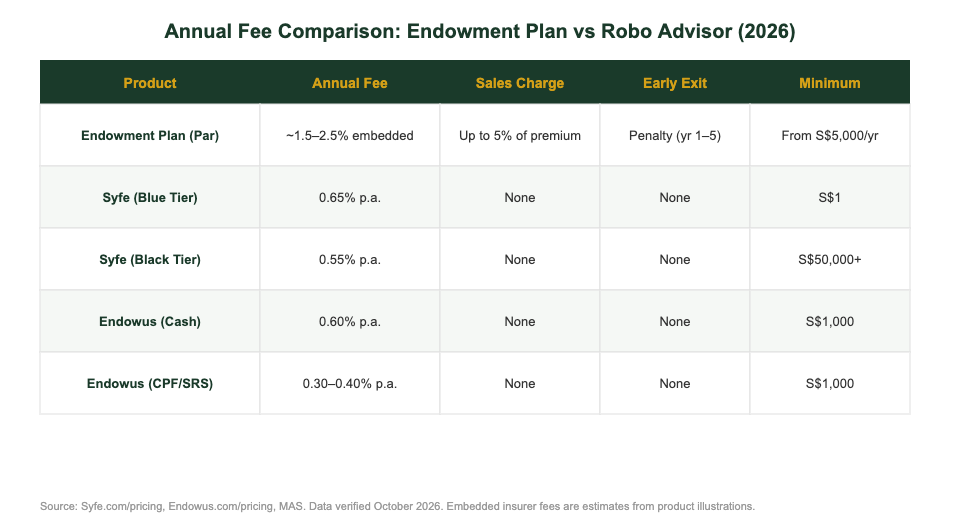
Source: Syfe.com/pricing, Endowus.com/pricing, MAS product disclosure sheets. Data verified October 2026.
Endowment Plan Embedded Costs
- Distribution cost / agent commission: Typically 30-60% of Year 1 premium (paid from your premiums upfront)
- Mortality charge: Deducted annually from your policy value to fund the death benefit
- Par fund management expense: ~1.5-2.5% of fund assets per year (embedded in par fund returns, not disclosed separately)
- Early surrender charge: In the first 2-5 years, surrendering can result in receiving back less than total premiums paid
Robo Advisor Fees (Verified October 2026)
Endowus fees:
- Short-term cash (Cash Smart): 0.15% p.a.
- CPF/SRS multi-fund portfolios: 0.40% p.a.
- CPF/SRS single-fund: 0.30% p.a.
- Cash long-term wealth (less than S$200K): 0.60% p.a.
- 100% trailer fee cashback — reduces effective cost further
Syfe fees:
- Blue tier (no minimum): 0.65% p.a.
- Black tier (S$50,000+): 0.55% p.a.
- Gold tier (S$250,000+): 0.45% p.a.
- No sales charges, no exit fees
Use the Endowus referral code 2V343 when signing up to get S$10,000 managed free for 6 months. For Syfe, use the Syfe referral code SRPRFFFCD to get up to S$60 when you top up your account.
Flexibility, Liquidity and Lock-In Periods
For many Singaporeans, flexibility is the decisive factor. Life changes: retrenchment, medical emergencies, property purchases. The ability to access your savings without penalty has real financial value that is often underweighted when purchasing an endowment plan.
Endowment Plan: Very Low Liquidity
- Partial withdrawals are generally not permitted without surrendering the entire policy
- Policy loans are available in some plans, typically at 5-8% p.a. interest — expensive liquidity
- Surrendering before maturity almost always results in a loss relative to total premiums paid in the first 5 years
- Premium payment holidays may be available after Year 2-3 on some plans but terms vary by insurer
Robo Advisor: High Liquidity
- Full redemption or partial withdrawal available at any time, no fees
- Settlement typically within 3-5 business days (T+3 to T+5)
- No penalties for withdrawing during market downturns (though you bear market risk)
- You can pause contributions at any time without consequence
If you are investing for passive income in Singapore, robo advisor income portfolios (e.g. Endowus Income, Syfe Income+) distribute monthly income while keeping capital invested — giving you both liquidity and cashflow that most endowment plans cannot match.
Use our Singapore retirement calculator to model how different return rates and contribution schedules affect your retirement nest egg under each approach.
Who Should Choose an Endowment Plan vs Robo Advisor?
There is no universal “better” product. The right choice depends entirely on your financial situation, goals, and behavioural traits.
An Endowment Plan May Be Right For You If:
- You have a specific financial goal at a fixed date — e.g. university fees in 18 years or a wedding in 10 years — and need the capital guarantee to ensure the money will be there
- You struggle with staying invested during market volatility and need the forced savings mechanism of a premium commitment
- You want basic life insurance coverage bundled with savings in a single product
- You have low risk tolerance and losing even a small portion of capital would cause significant stress
- You plan to use SRS funds and want a simple, low-maintenance product
A Robo Advisor May Be Right For You If:
- You want higher long-term growth potential and can tolerate year-to-year volatility
- You need flexibility to access funds without penalty during the investment period
- You want to invest CPF OA or SRS savings more aggressively than the default CPF interest rates
- You prefer transparent, low fees and want to understand exactly what you are paying
- You are investing for 15+ years where market-linked compounding will likely outrun guaranteed returns
Many Singapore investors choose to use both — an endowment plan to handle specific, date-certain obligations (e.g. children’s education) and a robo advisor for long-term retirement wealth building. This complementary approach gives you the best of both worlds. You can also explore best S-REITs in Singapore 2026 for another alternative generating dividend income alongside your core portfolio.
Worked Example: SGD 50,000 Over 10 Years
To make the comparison concrete, here is a simplified illustration of what SGD 50,000 invested in each product might look like at the 10-year mark.
| Product | Return Scenario | Year 10 Value | Gain on S$50K |
|---|---|---|---|
| Endowment Plan | Guaranteed only (~2% p.a.) | S$61,000 | +S$11,000 |
| Endowment Plan | Illustrated total (~4.5% p.a.) | S$77,800 | +S$27,800 |
| Syfe / Endowus | Conservative portfolio (~4.5% p.a.) | S$77,800 | +S$27,800 |
| Syfe / Endowus | Balanced portfolio (~6.5% p.a.) | S$93,900 | +S$43,900 |
| Syfe / Endowus | Growth portfolio (~9% p.a.) | S$118,400 | +S$68,400 |
Note: Endowment plan figures based on typical MAS-illustrated scenarios (non-guaranteed). Robo advisor figures based on historical portfolio performance (not guaranteed). All values are approximate and for illustrative purposes only.
At a robo advisor’s balanced return rate, you earn approximately S$16,100 more than the endowment plan’s illustrated scenario — with full liquidity throughout. But unlike the endowment plan, there is no capital guarantee if markets perform poorly.
Conclusion: Endowment Plan vs Robo Advisor — Which Wins?
Neither product is universally better. Here is the verdict by goal:
| Your Primary Goal | Recommended Choice |
|---|---|
| Capital guarantee + specific target date | Endowment Plan |
| Long-term wealth building (15+ years) | Robo Advisor |
| CPF OA / SA investment | Endowus (Robo) |
| Children’s education fund (fixed date) | Endowment Plan |
| Retirement portfolio building | Robo Advisor |
| SRS investment (low risk tolerance) | Both (diversify) |
Sign up for Endowus with referral code 2V343 or Syfe with code SRPRFFFCD to get started with a robo advisor today.
Frequently Asked Questions
Is an endowment plan better than a robo advisor for retirement?
Can I use CPF to buy an endowment plan?
What happens if I surrender my endowment plan early?
Which is safer — endowment plan or Syfe/Endowus?
What is the minimum investment for a robo advisor vs an endowment plan?
Is Endowus or Syfe better for investing CPF?
Get Free Insurance Advice
Speak with a licensed insurance advisor. No obligation, no cost.
By submitting this form, you agree to our Privacy Policy.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.