Endowment Plan Singapore October 2026: New Tranche Yields After the Fed Rate Hike
The Fed raised rates by 25 basis points to 3.75%–4.00% on 17 September 2026 — its first hike since 2023. For Singapore endowment plan buyers, this is a pivotal moment. Existing tranches are closing. New ones will be priced at higher guaranteed yields. If you’ve been considering an endowment plan, October and November 2026 may deliver the best guaranteed rates in years. Here’s exactly what to expect and how to position yourself.
Not financial advice. All figures are for educational reference only. Data verified as at 18 September 2026. Endowment yields and tranche availability change frequently — verify current rates directly with your insurer or a licensed financial adviser before buying.
- The Fed hiked to 3.75–4.00% on Sep 17. New endowment tranches typically reprice upward within 4–10 weeks.
- The current best guaranteed yield sits at approximately 4.25% p.a. for a 3-year plan (latest available tranche as at Sep 2026).
- October–November 2026 is the prime window to compare new tranche launches — existing September rates will close first.
Table of Contents
- What the Fed Rate Hike Means for Singapore Endowment Plans
- Current Endowment Plan Yields in Singapore (Sep 2026)
- How Insurers Reprice: The Tranche Cycle Explained
- What to Watch in October–November 2026
- Should You Buy Now or Wait?
- Endowment vs Alternatives in a Higher-Rate Environment
- Frequently Asked Questions
What the Fed Rate Hike Means for Singapore Endowment Plans
On 17 September 2026, the Federal Reserve raised its benchmark rate by 25 basis points. The new target range is 3.75%–4.00%. This is the first rate hike since 2023 — and it signals a shift in the global rate environment that directly affects Singapore fixed-income products.
Endowment plans in Singapore are participating or non-participating products sold by insurers. Their guaranteed yields are largely driven by the returns insurers can earn on their own bond portfolios. When global rates rise, new money invested by insurers earns more. That higher investment income gets passed on — partially — to new policyholders through higher tranche yields.
The keyword here is “new policyholders.” If you already hold an endowment plan, your guaranteed yield is locked in. You don’t automatically benefit from a rate hike. The upside accrues to buyers of future tranches.
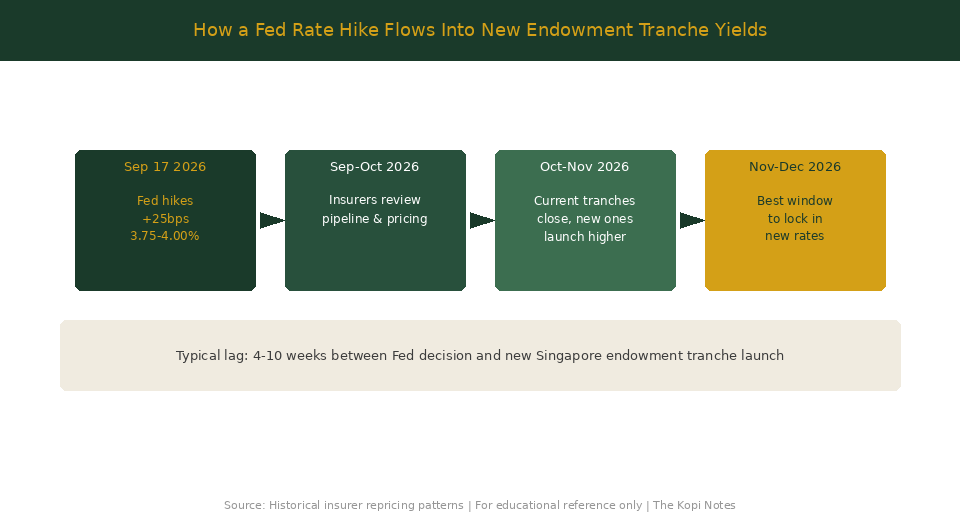
Singapore insurers typically take 4–10 weeks to reflect a rate change in new tranche pricing. That puts the best repricing window in October–November 2026. If you’re planning to buy an endowment plan, this is the period to watch closely.
Current Endowment Plan Yields in Singapore (Sep 2026)
Before the rate hike, here’s where guaranteed yields stood for the major plan types available in Singapore as at September 2026.
| Plan Type | Tenor | Guaranteed Yield (p.a.) | Structure |
|---|---|---|---|
| Short-term endowment (best in class) | 3 years | ~4.25% | Single premium |
| Short-term endowment (typical) | 2–3 years | 2.40%–3.00% | Single premium |
| Short-term endowment (entry-level) | 2 years | 1.44%–1.88% | Single premium |
| Long-term participating endowment | 10–25 years | 2.50%–3.20% (guaranteed) | Regular premiums |
Source: MAS CompareFirst, insurer product pages | Data as at Sep 2026 | Not financial advice
The top of the range — approximately 4.25% p.a. for 3 years — comes from the best available tranche as at September 2026. This is historically high by Singapore standards, but new tranches launching in October could push yields slightly higher if insurers pass on the Fed hike.
How Insurers Reprice: The Tranche Cycle Explained
Singapore endowment plans don’t update their yields daily like a bank savings rate. Instead, insurers sell plans in tranches — a fixed pool of policies at a set guaranteed rate. Once a tranche is fully subscribed or closes, the next one is priced at the current rate environment.
Here’s the typical repricing cycle after a major rate move:
- Week 1–2: Insurers monitor new rate environment and assess their bond investment pipeline.
- Week 3–6: Internal pricing teams set new guaranteed rates for upcoming tranches. Existing open tranches may close early if the insurer expects to sell the next one at a higher price.
- Week 6–10: New tranches launch with updated guaranteed yields. Marketing campaigns begin. Comparison sites (MoneySmart, SingSaver, CompareFirst) update their listings.
For the Sep 17 Fed hike, this puts the prime window in late October to mid-November 2026. Some insurers are faster — you may see new tranches as early as mid-October.
One important nuance: not all insurers pass through the full 25bps. Historically, Singapore insurers have passed through 15–30 basis points of a Fed move to new endowment tranche yields. The pass-through varies by the insurer’s book, their reinsurance arrangements, and competitive dynamics.
What to Watch in October–November 2026
If you’re planning to buy a Singapore endowment plan in the next few months, here’s your watchlist for October–November 2026.
1. HSBC Life Savings Protector II
HSBC Life’s short-term endowment has led the Singapore market on guaranteed yields in 2026. Watch for their October tranche. If the previous tranche offered approximately 4.25% p.a. for 3 years, the next one could push towards 4.40%–4.50% depending on their pass-through.
2. Etiqa Tiq and Singlife Secure Saver
These two plans typically have lower minimum premiums (from S$5,000) and are popular with first-time endowment buyers. Their yields tend to track the market closely, with a slight lag of 2–4 weeks versus HSBC Life.
3. Manulife and AIA Single-Premium Plans
Both insurers have offered competitive 2-year products in 2026. After the rate hike, their new tranches should improve. Manulife’s 2-year plan was at approximately 1.88% p.a. earlier in 2026 — that could rise to 2.00%–2.20% in new tranches.
4. CompareFirst and MoneySmart
The fastest way to track new tranche launches is via CompareFirst (MAS) and the aggregator comparison pages on MoneySmart. These update within days of new tranche launches. Set a reminder to check them in late October.
Should You Buy Now or Wait?
This is the key question for most readers. Here’s the honest framework.
Buy the current tranche if:
- You need the money deployed by a specific date and don’t want to risk the tranche closing before you buy.
- Current yields already meet your target — locking in 4.25% p.a. for 3 years is strong by historical standards.
- You’re uncertain whether future Fed decisions will continue hiking or reverse course. The FOMC projections show 16 of 18 officials see at least one more hike in 2026 — but nothing is guaranteed.
Wait for October–November if:
- You don’t need to deploy capital urgently and can afford a 4–8 week wait.
- You’re optimising for the highest guaranteed yield and want to see whether insurers pass through the Sep 17 hike before you commit.
- You plan to put a significant sum (S$50,000+) into an endowment — even a 20bps improvement saves you S$300/year on a S$150,000 plan.
The pre-FOMC article we published in September covered the endowment plan lock-in decision before the September rate decision — the calculus has now flipped. Back then, readers were considering locking in before a rate cut. Today, with a hike confirmed, the logic reverses: wait and let the new tranches price in the higher rate.
That said, don’t wait indefinitely. If the best October tranche closes quickly (some do, particularly the HSBC Life tranches), you could miss out entirely and face another 4–8 week wait for the next one.
You can estimate how different yields affect your retirement target using the Singapore retirement calculator on TKN — plug in different endowment return assumptions to see the long-run impact.
Endowment vs Alternatives in a Higher-Rate Environment
With rates rising, it’s worth comparing endowment plans against the other fixed-income options available to Singapore investors right now. Each has different lock-up periods, risk profiles, and flexibility.
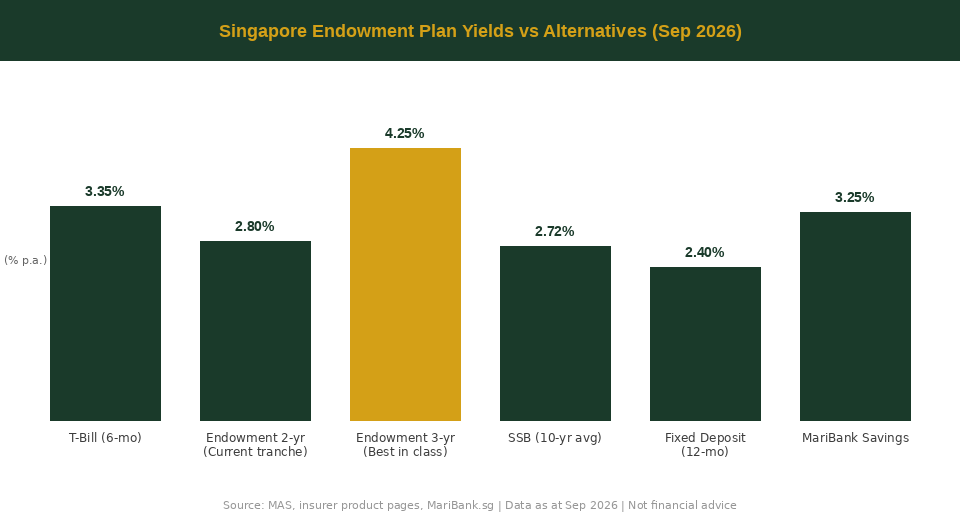
| Product | Yield (Sep 2026) | Lock-up | Capital Guaranteed? | Min Amount |
|---|---|---|---|---|
| Endowment plan (best tranche) | ~4.25% p.a. | 3 years | Yes | S$5,000 |
| 6-month T-bill | ~3.35% p.a. | 6 months | Yes (SGD) | S$1,000 |
| Singapore Savings Bond | ~2.72% p.a. avg | Up to 10 yrs (redeemable) | Yes (SGD) | S$500 |
| Fixed deposit (12 months) | ~2.40% p.a. | 12 months | Yes (bank) | S$1,000 |
| MariBank savings | 3.25% p.a. | None (flexible) | Up to S$75k (SDIC) | S$1 |
Source: MAS, insurer product pages, MariBank.sg | Data as at Sep 2026 | Not financial advice
The endowment plan wins on yield for the 3-year segment — but at the cost of lock-up. If you surrender an endowment plan early, you typically lose some or all of the guaranteed return and may even get back less than you paid in during the early years.
For shorter-horizon needs (under 12 months), T-bills remain the best capital-guaranteed option. The full savings plan comparison after the Fed rate hike covers all these options in more detail.
For a broader breakdown of savings strategies by goal and risk appetite, the 7 types of savings plans ranked guide on TKN is a good starting point. You can also compare the best short-term endowment plans in Singapore for a side-by-side breakdown of open tranches.
If you’re looking for a robo-advisor to handle your broader cash management alongside an endowment, the Endowus referral code (code: 2V343) and the Syfe referral code (code: SRPRFFFCD) both offer sign-up bonuses for new accounts. The MariBank referral code (code: 2DCT80WQ) gives you access to their 3.25% savings account with no lock-in.
Frequently Asked Questions
Will endowment plan yields definitely go up after the Fed rate hike?
What is the best endowment plan in Singapore right now (Sep 2026)?
How long should I wait before buying an endowment plan after a Fed rate hike?
Is an endowment plan better than a T-bill right now?
Can I use CPF funds to buy an endowment plan?
What happens if I surrender my endowment plan early?
Get Free Insurance Advice
Speak with a licensed insurance advisor. No obligation, no cost.
By submitting this form, you agree to our Privacy Policy.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.