Matched MediSave Scheme (MMSS) 2026: How to Get Up to $1,000 Free Government Top-Up
The Matched MediSave Scheme (MMSS) is a five-year government initiative (2026–2030) that matches every dollar you voluntarily top up into your MediSave account — up to $1,000 per year. Eligible Singapore Citizens aged 55 to 70 with an average monthly income of $4,000 or less can receive up to $5,000 in free government contributions over the scheme lifetime, with no application required.
Not financial or tax advice. All figures are for educational reference only. Data verified as at October 2026. Please consult a licensed financial adviser or the CPF Board for personalised guidance.
What Is the Matched MediSave Scheme (MMSS)?
The Matched MediSave Scheme (MMSS) was introduced as part of Singapore’s Budget 2026 and took effect from January 2026. Administered by the CPF Board, it is designed to help lower-income, middle-aged Singaporeans build up their MediSave balances so they can better manage healthcare costs in retirement.
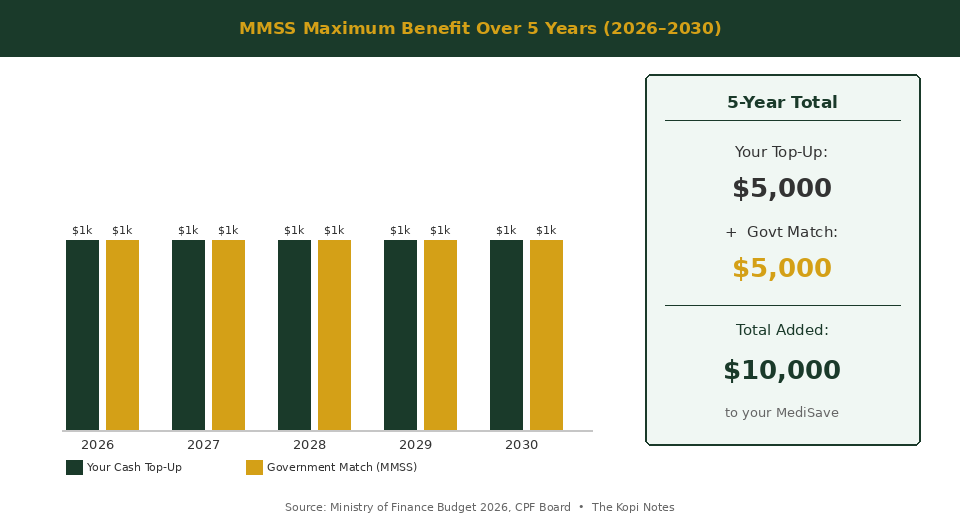
Under the MMSS, the Government provides a dollar-for-dollar match on voluntary cash top-ups to your MediSave Account, capped at $1,000 per year. Because the scheme runs for five years (2026 to 2030), eligible members who maximise their annual top-ups can receive up to $5,000 in total government matching grants over the scheme’s lifetime — on top of their own contributions.
The MMSS is separate from the MediSave Basic Healthcare Sum (BHS) and annual contribution cap — it is a standalone incentive scheme that rewards proactive voluntary top-ups. Approximately 184,000 CPF members are expected to benefit from the scheme annually.
If you have been wondering how to make the most of your Integrated Shield Plan (ISP) coverage heading into retirement, topping up your MediSave under the MMSS is one of the most efficient ways to build a healthcare buffer — especially if you qualify for the government match.
MMSS Eligibility Criteria 2026
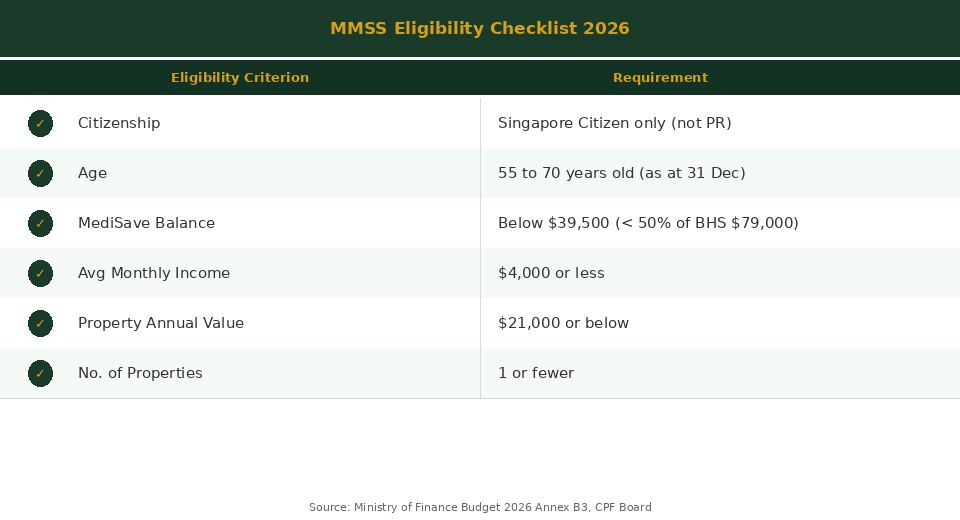
To qualify for the MMSS, you must satisfy all six of the following conditions as at 31 December of the assessment year. Missing even one criterion means you do not qualify for that year’s matching grant.
| Eligibility Criterion | Requirement |
|---|---|
| Citizenship | Singapore Citizen only (PRs not eligible) |
| Age | 55 to 70 years old as at 31 December |
| MediSave Balance | Below $39,500 (less than 50% of the 2026 BHS of $79,000) |
| Average Monthly Income | $4,000 or less in the preceding calendar year |
| Property Annual Value | $21,000 or below |
| Number of Properties Owned | 1 or fewer |
Source: Ministry of Finance Budget 2026 Annex B3, CPF Board
The CPF Board automatically assesses your eligibility every year — you do not need to submit any application. Eligible members receive a notification via email or post in January of each year. You can also check your eligibility status through my.cpf.gov.sg using your Singpass login.
Key note on the MediSave balance threshold: The $39,500 threshold is set at 50% of the 2026 Basic Healthcare Sum (BHS) of $79,000. The BHS typically increases annually, so the qualifying threshold may change in future years. Members with MediSave balances at or above $39,500 do not qualify for the MMSS, regardless of their other circumstances.
How Much Can You Receive?
The MMSS provides a dollar-for-dollar match, capped at $1,000 per year. If you top up less than $1,000, the government match is smaller — it follows your contribution exactly. Topping up more than $1,000 earns you the maximum $1,000 match, but no additional matching beyond that cap applies.
| Your Cash Top-Up | Government Matches | Total Added to MediSave |
|---|---|---|
| $300 | $300 | $600 |
| $500 | $500 | $1,000 |
| $1,000 | $1,000 (maximum) | $2,000 |
| $3,000 | $1,000 (capped) | $4,000 |
Source: CPF Board, Ministry of Finance Budget 2026
Over the five-year scheme (2026–2030), the maximum total government contribution is $5,000 — provided you make at least $1,000 in qualifying cash top-ups every year. The grant is credited to your MediSave Account at the start of the following year. So top-ups made by 31 December 2026 earn a grant credited in January 2027.
There is no minimum top-up amount required to participate. Even a $50 voluntary contribution earns a $50 government match. The key requirement is that the top-up must be credited to your MediSave Account before 31 December of the assessment year.
How to Top Up Your MediSave (Step-by-Step)
To receive the MMSS government match, you need to make a voluntary cash top-up to your MediSave Account. Here is how to do it:
Step 1: Check your eligibility
Log in to my.cpf.gov.sg with Singpass and check your MediSave balance. If your balance is below $39,500 and you meet the other criteria, you are eligible to participate in the MMSS for 2026. The CPF Board also sends eligibility notifications in January each year.
Step 2: Choose your top-up method
You can make a voluntary MediSave top-up using any of these methods:
- PayNow-CPF — Transfer directly from your bank app by entering your NRIC or scanning the CPF QR code
- CPF e-Cashier (my.cpf.gov.sg) — Log in and pay via internet banking, PayNow, or FAST transfer
- GIRO — Set up a recurring monthly deduction from your bank account
- At a CPF Service Centre — Walk in with your NRIC for assisted cash payment
Step 3: Decide the top-up amount
To maximise the MMSS grant, top up at least $1,000 before 31 December. Any amount works — there is no minimum. Importantly, anyone can make the top-up on your behalf: your spouse, children, employer, or any community member. The MMSS match is based on the eligible member’s account, not who made the contribution.
Step 4: Wait for the government grant
After 31 December, the CPF Board automatically assesses your eligibility for that year. If you qualify, the matching grant is credited to your MediSave Account in January of the following year. No paperwork or claim form is needed.
Important: Ensure you select “MediSave Account” as the destination when making the transfer. Top-ups to your Ordinary Account or Special Account do not count towards the MMSS.
MMSS and Income Tax Relief: What You Can Claim
The tax treatment of MMSS top-ups is one of the most commonly misunderstood aspects of the scheme. Here is the clear breakdown:
The MMSS-matched top-up (first $1,000) does NOT qualify for income tax relief. IRAS specifically excludes this portion because you are already receiving a dollar-for-dollar government match as the incentive. Double-dipping — getting both a 100% government match and a tax deduction on the same $1,000 — is not permitted.
However, top-ups above the $1,000 MMSS cap may still qualify for the standard MediSave Top-Up Tax Relief:
- Up to $8,000 per year in tax relief for topping up your own CPF MediSave, Retirement Account, or Special Account
- A separate $8,000 relief for topping up family members’ accounts (combined cap)
- Only the portion of your top-up that exceeds the $1,000 MMSS cap is eligible for this tax relief
Worked example — YA 2027 (for a 2026 top-up of $3,000):
- First $1,000 → earns $1,000 MMSS government match → no tax relief applies
- Remaining $2,000 → eligible for standard MediSave Top-Up Tax Relief
- At a 7% marginal income tax rate: $2,000 × 7% = $140 in tax savings
- Total combined benefit from a $3,000 top-up: $1,000 (MMSS grant) + $140 (tax savings) = $1,140 — effectively a 38% return on the $3,000 outlay
Check the IRAS CPF Cash Top-Up Relief page for the latest annual limits, as they may be revised.
MMSS vs Other CPF Matching Schemes
Singapore has several government matching programmes for CPF savings. Here is how the MMSS compares with the two closest alternatives:
| Scheme | Target Account | Target Group | Annual Match Cap |
|---|---|---|---|
| MMSS (2026–2030) | MediSave Account | Citizens, 55–70, low income, low MA | $1,000 |
| MRSS (ongoing) | Retirement Account | Citizens, 55–70, low income, low RA | $600 |
| Workfare MediSave Bonus | MediSave Account | Lower-wage workers, annual | Varies by age |
Source: Ministry of Finance, CPF Board, as at October 2026
The MMSS has a higher annual match cap than the MRSS ($1,000 vs $600), making it particularly valuable for eligible members who can set aside $1,000 per year for healthcare savings. Crucially, you can participate in both the MMSS and the MRSS simultaneously if you meet the eligibility criteria for each — the two schemes target different CPF accounts and the eligibility criteria are independent.
Planning retirement finances? Our Singapore retirement planning calculator can help you model the long-term impact of MediSave top-ups on your retirement healthcare buffer.
Is the MMSS Worth It?
For eligible Singaporeans, the MMSS offers an immediate 100% return on the first $1,000 of top-ups — fully guaranteed by the government. That alone makes it one of the most compelling savings incentives available in Singapore. Your MediSave also earns a guaranteed 4% per annum interest rate, compounding the benefit further over time.
Reasons to maximise your MMSS top-up (if eligible):
- Zero risk: the government match is guaranteed, not market-dependent
- MediSave earns 4% p.a. — a high, risk-free return in the current environment
- A higher MediSave balance means more ISP premiums can be paid from MediSave rather than cash, preserving your monthly cash flow in retirement
- MediSave funds can also be used for CareShield Life premiums, hospitalisation, day surgery, outpatient care, and approved medical devices
- Over five years, $5,000 in matched grants (plus your own $5,000) compounds at 4% p.a. to grow your healthcare safety net meaningfully
Who should prioritise the MMSS: Singapore Citizens aged 55–70 with MediSave below $39,500 who have discretionary savings to set aside annually, especially those with ISP riders whose premiums draw from MediSave.
If you do not qualify for MMSS — for example, your MediSave is already above $39,500 or your income exceeds $4,000/month — standard voluntary MediSave top-ups still earn 4% p.a. and may qualify for up to $8,000 in MediSave Top-Up Tax Relief annually. Alternatively, consider investing your CPF OA savings via Endowus (referral code 2V343) for globally diversified exposure through the CPF Investment Scheme.
Frequently Asked Questions
Who is eligible for the Matched MediSave Scheme (MMSS) in 2026?
To qualify, you must be a Singapore Citizen (not PR) aged 55 to 70, with a MediSave Account balance below $39,500 (50% of the 2026 BHS of $79,000), an average monthly income of $4,000 or less, a property Annual Value of $21,000 or below, and you must own no more than one property. All six conditions must be met as at 31 December of the assessment year.
Do I need to apply for the MMSS?
No application is needed. The CPF Board automatically assesses your eligibility every year using CPF and IRAS data. If you qualify, you will receive a notification by email or post in January. You simply need to make voluntary cash top-ups to your MediSave Account before 31 December to trigger the matching grant.
Does the MMSS top-up qualify for income tax relief?
No. The first $1,000 of top-ups that receive the MMSS government match does not qualify for MediSave Top-Up Tax Relief. However, any additional top-ups above the $1,000 MMSS annual cap may still qualify for standard MediSave top-up tax relief of up to $8,000 per year. Always check the IRAS website for the latest prevailing limits.
How much can I receive from the MMSS over five years?
Up to $5,000 in total — $1,000 per year from 2026 to 2030. The government matches your cash top-ups dollar-for-dollar, so you need to top up at least $1,000 per year to receive the maximum annual match. Over five years, you and the government together would add up to $10,000 to your MediSave Account.
Can my children or spouse top up my MediSave to trigger the MMSS?
Yes. Anyone — including your spouse, children, siblings, parents, employer, or members of the community — can make voluntary cash top-ups to your MediSave Account. The MMSS matching is based on the eligible member’s account, not the identity of who made the top-up. The funds simply need to be credited to the eligible member’s MediSave before 31 December.
When will the government credit my MMSS matching grant?
The matching grant is credited to your MediSave Account at the start of the following year. For example, if you top up by 31 December 2026, the CPF Board will assess your eligibility and credit the matching grant in January 2027. The grant is a one-time annual lump sum — not credited monthly or pro-rated across individual top-up transactions.
Explore More: MediSave & Healthcare Planning Guides
Understanding your MediSave and ISP options is essential for retirement healthcare planning. More guides from The Kopi Notes:
- MediSave Limit 2026: Basic Healthcare Sum & Annual Cap Guide
- What Is an Integrated Shield Plan? Complete Singapore Guide
- MediSave Annual Withdrawal Limits for ISP Premiums in 2026
- CareShield Life Singapore: How It Works & Premium Guide
Want to put your CPF Ordinary Account savings to work? Sign up for Endowus with referral code 2V343 and get up to $20 in bonus credits. Endowus lets you invest CPF OA, SRS, and cash savings in globally diversified, low-cost portfolios.
Get Free Insurance Advice
Speak with a licensed insurance advisor. No obligation, no cost.
By submitting this form, you agree to our Privacy Policy.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.