Singapore Bank Fixed Deposit Rate 2026: Every Major Bank Compared
October 2026 Update — Rates from DBS, UOB, OCBC, CIMB, HL Bank, Maybank & More
📋 What You’ll Find in This Guide
- All Singapore Bank FD Rates at a Glance
- Local Banks: DBS, UOB, OCBC, CIMB, Maybank, RHB
- Foreign Banks: Bank of China, HL Bank, Citibank, HSBC
- FD Rates by Tenor: 3-Month, 6-Month and 12-Month
- Digital Bank Alternatives (No Lock-In)
- How to Pick the Right Tenor and Bank
- Is Your Money Safe? SDIC Deposit Insurance
- Frequently Asked Questions
Fixed deposit rates at Singapore banks vary widely in October 2026 — from 1.00% p.a. at DBS/POSB for a 12-month placement to 2.10% p.a. at HL Bank for 24 months. Among foreign banks and finance companies, rates have climbed: Singapura Finance offers 2.08% for 12 months, while Maybank and CIMB both top 1.90%. Meanwhile, digital banks like MariBank and Trust Bank offer savings account rates up to 2.70% p.a. without any lock-in period.
Not financial advice. All rates are for educational reference only and subject to change. Data as at October 2026 — verify directly with each bank before placing funds.
Singapore Bank Fixed Deposit Rates at a Glance (October 2026)
The table below covers 12-month Singapore dollar fixed deposit rates across all major banks. Where a bank offers multiple rates by minimum deposit tier, the most broadly accessible rate is shown first.
| Bank | Best 12-Month Rate | Minimum Deposit | Bank Type |
|---|---|---|---|
| Singapura Finance (Vivid FD) | 2.08% p.a. | S$10,000 | Finance Company |
| HL Bank | 2.05% p.a. | S$10,000 | Foreign Bank |
| CIMB (Preferred) | 1.95% p.a. | S$10,000 | Foreign Bank |
| Maybank | 1.91% p.a. | S$20,000 | Foreign Bank |
| RHB | 1.90% p.a. | S$20,000 | Foreign Bank |
| Bank of China (mobile, standard) | 1.70% p.a. | S$500 | Foreign Bank |
| Hong Leong Finance | 1.60%–1.70% p.a. | S$5,000–S$20,000 | Finance Company |
| UOB | 1.45%–1.70% p.a. | S$10,000 | Local Bank |
| OCBC | 1.40%–1.65% p.a. | S$20,000 | Local Bank |
| HSBC Personal | 1.40% p.a. | S$30,000 | Foreign Bank |
| ICBC (e-banking) | 1.30%–1.45% p.a. | S$500–S$20,000 | Foreign Bank |
| DBS / POSB | 1.00% p.a. | S$1,000 | Local Bank |
| Standard Chartered | 0.60% p.a. | No minimum | Foreign Bank |
Source: StashAway FD Rate Comparison, GrowBeanSprout, October 2026. Rates subject to change — verify directly with each institution. Higher tiers available with larger minimum deposits or relationship banking status.
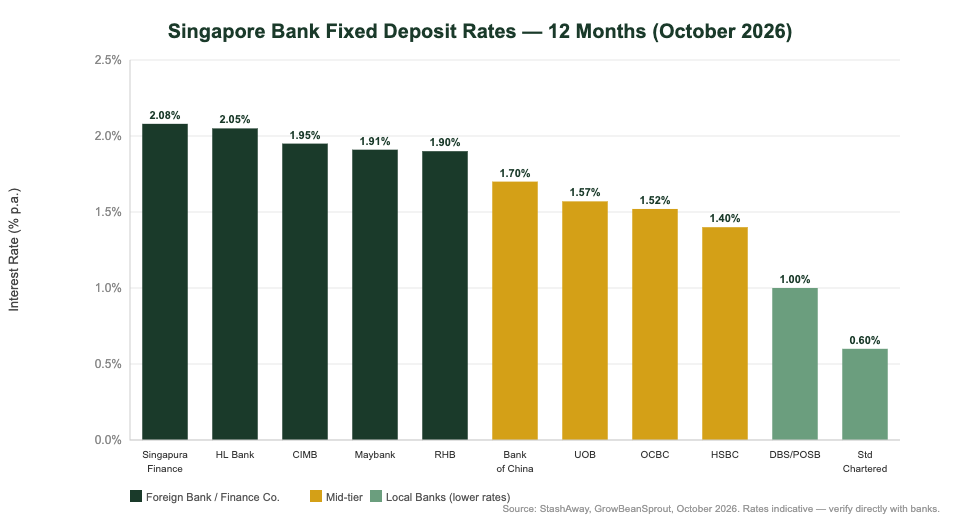
Singapore bank 12-month FD rates, October 2026. Source: StashAway, GrowBeanSprout. Rates indicative only.
Local Singapore Banks: DBS, UOB, OCBC
Singapore’s three local banks — DBS/POSB, UOB, and OCBC — offer the convenience of established branch networks, extensive ATMs, and bundled banking products. However, their fixed deposit rates are typically not the most competitive in October 2026.
DBS / POSB Fixed Deposit
DBS and POSB offer the most accessible entry point with a minimum deposit of just S$1,000. The trade-off: the 12-month rate sits at 1.00% p.a. as of October 2026 — roughly half what some foreign banks offer. A 6-month DBS FD currently yields 0.80% p.a. For those prioritising accessibility over yield, DBS eSavings or the DBS Multiplier Account may be worth comparing alongside the fixed deposit.
UOB Fixed Deposit
UOB offers more competitive rates than DBS, with 12-month placements reaching 1.45%–1.70% p.a. depending on the minimum amount and promotional timing. UOB’s FD offering for senior citizens (above 55) sometimes carries a small premium above the standard rate. The minimum deposit is S$10,000 for most promotional rates.
OCBC Fixed Deposit
OCBC’s 12-month rate in October 2026 stands at 1.40%–1.65% p.a. for online placements, with the higher end requiring S$20,000 or above. OCBC also runs periodic senior citizen promotions. The bank’s Step-Up FD product offers a blended rate across tenors, useful for those uncertain about locking in for a full year.
CIMB Fixed Deposit
CIMB consistently offers some of the best fixed deposit rates in Singapore among established banks. In October 2026, CIMB’s 12-month rate reaches 1.95% p.a. for Preferred tier accounts with S$10,000 minimum. Standard personal banking rates are slightly lower. CIMB’s 6-month rate is 1.65% p.a. — competitive for medium-term placements.
Maybank Fixed Deposit
Maybank offers 1.91% p.a. for 12-month placements with a S$20,000 minimum — one of the stronger rates among broadly available FDs. Maybank also runs bundle promotions that can push effective yields higher when combined with other Maybank products.
RHB Fixed Deposit
RHB’s 12-month rate of 1.90% p.a. (S$20,000 minimum) is competitive and comparable to Maybank. RHB Premier customers may qualify for slightly higher rates. Worth considering alongside CIMB if you have S$20,000+ to place.
Foreign Banks and Finance Companies: Where the Higher Rates Are
Smaller foreign banks and Singapore finance companies — particularly HL Bank (a Malaysian bank with Singapore operations), Bank of China, and finance companies like Hong Leong Finance and Singapura Finance — have consistently offered more competitive FD rates in 2026.
HL Bank (Hong Leong Bank)
HL Bank stands out in October 2026 with rates reaching 2.05% p.a. for 6-month or 12-month placements, and 2.10% p.a. for 24 months — requiring S$10,000 minimum online placement. HL Bank is a licensed bank regulated by MAS and its deposits are covered by SDIC up to S$100,000. Their digital-friendly approach (FD placement via app) makes it accessible without visiting a branch.
Singapura Finance (Vivid Fixed Deposit)
Singapura Finance’s “Vivid Fixed Deposit” tops the 12-month chart at 2.08% p.a. with S$10,000 minimum. Singapura Finance is a licensed finance company regulated by MAS, and deposits are SDIC-protected. Finance companies sometimes carry slightly higher regulatory risk than full banks (they cannot offer current accounts or issue credit cards), but for FD purposes the deposit insurance backstop matters most.
Bank of China (Mobile Banking)
Bank of China Singapore’s mobile banking platform offers 1.60%–1.70% p.a. for 6–12 month placements starting from just S$500. This accessibility makes it attractive for smaller amounts. Higher minimum tiers (S$200,000+) access 2.00% p.a. rates. The S$500 entry point is one of the lowest available for competitive FD rates in Singapore.
Singapore Bank FD Rates by Tenor: 3-Month, 6-Month and 12-Month
Choosing the right tenor is as important as choosing the right bank. Here’s how rates compare across tenors for October 2026, helping you balance yield against flexibility:
| Bank | 3-Month Rate | 6-Month Rate | 12-Month Rate | Min. Deposit |
|---|---|---|---|---|
| HL Bank | N/A | 2.05% | 2.05% | S$10,000 |
| CIMB | 1.35% | 1.65% | 1.95% | S$10,000 |
| Bank of China (mobile) | 1.60% | 1.70% | 1.70% | S$500 |
| UOB | ~0.80% | ~1.10% | 1.45%–1.70% | S$10,000 |
| OCBC | ~0.60% | 1.25% | 1.40%–1.65% | S$20,000 |
| DBS / POSB | ~0.40% | 0.80% | 1.00% | S$1,000 |
Source: Compiled from bank websites and third-party comparison platforms, October 2026. Rates are indicative; actual rates depend on promotional periods and relationship banking status. Check directly with each bank.
Digital Bank Savings Accounts: A Flexible Alternative to FDs
Singapore’s three digital banks — GXS Bank, MariBank, and Trust Bank — don’t offer traditional fixed deposits. Instead, they provide high-yield savings accounts with daily or monthly interest accrual and no lock-in period. For savers who want flexibility, these can outperform most bank FDs while keeping funds instantly accessible.
| Digital Bank | Savings Rate | Lock-In? | SDIC Protected? | Referral Bonus |
|---|---|---|---|---|
| MariBank | 2.70% p.a. | No | Yes (up to S$100K) | S$20 (code: 2DCT80WQ) |
| Trust Bank | 2.40% p.a. | No | Yes (up to S$100K) | S$10 (code: HTWYQP95) |
| GXS Bank | 0.88%–1.75% p.a.* | No | Yes (up to S$100K) | Use code: YONG477 |
*GXS base rate 0.88% p.a.; Boost Pockets up to 1.75% p.a. on targeted savings goals. Rates as at October 2026. MariBank and Trust Bank rates subject to change — check apps for current rates. For a full side-by-side, see our MariBank vs Trust Bank vs GXS comparison.
The key insight: MariBank at 2.70% p.a. currently beats every 3-month FD available at Singapore banks and matches or exceeds most 6-month FDs — while keeping your money instantly accessible. The trade-off is that digital bank rates can change without notice, while a locked FD guarantees the rate for the tenor.
If you are deciding between a 3-month FD and a digital bank savings account, run the numbers for your specific amount. For S$50,000 over 3 months: a 1.60% Bank of China FD earns approximately S$200, while MariBank at 2.70% earns approximately S$338 with full liquidity.
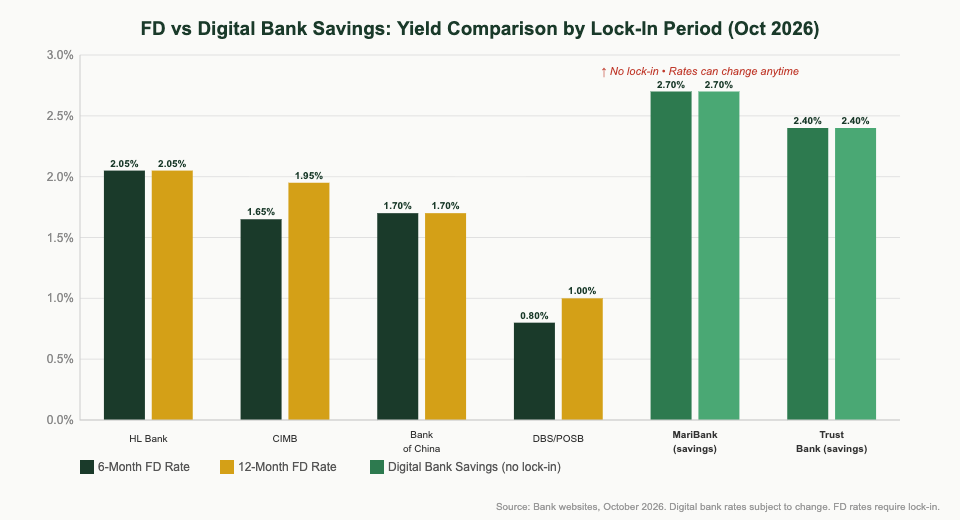
FD vs digital bank savings: yield by lock-in period. MariBank at 2.70% and Trust Bank at 2.40% beat most 6-month FDs. Source: October 2026.
How to Choose the Right Tenor and Bank for Your Fixed Deposit
Choosing a fixed deposit isn’t just about the headline rate. Four factors matter most: your time horizon, minimum deposit constraints, rate lock-in preference, and SDIC eligibility.
Time horizon first. If you need the funds within 3–6 months, a 12-month FD is not appropriate. Early withdrawal typically forfeits all interest earned. Short-term cash is often better served by a digital bank savings account or T-bills rather than a locked FD. For a full comparison of cash instruments, see our Singapore T-bills 2026 guide.
Minimum deposit matters. The most competitive FD rates — HL Bank at 2.05%, Singapura Finance at 2.08% — require S$10,000 minimum. Bank of China is the outlier: a 1.70% p.a. rate for 12 months with just S$500 minimum. For smaller amounts, digital banks are typically the better fit.
Rate trajectory. In October 2026, FD rates have been rising. Whether to lock in a 12-month rate or stay flexible with a 3-month ladder depends on your view of Singapore’s rate environment. Those using Singapore Savings Bonds as an alternative can find flexible redemption with government-backed security — SSBs allow monthly redemption and are backed by the Singapore government.
Concentration risk. SDIC covers up to S$100,000 per depositor per scheme member. If your FD exceeds S$100,000, consider spreading across two or more SDIC member institutions. This is particularly relevant for those placing S$200,000+ to access Bank of China’s highest rate tier.
Is Your Singapore Bank FD Money Safe? SDIC Deposit Insurance
All Singapore banks and finance companies listed in this article are SDIC (Singapore Deposit Insurance Corporation) scheme members. This means your SGD deposits — including fixed deposits — are insured up to S$100,000 per depositor per scheme member in the unlikely event of a bank failure.
This covers all three digital banks (GXS, MariBank, Trust Bank) as MAS-licensed full banks. Finance companies like Hong Leong Finance and Singapura Finance are also covered under the SDIC scheme. Standard Chartered, Citibank, HSBC, Bank of China, and other foreign banks with MAS operating licences are likewise SDIC members.
The S$100,000 limit means a S$150,000 FD at a single bank has S$50,000 of uninsured exposure. The practical mitigation: split large FD placements across two SDIC member institutions. For additional reading on deposit safety, see our dedicated guide on Singapore FD rates 2026, which covers SDIC in more detail alongside rate trends throughout the year.
Looking for passive income beyond fixed deposits? Our passive income Singapore guide covers S-REITs, dividend stocks, and other income-generating instruments that may suit longer investment horizons.
Frequently Asked Questions about Singapore Bank Fixed Deposit Rates
Which Singapore bank has the highest fixed deposit rate in October 2026?
As of October 2026, HL Bank (Hong Leong Bank Singapore) offers 2.10% p.a. for a 24-month placement with a S$10,000 minimum. For 12-month FDs, Singapura Finance leads at 2.08% p.a. Among the three local banks (DBS, UOB, OCBC), UOB offers the most competitive rates at up to 1.70% p.a. Rates change frequently — check each bank directly before placing.
What is a typical fixed deposit interest rate in Singapore right now?
Typical 12-month Singapore bank fixed deposit rates in October 2026 range from 1.00% p.a. (DBS/POSB) to around 1.90%–2.08% p.a. for competitive options like Maybank, RHB, CIMB, HL Bank, and Singapura Finance. The average across major banks for a 12-month placement is roughly 1.50%–1.60% p.a.
Are digital bank savings accounts (MariBank, GXS, Trust Bank) better than fixed deposits?
It depends on your needs. Digital bank savings accounts at MariBank (2.70% p.a.) and Trust Bank (2.40% p.a.) currently offer higher yields than most 3-month and 6-month FDs, with no lock-in. The advantage of a traditional FD is the guaranteed rate for the full tenor — digital bank rates can change any time. For funds you need within 3 months, digital banks typically win on yield. For 12-month placements where you want certainty, a competitive FD (e.g. HL Bank at 2.05%) may be appropriate.
What is the minimum amount needed to open a fixed deposit in Singapore?
Minimums vary significantly by bank. Bank of China (mobile banking) allows FD placements from as little as S$500. Most local banks (DBS, UOB, OCBC) start at S$1,000–S$10,000. Foreign banks and finance companies offering the highest rates (HL Bank, Singapura Finance, Maybank, RHB) typically require S$10,000–S$20,000 minimum. There is no upper limit, though SDIC insurance only covers up to S$100,000 per institution.
Are Singapore bank fixed deposits safe?
Yes. Fixed deposits at all MAS-licensed Singapore banks and finance companies are insured by the Singapore Deposit Insurance Corporation (SDIC) up to S$100,000 per depositor per scheme member. This includes DBS, UOB, OCBC, CIMB, Maybank, HL Bank, Bank of China, and all other banks listed in this article. Finance companies like Hong Leong Finance and Singapura Finance are also SDIC members. For amounts above S$100,000, consider spreading across two institutions to ensure full coverage.
What happens if I withdraw my fixed deposit early?
Early withdrawal of a fixed deposit typically results in full forfeiture of interest — you receive only your principal back. Some banks apply a partial interest penalty (paying a fraction of the accrued interest), but this varies by institution. Always check the break-clause terms before placing a FD. If you anticipate needing the funds before maturity, a digital bank savings account (with daily interest and instant withdrawal) or Singapore Savings Bonds (redeemable any month with interest paid up to that point) may be more appropriate than a fixed deposit.
How do Singapore FD rates compare to T-bills and Singapore Savings Bonds?
In October 2026, the 6-month Singapore T-bill yield is approximately 1.7% p.a. (cut-off yield varies each auction). Singapore Savings Bonds offer a step-up structure averaging around 2.0%+ p.a. over 10 years, with monthly redemption flexibility. Competitive 6-month FDs (Bank of China at 1.70%, HL Bank at 2.05%) now match or surpass T-bill yields for savers willing to accept a lock-in. SSBs remain compelling for long-term cash with government backing. See our T-bills guide for the latest auction results.
Compare All Banks and Pick Your Best FD Rate
Fixed deposit rates at Singapore banks vary by up to 1.5 percentage points for the same tenor. On S$50,000, that’s a difference of S$750 per year. Use our full breakdown above to find the right bank for your amount and time horizon.
While you’re at it, check whether a digital bank savings account suits part of your cash. Use MariBank referral code 2DCT80WQ or Trust Bank referral code HTWYQP95 to get a sign-up bonus when you open an account.
Not financial advice. All rates quoted in this article are indicative as at October 2026 and subject to change. Always verify with the bank directly before making any financial decision.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.