GXS Bank vs OCBC 360: Which Earns More for Your Savings in 2026?
Updated November 2026 · 7 min read
GXS Bank and OCBC 360 are two of the most popular savings options in Singapore — but they suit very different savers. GXS Bank’s Boost Pocket earns up to 2.00% p.a. with zero conditions and no salary crediting required. OCBC 360 goes higher — up to 4.70% p.a. — but demands salary credits of at least S$1,800, monthly card spending, and ideally an insurance or investment product. If you want simplicity, GXS wins. If you can meet OCBC’s criteria, the gap narrows significantly.
Not financial advice. All figures are for educational reference only. Data as at November 2026 unless noted.
At a Glance: GXS Bank vs OCBC 360
Before we dive into the detail, here is how the two accounts stack up on the numbers that matter most to everyday savers.
| Feature | GXS Bank Boost Pocket | OCBC 360 Account |
|---|---|---|
| Maximum rate | 2.00% p.a. (18-month tenure) | 4.70% p.a. (all bonuses met, promo rate to Dec 2026) |
| Practical rate (no Insure/Invest) | 2.00% p.a. (no conditions needed) | 2.20% p.a. (salary + save promo + spend) |
| Conditions required | None | Salary ≥S$1,800, card spend ≥S$500/month, monthly balance growth ≥S$500 |
| Balance cap for bonuses | S$95,000 (across all Boost Pockets) | S$100,000 (bonuses apply to first S$100k only) |
| Lock-in period | 1 to 18 months (tenure-based) | None (conditions are monthly, not a lock-in) |
| Minimum deposit | S$100 per pocket | S$3,000 (fall-below fee applies below this) |
| Monthly fees | None | S$2/month if balance below S$3,000 (waived year 1) |
| SDIC deposit insurance | Yes (up to S$100,000) | Yes (up to S$100,000) |
Source: GXS Bank via Beansprout (3 Nov 2026), OCBC Bank via Beansprout (4 Aug 2026). Rates subject to change without notice.
GXS Bank Boost Pocket: Rates and How It Works
GXS Bank is a fully digital bank licensed by the Monetary Authority of Singapore (MAS), backed by the Grab-Singtel consortium. Unlike traditional banks, GXS imposes no salary crediting requirement, no minimum card spend, and no complex hoops to jump through. Its flagship savings product — the Boost Pocket — works like a tenure-based time deposit: the longer you commit your funds, the higher the rate you earn.
Boost Pockets earn daily interest at the total rate shown below. The bonus portion above the base 0.88% p.a. is paid only on maturity. If you withdraw early, you forfeit the bonus interest above the base rate. You can open up to eight Boost Pockets simultaneously, with a minimum of S$100 per pocket and a total cap of S$95,000 across all pockets.
GXS Bank Boost Pocket Rates (November 2026)
| Tenure | Total Rate p.a. | Annualised interest on S$50,000 |
|---|---|---|
| 1 month | 1.01% p.a. | S$505 |
| 3 months | 1.22% p.a. | S$610 |
| 4 months | 1.40% p.a. | S$700 |
| 8 months | 1.70% p.a. | S$850 |
| 12 months | 1.75% p.a. | S$875 |
| 18 months | 2.00% p.a. | S$1,000 |
Source: GXS Bank via Beansprout, 3 November 2026. Interest annualised for comparison; actual payout is at maturity for the Boost Pocket’s tenure. Minimum S$100 per pocket, total cap S$95,000 across all Boost Pockets.
The GXS Saving Pocket (not to be confused with Boost Pocket) earns 1.20% p.a. with no tenure lock-in — a handy mid-tier option for funds you may need to access within days. The standard Main Account rate is 0.88% p.a., also with no lock-in.
GXS Bank First Boost promo (until 31 December 2026): New customers who open a 3-month Boost Pocket named “FIRST BOOST” with at least S$5,000 of fresh funds receive a S$20 cashback, lifting the effective return to roughly 2.82% p.a. on that S$5,000 tranche. Use referral code YONG477 when signing up for GXS Bank to claim any available sign-up bonuses. Promo subject to eligibility and availability — verify on the GXS Bank app before proceeding.
OCBC 360: Rates and Bonus Categories
The OCBC 360 Account is one of Singapore’s most established high-yield savings accounts, offered by one of the country’s three major local banks. Unlike GXS Bank’s straightforward Boost Pocket, the OCBC 360 operates on a tiered bonus system — the more products and services you use with OCBC, the higher your effective interest rate. The base rate is a mere 0.05% p.a., but stacking bonus categories can lift it substantially for the first S$100,000 of your balance.
OCBC 360 Bonus Interest Rate Tiers (November 2026)
| Bonus Category | Monthly Criteria | Rate — first S$75k | Rate — next S$25k |
|---|---|---|---|
| Salary | Credit ≥S$1,800/month via GIRO/FAST/PayNow | 1.00% p.a. | 2.00% p.a. |
| Save ⚡ promo to 31 Dec 2026 | Avg daily balance up ≥S$500 month-on-month | 0.50% p.a. | 1.10% p.a. |
| Spend | Spend ≥S$500/month on selected OCBC cards | 0.25% p.a. (flat on first S$100k) | |
| Insure | Buy eligible OCBC insurance (≥S$2,000 annual premium) | 1.00% p.a. | 2.00% p.a. (12 months) |
| Invest | Buy eligible OCBC investment product (≥S$20,000) | 1.00% p.a. | 2.00% p.a. (12 months) |
| Grow | Maintain avg daily balance ≥S$250,000 | 1.20% p.a. (flat on first S$100k) | |
Source: OCBC Bank via Beansprout, 4 August 2026. Promo Save rate valid 1 Aug–31 Dec 2026; standard Save rate reverts to 0.40%/0.40% after 31 Dec 2026. Insure and Invest bonuses apply for 12 months from product purchase date.
The maximum effective rate of 4.70% p.a. is achievable if you meet Salary + Save (promo) + Spend + Insure + Invest simultaneously. For most salaried Singaporeans without an insurance or investment purchase, the realistic practical maximum is 2.20% p.a. during the Save promo period (until 31 December 2026), falling to around 1.95% p.a. from January 2027.
For a full breakdown of every OCBC 360 bonus tier and how to calculate your personalised effective rate, see our detailed OCBC 360 interest rate guide for November 2026.
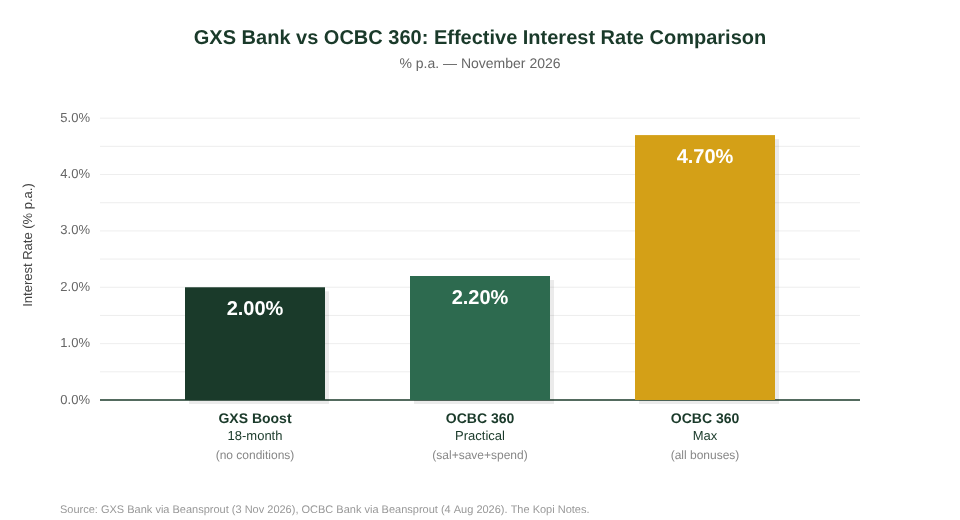
GXS Boost Pocket vs OCBC 360 effective rates at different condition levels. Source: GXS Bank, OCBC Bank (November 2026). The Kopi Notes.
Head-to-Head Rate Comparison
The most useful comparison isn’t the theoretical maximum — it’s the rate you’ll actually earn based on your financial situation. Here is how the two accounts compare across three common scenarios.
Scenario 1: Salary Crediting + Card Spend Only
For a salaried Singaporean who credits at least S$1,800 to OCBC and spends at least S$500/month on an eligible OCBC card, the OCBC 360 earns 2.20% p.a. with the promo Save bonus active. That is marginally ahead of GXS Boost Pocket’s 2.00% p.a. (18-month), but demands active management every month. Missing the Save criteria in any month — a large purchase, a holiday withdrawal, an unusually expensive month — drops the rate to 1.70% p.a. (Salary + Spend only). GXS Bank’s 2.00% p.a. remains unchanged regardless of your monthly spending or saving behaviour.
Scenario 2: Adding Insurance or Investment
This is where OCBC 360 pulls clearly ahead. Adding the Insure bonus by buying an eligible OCBC insurance policy (minimum S$2,000 annual premium) boosts the effective rate to 3.45% p.a. for 12 months. Add both Insure and Invest (minimum S$20,000 in eligible investment products), and the rate reaches 4.70% p.a. — more than double GXS Bank’s maximum.
That said, insurance and investment products should be evaluated on their own merits first, not as vehicles to unlock savings bonuses. If you were planning to buy insurance anyway and OCBC is competitive, the bonus interest is a genuine benefit worth factoring in.
Scenario 3: Zero Monthly Conditions
GXS Bank wins outright. No salary crediting, no minimum card spend, no monthly balance growth requirement. Simply open a Boost Pocket, choose your tenure, and deposit your savings. The 18-month rate of 2.00% p.a. is competitive with OCBC 360’s practical rate and far higher than what OCBC 360 offers to those who cannot reliably meet the monthly criteria.
This makes GXS Bank particularly well-suited to freelancers, self-employed individuals, retirees, and anyone with an irregular income pattern who can’t guarantee monthly OCBC salary crediting.
Real-Money Scenarios: S$30,000, S$75,000 and S$100,000
Abstract percentages can obscure the real-dollar impact. Here is how much interest each account earns annually at three common savings balance levels.
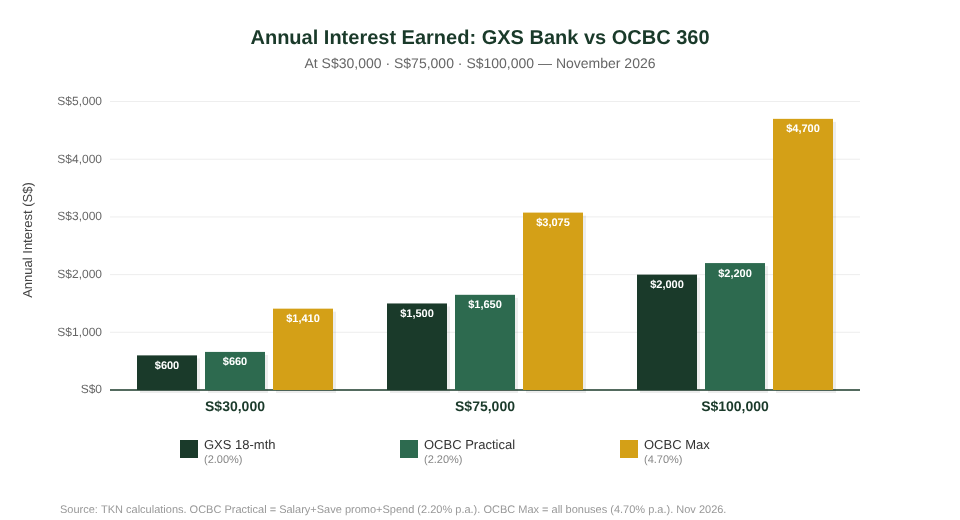
Annual interest earned at three balance levels. OCBC “Practical” = Salary + Save promo + Spend (2.20% p.a.). OCBC “Max” = all bonuses (4.70% p.a.). GXS = 18-month Boost Pocket (2.00% p.a.). Source: TKN calculations, November 2026.
| Balance | GXS 18-mth Boost (2.00% p.a., no conditions) |
OCBC 360 Practical (2.20% p.a., sal+save+spend) |
OCBC 360 Max (4.70% p.a., all bonuses) |
|---|---|---|---|
| S$30,000 | S$600/year | S$660/year | S$1,410/year |
| S$75,000 | S$1,500/year | S$1,650/year | S$3,075/year |
| S$100,000 | S$2,000/year | S$2,200/year | S$4,700/year |
Figures are illustrative. OCBC 360 “Practical” uses promo Save rate valid to 31 Dec 2026. GXS Boost Pocket total cap is S$95,000 (excess earns 0.88% p.a.). OCBC 360 bonus rates apply to first S$100,000 only. All figures rounded. Source: TKN calculations, November 2026.
The table makes the trade-offs clear. At S$100,000, the OCBC 360 at maximum earns S$4,700 per year — more than double GXS Boost Pocket’s S$2,000. But achieving that maximum requires purchasing both insurance products (minimum S$2,000 annual premium) and investment products (minimum S$20,000) through OCBC. Without those, OCBC earns S$2,200 versus GXS’s S$2,000 — a difference of just S$200 per year for considerably more administrative complexity.
For balances above S$95,000, GXS Bank’s Boost Pocket cap means the excess earns only 0.88% p.a. in the Main Account. If you have more than S$95,000 to park, consider splitting between accounts — including Singapore T-bills or Singapore Savings Bonds, which may offer comparable rates with capital flexibility. Use our free Singapore retirement planning calculator to model how different savings rates affect your long-term wealth.
Which Account Should You Choose?
The right answer depends less on which headline rate is higher and more on your individual circumstances and banking habits.
Choose GXS Bank Boost Pocket If:
- You are a freelancer, self-employed, or retiree with irregular income
- You cannot reliably credit a salary of at least S$1,800 to OCBC every month
- You want to set-and-forget without worrying about monthly maintenance criteria
- Your emergency fund or savings are between S$10,000 and S$95,000
- You prefer a fully digital banking experience with no branch visits required
- You already bank with another institution and want a separate, higher-yield savings vehicle
Choose OCBC 360 Account If:
- You are salaried and can reliably credit at least S$1,800 to OCBC each month
- You already spend at least S$500/month on a credit card and can switch to an eligible OCBC card
- You are willing to grow your OCBC balance by S$500/month to earn the Save bonus
- You are open to purchasing insurance or investment products through OCBC for the higher bonus tiers
- You want a full-service banking relationship with branch access, wealth management, and a broad product suite
Consider Using Both Accounts Together
Many Singapore savers use both accounts as a complementary pair. A common strategy: credit your salary to OCBC 360 to earn the Salary bonus, keep an OCBC card for the Spend bonus, and park additional savings that you don’t need on a monthly basis in GXS Boost Pockets. The two products are not mutually exclusive — they serve different financial purposes within the same household.
If you’re still narrowing down the right digital bank, our comparisons of GXS Bank vs Trust Bank and GXS Bank vs MariBank may also be useful. For those weighing savings accounts against fixed deposits, the GXS Bank vs moomoo Cash Plus comparison is worth reading too.
The Verdict
GXS Bank and OCBC 360 are both strong savings options, but they are designed for fundamentally different types of savers. GXS Bank’s Boost Pocket offers a clean, no-conditions 2.00% p.a. for 18 months, making it the go-to for anyone who wants a competitive rate without monthly admin. OCBC 360’s ceiling is higher — up to 4.70% p.a. — but hitting that ceiling demands salary crediting, card spending, monthly balance growth, and insurance or investment purchases simultaneously.
For most salaried Singaporeans who can meet the core OCBC conditions (salary + save + spend), OCBC 360 edges slightly ahead at 2.20% p.a. with the promo rate active until December 2026. For everyone else — especially freelancers, retirees, or those who find bank-hopping administrative conditions tiresome — GXS Bank Boost Pocket’s 2.00% p.a. with zero conditions is a compelling and stress-free alternative.
Always verify rates directly with GXS Bank and OCBC before making any financial decision. Rates and promotions change. This article is for informational purposes only and does not constitute financial advice.
Frequently Asked Questions
Is GXS Bank or OCBC 360 better for someone with no salary crediting?
What is the maximum effective interest rate on GXS Bank in 2026?
Does OCBC 360 have a lock-in period?
Can I use GXS Bank and OCBC 360 at the same time?
When does the OCBC 360 Save promo bonus end?
Is GXS Bank safe? Is my money insured?
What referral code can I use for GXS Bank?
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.