GXS Bank vs Trust Bank 2026: Which Digital Bank Is Better for Singaporeans?
Two MAS-licensed digital banks, one clear comparison — savings rates, features, and who should pick which in November 2026.
GXS Bank (backed by Grab and Singtel) and Trust Bank (backed by Standard Chartered and NTUC FairPrice Group) are both MAS-licensed digital banks with SDIC deposit insurance up to S$100,000. GXS offers up to 1.75% p.a. on its Boost Pockets with no conditions, climbing to 2.40% p.a. with the November 2026 Holiday Boost promo. Trust Bank’s Flex plan matches at 2.40% p.a. but requires salary crediting and regular card spend to unlock the top tier.
Not financial advice. All figures are for educational reference only. Data as at November 2026 unless noted.
Quick Answer: GXS Bank vs Trust Bank
For most Singapore savers who want a genuinely no-fuss savings rate, GXS Bank edges ahead. Its Boost Pockets deliver up to 1.75% p.a. on a 5-month tenor with zero qualifying conditions — no salary crediting, no minimum card spend, no union membership required. Lock in a Boost Pocket and the rate is guaranteed for the full tenor.
Trust Bank’s Flex plan can reach 2.40% p.a. on paper, but unlocking the top tier requires you to credit your salary, spend on the Trust debit card each month, and — for the best rates — be an NTUC union member. Its achievable no-effort rate sits around 0.75–0.85% p.a., well below GXS’s floor.
That said, Trust Bank is the stronger pick if you are already embedded in the NTUC/FairPrice ecosystem or if the Trust+ customisable savings plan fits your cash-management style better than fixed tenors. Both banks are equally safe: full MAS digital banking licences, SDIC-insured up to S$100,000 per depositor.
See our in-depth GXS Bank complete guide and Trust Bank 2026 review for full detail on each bank individually.
Key Differences at a Glance
| Feature | GXS Bank | Trust Bank |
|---|---|---|
| Backed by | Grab + Singtel | Standard Chartered + NTUC FairPrice Group |
| MAS Licence | Full Digital Bank (DFB) | Full Digital Bank (DFB) |
| SDIC Insurance | Up to S$100,000 | Up to S$100,000 |
| Base/No-Effort Rate | 0.88% p.a. (Flex Save) | ~0.75–0.85% p.a. |
| Best No-Condition Rate | 1.75% p.a. (5-month Boost Pocket) | ~0.85% p.a. |
| Best Headline Rate | 2.40% p.a. (Holiday Boost promo, Nov 2026) | 2.40% p.a. (Flex plan with full qualifying steps) |
| Rate Conditions? | None for Boost Pockets | Salary credit + card spend + Union |
| Rate Certainty | Locked for entire tenor | Variable (can change) |
| Debit Card | Yes | Yes (Visa) |
| Ecosystem Perks | GrabPay rewards | FairPrice Group rewards, NTUC union benefits |
| Referral Code | YONG477 | HTWYQP95 |
| Monthly Fee | None | None |
Source: GXS Bank and Trust Bank official rate pages, November 2026. SDIC limit raised to S$100,000 in April 2024.
Interest Rates Compared: GXS Bank vs Trust Bank (November 2026)
GXS Bank Boost Pocket Rates
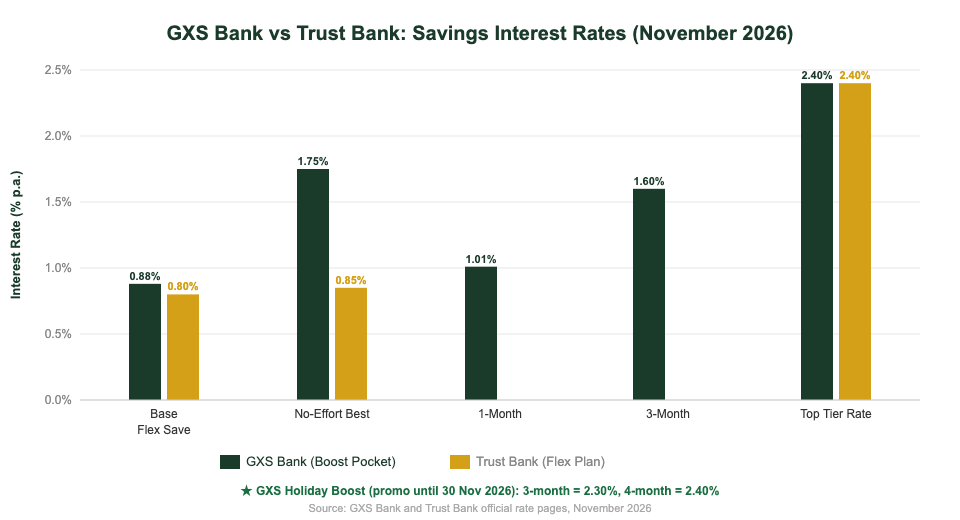
GXS Bank’s key savings product is the Boost Pocket — a fixed-tenor deposit you open inside your GXS Savings Account, earning a higher rate than the flexible Flex Save account. You can open up to 8 Boost Pockets simultaneously, each with its own tenor and rate. The rates below require no salary crediting, no minimum spend, and no qualifying criteria.
| Tenor | Standard Rate (p.a.) | Holiday Boost Promo (until 30 Nov 2026) |
|---|---|---|
| 1 month | 1.01% | — |
| 2 months | 1.50% | — |
| 3 months | 1.60% | 2.30% (name pocket “HOLIDAY BOOST”) |
| 4 months | 1.70% | 2.40% (name pocket “HOLIDAY BOOST”) |
| 5 months | 1.75% | — |
Source: GXS Bank app, November 2026. Holiday Boost requires S$10,000–S$100,000 in fresh funds and pocket named exactly “HOLIDAY BOOST”. See our full Holiday Boost guide for step-by-step instructions.
The Flex Save account (the default flexible bucket) earns 0.88% p.a. with no conditions and no lock-up. It’s the ideal home for your most liquid emergency fund tranche while Boost Pockets work harder on the rest.
For more detail on how GXS Bank Boost Pockets work day-to-day, including whether they are SDIC-insured, read our guide Is GXS Bank safe?
Trust Bank Savings Rates
Trust Bank structures its savings around the Flex plan (or the higher-tier Signature plan for larger balances) and its market-first Trust+ customisable savings offering. The headline rate of up to 2.40% p.a. requires meeting a combination of qualifying criteria each month:
- Credit your salary into Trust Bank
- Spend a minimum amount on your Trust Visa debit card
- NTUC union membership (required for the top interest tier)
Without any of these steps, the base rate sits around 0.75–0.85% p.a. — competitive versus traditional banks, but below GXS’s no-condition 1.01–1.75% Boost Pocket range. The Trust+ plan offers a customisable approach to savings with up to 2.40% p.a. for eligible savers who meet the qualifying thresholds.
Key insight: The gap between headline and achievable rates is what matters most. For a saver who cannot or does not want to credit salary to a digital bank, GXS Bank’s Boost Pockets offer a meaningfully higher effective rate — no game-playing required.
Use our Singapore retirement planning calculator to see how small differences in savings rates compound over a 10-year horizon.
Account Features and Product Range
GXS Bank Account Structure
GXS Bank keeps its product range tight and focused on savings:
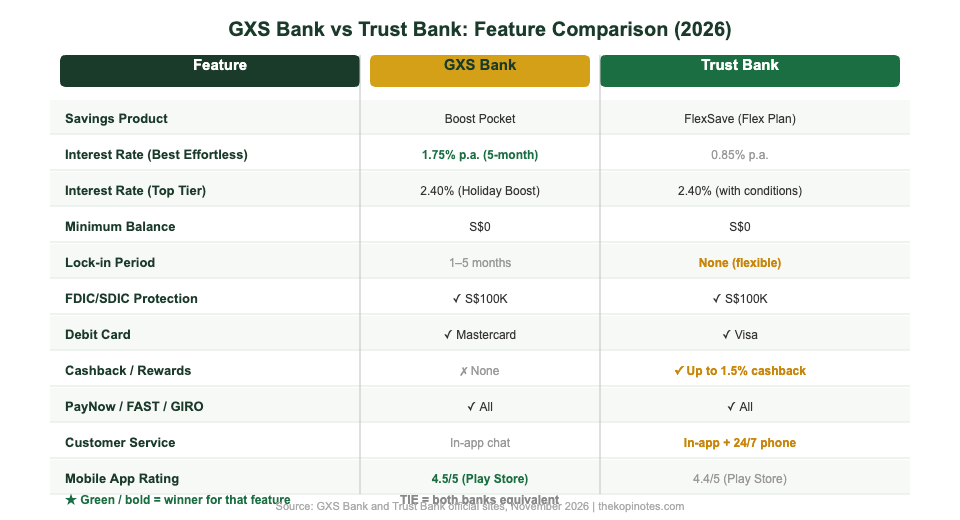
- Flex Save: Fully liquid savings account earning 0.88% p.a. No lock-up, no minimum balance. Best for funds you may need at any time.
- Boost Pockets: Fixed-tenor deposits embedded within your savings account, each earning a higher promotional rate. Open up to 8 simultaneously. Rates are locked for the full tenor — the rate you see when you open the pocket is exactly what you receive.
- Saving Pockets: Goal-based savings pots for specific targets (holiday, renovation, emergency fund).
The Boost Pocket model is effectively a mini fixed deposit with the convenience of a digital savings account. Because it sits inside your GXS account (not at a separate bank), there is no separate application, no branch visit, and no paperwork. You name the pocket, choose the tenor, and the rate is confirmed instantly. All Boost Pockets and Flex Save balances are SDIC-insured in aggregate up to S$100,000 per depositor.
Trust Bank Account Structure
Trust Bank offers a broader set of savings structures geared towards depositors who can and want to fulfil qualifying criteria:
- Standard Savings Account: Base rate savings; accessible to all. Lower rates than the Flex plan.
- Flex Plan: Up to 2.40% p.a. with qualifying criteria (salary credit, card spend, Union membership). Tiered — the more criteria you meet, the higher the rate.
- Signature Plan: Higher-tier plan for larger balances, same qualifying structure.
- Trust+: Trust Bank’s market-first customisable savings plan. Allows you to tailor your savings structure with more flexibility, earning up to 2.40% p.a. for eligible members.
Trust Bank’s debit card is a Visa card that works across the FairPrice Group ecosystem — earning linkpoint rewards on FairPrice supermarket spending and petrol rebates at Esso. For NTUC union members, the bank represents a meaningful extension of their existing membership benefits.
Fees, Access, and Ecosystem Perks
| Category | GXS Bank | Trust Bank |
|---|---|---|
| Monthly fee | None | None |
| Minimum balance | None | None |
| PayNow/FAST | Yes | Yes |
| Debit card | Yes (Mastercard/Visa) | Yes (Visa) |
| Early withdrawal (Boost Pocket) | May forfeit bonus interest on that pocket | Not applicable (tiered rate structure) |
| Ecosystem tie-in | Grab, GrabPay | NTUC FairPrice, Esso, Union membership |
| CPF / SRS compatibility | No (cash only) | No (cash only) |
| Customer service | In-app chat; no branch | In-app chat; no branch |
Source: GXS Bank and Trust Bank product pages, November 2026.
Neither bank accepts CPF Ordinary Account, Supplementary Retirement Scheme (SRS), or any CPF monies — both are cash-only savings products. For CPF and SRS investment options, the Singapore Savings Bonds guide and our Endowus referral page cover suitable alternatives.
Who Should Pick Which?
Pick GXS Bank if you:
- Want the highest guaranteed rate with zero qualifying steps — Boost Pockets deliver 1.01–1.75% p.a. with no salary crediting required
- Are comfortable with fixed tenors of 1–5 months — the locked rate is the upside; illiquidity for that period is the trade-off
- Want to take advantage of the November 2026 Holiday Boost promo (2.3–2.4% p.a.) before it expires 30 Nov 2026 — use referral code YONG477 to open an account
- Already use Grab or GrabPay regularly and want your savings in the same ecosystem
- Have S$10,000–S$100,000 in fresh funds to deploy into the Holiday Boost promo
Pick Trust Bank if you:
- Are an NTUC union member — you unlock higher rates and FairPrice Group rewards that GXS cannot match
- Credit your salary and regularly spend at FairPrice, Cheers, or Esso — your everyday habits naturally fulfil the qualifying criteria
- Want the Trust+ customisable savings plan — the market-first structure suits savers who prefer more plan control over fixed-tenor locks
- Prefer a Visa debit card with direct FairPrice linkpoint integration
- Use referral code HTWYQP95 for Trust Bank sign-up bonuses
Can you hold both?
Yes — there is no restriction on holding GXS Bank and Trust Bank simultaneously. Many Singapore savers use GXS Bank Boost Pockets for the guaranteed locked rate on a portion of their savings, and Trust Bank for their primary salary crediting and FairPrice card spending. The combined strategy lets you optimise rates across both banks without being locked into a single platform.
For savers wanting higher returns beyond digital bank rates, our guides on Syfe and the Singapore Savings Bonds cover options with 3–4%+ returns for longer time horizons.
Frequently Asked Questions
Is GXS Bank safe? Are deposits insured?
Yes. GXS Bank holds a full MAS Digital Full Bank (DFB) licence and is a member of the Singapore Deposit Insurance Corporation (SDIC) scheme. Your Flex Save and Boost Pocket balances are insured in aggregate up to S$100,000 per depositor. The SDIC limit was raised from S$75,000 to S$100,000 in April 2024. GXS Bank is backed by Grab and Singtel — two SGX-listed and NASDAQ-listed blue-chip companies respectively.
Is Trust Bank safe? Is it SDIC-insured?
Yes. Trust Bank also holds an MAS Digital Full Bank licence and participates in the SDIC scheme. Deposits are insured up to S$100,000 per depositor. Trust Bank is backed by Standard Chartered (a global bank with over 160 years of history) and NTUC FairPrice Group (Singapore’s largest retail co-operative). Both institutions are well-capitalised and regulated entities.
Which bank pays a higher rate right now (November 2026)?
On a no-conditions basis, GXS Bank pays more. Its standard 5-month Boost Pocket earns 1.75% p.a. with no salary crediting, no card spend, and no union membership required. Trust Bank’s no-effort base rate sits around 0.75–0.85% p.a. If you are willing to credit salary and meet Trust Bank’s qualifying criteria (including NTUC union membership), both banks can reach 2.40% p.a. as a headline rate. The November 2026 Holiday Boost on GXS also hits 2.40% p.a. for 4-month fresh funds — but that promo ends 30 November 2026.
Can I open accounts at both GXS Bank and Trust Bank at the same time?
Yes, there is no restriction. You can hold both simultaneously. A popular strategy is to credit salary into Trust Bank to qualify for the Flex plan rate, while parking additional savings in GXS Boost Pockets for a guaranteed locked-in rate on the fixed-tenor tranche. The two banks serve slightly different savings jobs, so holding both is a sensible approach for savers wanting to maximise returns across their full cash position.
What happens if I withdraw early from a GXS Boost Pocket?
If you need funds from a GXS Boost Pocket before the tenor ends, you may forfeit the bonus interest component for that pocket — the standard Flex Save rate may apply instead, depending on GXS’s current terms. Because of this, GXS recommends only locking funds you are confident you will not need during the pocket’s tenor. For funds you may need at short notice, keep them in the Flex Save account which has no lock-up and earns 0.88% p.a.
What is Trust+? How is it different from the standard Trust Bank savings account?
Trust+ is Trust Bank’s market-first customisable savings plan — it allows eligible savers to tailor the structure of their savings goals and qualifying criteria more flexibly than the standard Flex plan. It can earn up to 2.40% p.a. for qualifying members. The standard Trust Bank savings account (without Trust+ or the Flex plan) earns a base rate of around 0.75–0.85% p.a. Trust+ is a newer product designed for savers who want more control over their savings journey while remaining within the Trust Bank ecosystem.
How do I get a GXS Bank or Trust Bank referral bonus?
To open a GXS Bank account and earn a referral bonus, use referral code YONG477 during sign-up in the GXS app. For Trust Bank, use referral code HTWYQP95 when registering in the Trust Bank app. Referral bonuses are subject to terms and conditions and may change — check the respective apps for current bonus amounts at the time of sign-up. Both banks are available to Singapore Citizens, PRs, and eligible Employment Pass holders.
Open GXS Bank or Trust Bank Today
Both banks offer no-fee accounts and sign-up referral bonuses. Use these codes when registering.
| GXS Bank | Code: YONG477 |
| Trust Bank | Code: HTWYQP95 |
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.