BOC SmartSaver Interest Rate (November 2026): How the 4.60% p.a. Headline Really Works
Every bonus tier, the S$1,500 balance rule, and what S$50,000 to S$200,000 actually earns.
The Bank of China SmartSaver pays up to 4.60% p.a. on the first S$100,000, but only while you hold a qualifying insurance policy that triggers the 3.00% wealth bonus for six months. Without it, the realistic ceiling is 1.60% p.a.: 0.10% prevailing, 0.90% for spending S$2,500 a month, 0.50% for a S$3,000 salary and 0.10% for three bill payments.
Not financial advice. All figures are for educational reference only. Data verified as at 16 November 2026 against Bank of China Singapore’s official SmartSaver page (rates effective from 1 November 2025).
Table of Contents
Contents — Click to expand
- How the BOC SmartSaver Interest Rate Works
- BOC SmartSaver Interest Rate Table (November 2026)
- The 3.00% Wealth Bonus: Read This Before Chasing 4.60%
- How Much Interest You Really Earn
- Balances Above S$100,000
- Minimum Balance, Fees and Eligibility
- Who the SmartSaver Suits
- Where Else to Park Your Cash
- Frequently Asked Questions
How the BOC SmartSaver Interest Rate Works
The SmartSaver is Bank of China Singapore’s bonus-interest savings account. Like the other “do more, earn more” accounts at the big banks, it starts you on a low prevailing rate and stacks bonus interest on top each month you hit certain actions. The structure has five moving parts, and you can mix and match them.
The prevailing rate is 0.10% p.a. and applies to your entire balance, whatever you do. On top of that, BOC pays bonus interest on the first S$100,000 for four kinds of activity: buying a qualifying insurance policy (the wealth bonus), card spending, salary crediting and bill payments. There is also an extra savings bonus for money above S$100,000, which we cover further down.
Two features make SmartSaver a little different from accounts like the OCBC 360 interest rate tiers. First, the card spend bonus has two levels, so a household that puts S$2,500 or more a month on cards gets noticeably more than one that spends S$750. Second, the salary threshold is S$3,000 a month, which is higher than some rival accounts, so fresh graduates on lower pay may miss that leg.
One more rule matters: BOC says you need a minimum monthly average balance of S$1,500 to enjoy bonus interest at all. If your average dips below that in a given month, you fall back to the prevailing rate for that month even if you met every other criterion.
BOC SmartSaver Interest Rate Table (November 2026)
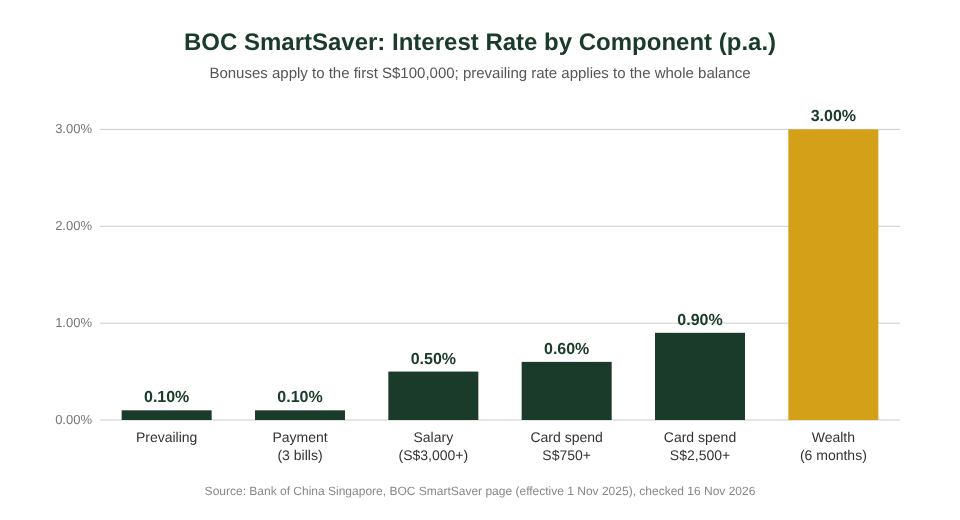
Here is every component exactly as Bank of China lists it on the official BOC SmartSaver page. All rates are per annum, and the bonus rates apply to the first S$100,000 of your balance unless stated.
| Component | What you need to do | Rate (p.a.) |
|---|---|---|
| Prevailing rate | Nothing: applies to the entire balance | 0.10% |
| Wealth bonus | Buy a qualifying insurance policy (see minimums below); paid for 6 consecutive months | 3.00% |
| Card spend bonus (tier 1) | Spend S$750 to below S$2,500 a month on debit or credit card | 0.60% |
| Card spend bonus (tier 2) | Spend S$2,500 or more a month on debit or credit card | 0.90% |
| Salary crediting bonus | Credit a salary of S$3,000 or more via GIRO, with “IBG-SALA” or “SALA” in the description | 0.50% |
| Payment bonus | Make 3 bill payments of at least S$30 each via GIRO or Internet/Mobile Banking | 0.10% |
| Extra savings bonus | Meet any one of card spend, salary or payment; paid on balance above S$100,000 up to S$1,000,000 | 0.50% |
Source: Bank of China Singapore, BOC SmartSaver page (effective 1 November 2025), checked 16 November 2026
Add the top tier of each first-S$100,000 bonus to the prevailing rate and you get the advertised headline: 0.10% + 3.00% + 0.90% + 0.50% + 0.10% = 4.60% p.a. That number is real, but it depends heavily on the wealth bonus, which is the subject of the next section.
Bank of China states that the rates are subject to change without prior notice. The current set has been in force since 1 November 2025, so it has held for a full year. Check the official page before you move money, because savings rates across Singapore have been drifting down as interest rates ease.
The 3.00% Wealth Bonus: Read This Before Chasing 4.60%
The wealth bonus is worth more than every other bonus combined, so it is worth understanding exactly what it asks of you. BOC pays 3.00% p.a. on the first S$100,000 for six consecutive months when you buy a qualifying insurance policy through the bank. The minimum premiums are steep:
| Policy type | Minimum premium to qualify |
|---|---|
| Single premium | S$150,000 equivalent |
| 5-year regular premium | S$24,000 equivalent in annual premiums |
| 10-year regular premium | S$12,000 equivalent in annual premiums |
Source: Bank of China Singapore, BOC SmartSaver page (effective 1 November 2025), checked 16 November 2026. Not available for purchases made with CPF Investment funds.
Put those numbers next to the reward. Six months of 3.00% on S$100,000 is about S$1,500 of extra interest. To earn it, you would commit at least S$12,000 a year for ten years (S$120,000 in total) or S$24,000 a year for five years, or hand over S$150,000 in one go. BOC also claws the bonus back if you terminate the policy within 12 months.
That makes the wealth bonus a sweetener for people who had already decided to buy that kind of policy from BOC, not a reason to buy one. If you are weighing an endowment or savings plan anyway, run the policy’s own guaranteed and projected returns against alternatives such as T-bills, SSBs or a simple portfolio first. Our Singapore retirement planning calculator helps you see whether locking cash away for 5 to 10 years fits your plan.
For everyone else, treat 1.60% p.a. as the practical maximum on SmartSaver, and 1.30% p.a. as the more typical figure for someone who spends between S$750 and S$2,500 a month on cards.
How Much Interest You Really Earn
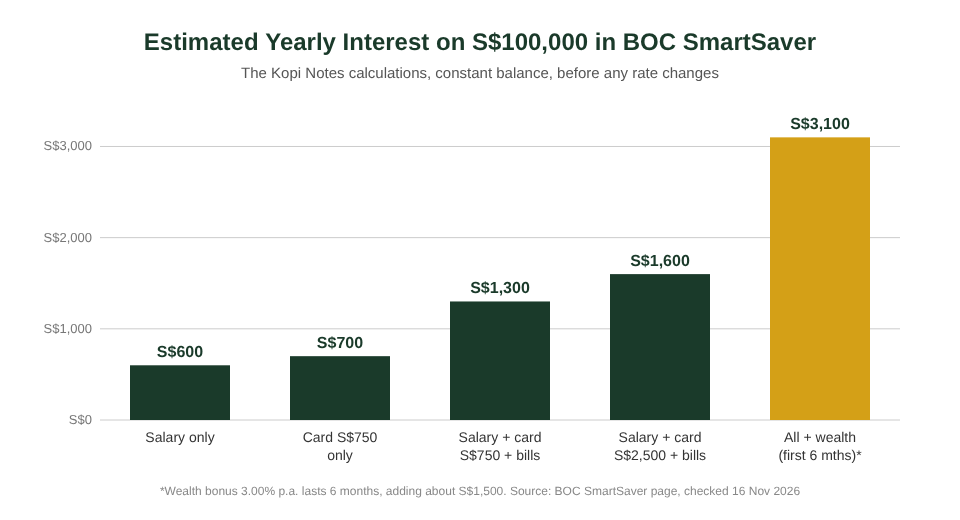
Headline rates are easier to compare once they become dollars. The table below shows The Kopi Notes’ estimates of yearly interest at different balances and activity levels. We assume the balance stays constant for the year, the monthly average stays above S$1,500, and rates do not change. Actual interest will differ if your balance moves or BOC revises rates.
| Scenario (criteria met every month) | Effective rate on first S$100k | S$50,000 balance | S$100,000 balance |
|---|---|---|---|
| No bonus criteria met | 0.10% | S$50 | S$100 |
| Salary only | 0.60% | S$300 | S$600 |
| Card spend S$750+ only | 0.70% | S$350 | S$700 |
| Salary + card S$750+ + 3 bills | 1.30% | S$650 | S$1,300 |
| Salary + card S$2,500+ + 3 bills | 1.60% | S$800 | S$1,600 |
| All of the above + wealth bonus (6 months) | 4.60% for 6 months, 1.60% after | S$1,550 | S$3,100 |
Source: The Kopi Notes calculations using rates from the BOC SmartSaver page, 16 November 2026. Constant balance assumed.
A few things jump out. The jump from “salary only” to “salary, card and bills” more than doubles your interest, because the card leg alone is worth more than the salary leg. Moving from S$750 to S$2,500 of monthly card spend adds only 0.30%, which on S$50,000 is S$150 a year. If reaching S$2,500 means putting spending on a card with weaker rewards, the extra 0.30% may not cover what you give up in cashback or miles.
The bill payment leg is small but cheap to collect. Three bills of at least S$30 each a month (think telco, utilities and insurance via GIRO) earn 0.10% p.a., or S$100 a year on S$100,000.
Balances Above S$100,000
Many bonus accounts stop rewarding you at S$100,000. SmartSaver keeps paying something extra. If you meet any one of the card spend, salary or payment criteria, BOC adds an extra savings bonus of 0.50% p.a. on the balance above S$100,000 up to S$1,000,000. With the 0.10% prevailing rate, that portion earns 0.60% p.a. Above S$1,000,000, only the prevailing rate applies.
Here is how that plays out for a household holding S$200,000 that credits salary, spends S$2,500 a month on cards and pays three bills:
- First S$100,000 at 1.60% p.a.: about S$1,600 a year
- Next S$100,000 at 0.60% p.a.: about S$600 a year
- Total: about S$2,200 a year, an effective 1.10% p.a. on the full S$200,000
0.60% is not exciting, but it beats leaving large sums in an account paying only a base rate. For money above S$100,000 that you do not need instantly, it is still worth comparing against T-bills, fixed deposits and money market funds. Our Bank of China fixed deposit rate guide covers BOC’s own time deposits if you prefer to keep everything at one bank.
Minimum Balance, Fees and Eligibility
SmartSaver’s housekeeping rules are light, but there are three numbers to remember:
| Rule | Detail |
|---|---|
| Minimum initial deposit | S$200 |
| Balance needed for bonus interest | Minimum monthly average balance of S$1,500 |
| Account service charge | S$3 if the monthly average balance falls below S$200 |
| Eligibility | Age 18 and above, with an MCS account at BOC |
| Salary crediting format | Via GIRO, with “IBG-SALA” or “SALA” in the statement description |
Source: Bank of China Singapore, BOC SmartSaver page (effective 1 November 2025), checked 16 November 2026
The salary rule is the one that trips people up. BOC looks for the “IBG-SALA” or “SALA” description, which is how most employers’ payroll GIRO transfers appear. Transfers you make yourself from another bank will not show that code, so they will not count. If you are self-employed or paid in a way that does not carry the salary code, plan on the card and bill legs instead, or look at our list of the best savings accounts without salary credit.
Who the SmartSaver Suits
A good fit if you
- Already credit a salary of S$3,000 or more and can move it to BOC
- Spend at least S$750 a month on cards and are happy to route it through cards that qualify under BOC’s terms
- Keep more than S$100,000 in cash and want the extra 0.50% on the portion above S$100,000
- Were already planning to buy a large insurance policy from BOC, so the wealth bonus is a free extra
Probably not the best fit if you
- Earn under S$3,000 a month or are not salaried, so the salary leg is out of reach
- Prefer to keep your card spending on a dedicated cashback or miles card at another bank
- Hold well under S$50,000, where the dollar difference between accounts is small and simplicity may matter more
- Want flexibility with no monthly conditions to track
Where Else to Park Your Cash
SmartSaver is one of several bonus-interest accounts in Singapore, and each rewards a different mix of habits. If your salary already lands at another bank, compare it with the Standard Chartered Bonus$aver interest rate and the CIMB FastSaver before you switch payroll. Rates change often, so look at each bank’s live page on the day you decide.
If you would rather avoid monthly conditions altogether, digital banks are the simpler route. MariBank, Trust Bank and GXS Bank pay interest without requiring salary crediting or card spend, though their rates and promotions shift regularly. Our best digital bank in Singapore comparison lays out the current options. If you open one, our referral pages list the current sign-up codes: MariBank referral code (2DCT80WQ), Trust Bank referral code (HTWYQP95) and GXS Bank referral code (YONG477).
A common setup is to split the roles: keep your salary and card spending in a bonus account like SmartSaver up to S$100,000, hold an emergency buffer in a no-strings digital bank, and invest longer-term money separately. That way no single account has to do everything.
Frequently Asked Questions
What is the BOC SmartSaver interest rate in November 2026?
Up to 4.60% p.a. on the first S$100,000, made up of the 0.10% prevailing rate plus bonuses for a qualifying insurance purchase (3.00%), card spend (up to 0.90%), salary crediting (0.50%) and bill payments (0.10%). Without the insurance-linked wealth bonus, the maximum is 1.60% p.a. These rates have applied since 1 November 2025.
How much card spend do I need for the SmartSaver bonus?
S$750 a month earns a 0.60% p.a. bonus, and S$2,500 or more earns 0.90% p.a. Spending can be on debit or credit card; check BOC’s terms for which cards and transactions count.
What salary do I need for the BOC SmartSaver salary bonus?
A salary of at least S$3,000 a month credited via GIRO, with “IBG-SALA” or “SALA” in the statement description. This earns a 0.50% p.a. bonus on the first S$100,000.
Is there a minimum balance for BOC SmartSaver?
The initial deposit is S$200. You need a minimum monthly average balance of S$1,500 to earn bonus interest, and BOC charges S$3 a month if your monthly average balance falls below S$200.
Does BOC SmartSaver pay bonus interest above S$100,000?
Yes. If you meet any one of the card spend, salary or payment criteria, you earn an extra 0.50% p.a. on the balance above S$100,000 up to S$1,000,000, plus the 0.10% prevailing rate. Above S$1,000,000, only the prevailing rate applies.
How long does the 3.00% wealth bonus last?
Six consecutive months. It requires a qualifying insurance purchase with high minimum premiums (for example S$12,000 a year for a 10-year regular premium policy) and is clawed back if you terminate the policy within 12 months. It is not available for CPF Investment purchases.
How much interest does S$100,000 earn in BOC SmartSaver?
About S$1,300 a year if you credit salary, spend S$750 or more on cards and pay three bills monthly, or about S$1,600 a year if your card spend reaches S$2,500. These are The Kopi Notes estimates assuming a constant balance and unchanged rates.
Disclaimer: This article was researched and drafted with the help of AI tools and checked against Bank of China Singapore’s official BOC SmartSaver page (rates effective from 1 November 2025) on 16 November 2026. It is general information, not financial advice. Interest rates, eligibility rules and promotions can change without notice. Always confirm the latest terms on the bank’s website before opening an account or moving money. The Kopi Notes may earn referral rewards from some links.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.