ISP Legacy Rider Singapore: Must You Switch to the New Rider by April 2028?
Based on MOH Parliamentary Q&A, September 2026 — find out which group you fall into and what you need to do.
Not all ISP rider holders have to switch to the new rider structure by April 2028. If you bought your rider before 27 November 2025, your insurer — not MOH — decides when and how you transition. Only those who bought between 27 November 2025 and 31 March 2026 are mandated to move to a compliant rider by their next renewal from April 2028. Those who bought from April 2026 onwards are already on the new rider. Data verified as at 24 September 2026.
Not financial advice. All figures are for educational reference only. Source: MOH Parliamentary Q&A, 8–9 September 2026.
- MOH only mandates a transition deadline for riders bought between 27 Nov 2025 and 31 Mar 2026 — they must switch by their next renewal after April 2028.
- If you bought your rider before 27 Nov 2025, your insurer decides — there is no government-set deadline for you.
- New riders are 35–40% cheaper in premiums, but your co-payment cap doubles from $3,000 to $6,000 per year.
What Changed in April 2026
From 1 April 2026, new ISP riders in Singapore no longer cover the minimum deductible on your Integrated Shield Plan. This was the core change MOH pushed through to reduce over-servicing in private hospitals.
Before the change, some riders would cover virtually everything — your deductible included. That meant many policyholders had zero skin in the game when choosing treatments. Hospitals and doctors had little incentive to keep bills low.
MOH’s solution: make you absorb the deductible yourself. The co-payment cap also doubled, from $3,000 to $6,000 per year. The trade-off? Premiums dropped by an average of 35% to 40% compared to legacy riders with maximum coverage, depending on your age band.
If you want a full breakdown of the new co-payment rules and real bill examples, check our detailed guide on the new ISP rider co-payment breakdown.
The Three Groups of Policyholders
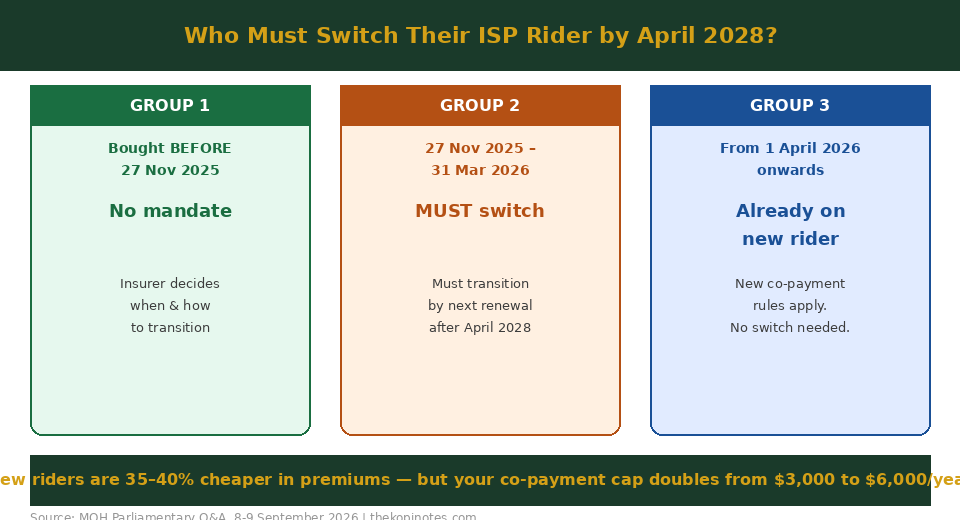
Here is the key thing most Singaporeans don’t realise: the April 2028 transition deadline does NOT apply to everyone. Where you stand depends entirely on when you bought your rider.
Source: MOH Parliamentary Q&A, 8–9 September 2026 | thekopinotes.com
| Group | When You Bought Your Rider | What Happens |
|---|---|---|
| Group 1 | Before 27 November 2025 | Your insurer decides when and how you transition. No government-set deadline. |
| Group 2 | 27 November 2025 to 31 March 2026 | You MUST transition to a compliant new rider by your next policy renewal from April 2028. |
| Group 3 | From 1 April 2026 onwards | You are already on the new rider structure. No transition needed. |
Source: MOH Parliamentary Q&A, 8 September 2026 (Notice Paper No. 1236)
Group 1 is the largest group. Most policyholders bought their riders before 27 November 2025. For them, MOH has left the decision to individual insurers. Your insurer may or may not push you to switch — and if they do, the timeline is up to them.
This matters a lot. If you are in Group 1, you have more time and flexibility than you might think. You are not on a government-mandated clock.
The April 2028 Deadline Explained
The April 2028 deadline only applies to Group 2 — those who bought riders between 27 November 2025 and 31 March 2026. This was a relatively short four-month window.
Why this window? MOH wanted to prevent a rush of people locking in legacy rider terms right before the April 2026 cutoff. By treating this group separately, MOH ensured people who had just bought a rider under the old rules would still need to move to compliant terms — just with a grace period of about two years.
For this group, the transition must happen at your next policy renewal after 1 April 2028. So if your policy renews in June 2028, that is when you must switch to a compliant new rider.
MOH confirmed in parliament (8 September 2026) that it does not track the proportion of legacy policyholders who have voluntarily switched. It is too early to assess trends since the April 2026 launch.
Legacy Rider vs New Rider: The Trade-Off
Whether you have to switch by 2028 or not, many policyholders are asking: is the new rider actually worth it? Here is a side-by-side comparison.
| Feature | Legacy Rider (Before April 2026) | New Rider (From April 2026) |
|---|---|---|
| Deductible Coverage | ✅ Covered (with max coverage riders) | ❌ Not covered — you pay this |
| Co-Payment Cap | $3,000 per year | $6,000 per year |
| Annual Premium (est.) | Higher (baseline) | 35–40% lower on average |
| Out-of-Pocket Risk | Lower per hospitalisation | Higher per hospitalisation |
| Who Benefits Most | Frequent hospitalisations, chronic conditions | Healthy individuals, cost-conscious policyholders |
Source: MOH Parliamentary Q&A, 8 September 2026 | thekopinotes.com
The 35–40% premium saving is meaningful. For a 40-year-old, that could be hundreds of dollars per year. But the higher co-payment cap means if you do get hospitalised, you could pay up to $6,000 out of pocket before the rider kicks in fully.
For most healthy Singaporeans who are hospitalised rarely, the new rider saves more money over time. For those with chronic conditions or who expect regular hospitalisations, the legacy rider’s lower co-payment cap may be worth keeping — at least until your insurer forces the switch.
Should You Switch Voluntarily?
If you are in Group 1 (bought before 27 November 2025), your insurer has not been forced to push you to switch. But should you proactively switch anyway?
Here is a simple decision framework:
| Your Situation | Recommendation |
|---|---|
| You are young, healthy, rarely hospitalised | Consider switching to save on premiums. The lower co-payment cap matters less if you rarely use it. |
| You have a chronic condition or frequent hospitalisations | Hold on to your legacy rider for now. The lower co-payment cap offers more protection when bills are predictably high. |
| You are in Group 2 and the deadline is approaching | Plan ahead. Compare new rider quotes from your insurer before the renewal date to avoid a last-minute rush. |
| Your insurer offers a new rider with improved terms | Review the specific terms carefully. Some insurers may offer compliant riders that are better than the minimum requirement. |
If you are weighing whether to downgrade your ISP rider or switch, make sure you understand what your specific insurer’s new rider covers — the co-payment structure can vary between providers.
Also read our broader guide on the shield plan Singapore options to understand how your base plan interacts with your rider choice.
MOH Data: Why the Numbers Tell a Story
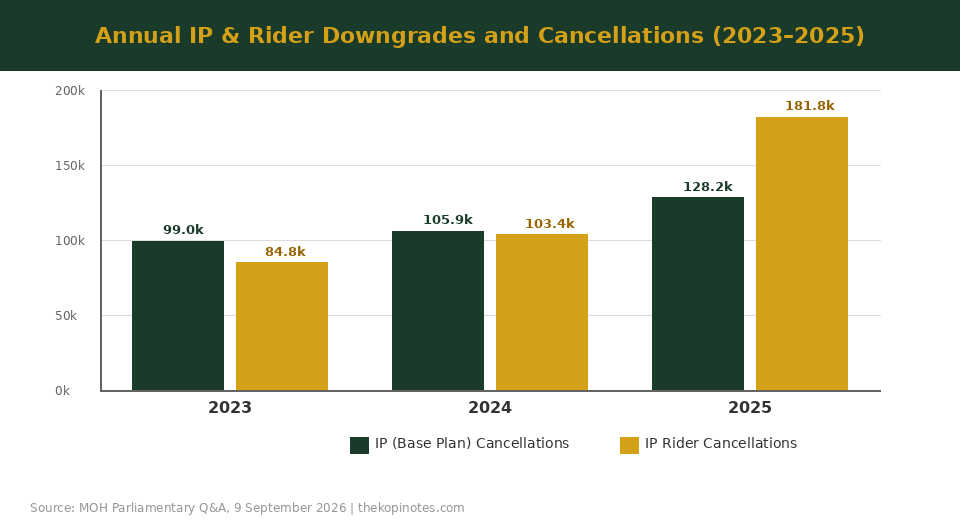
Before the new riders even launched, 182,000 policyholders cancelled or downgraded their riders in 2025. That is a 76% jump from 103,400 in 2024.
Many did it in anticipation of the April 2026 changes. Some cancelled outright. Others downgraded from maximum coverage to more basic riders. The broader ISP downgrade statistics from MOH tell a clear story: rising premiums are making Singaporeans rethink their coverage.
Source: MOH Parliamentary Q&A, 9 September 2026 | thekopinotes.com
| Metric | 2023 | 2024 | 2025 |
|---|---|---|---|
| IP (Base Plan) Cancellations | 99,000 | 105,900 | 128,200 |
| IP Rider Cancellations / Downgrades | 84,800 | 103,400 | 181,800 |
Source: MOH Parliamentary Q&A, 9 September 2026 (Notice Paper No. 1117) | Mr Saktiandi Supaat, MP for Bishan-Toa Payoh GRC
The 29.5% rise in IP base plan cancellations from 2023 to 2025 is significant. It suggests affordability is becoming a real concern — not just for riders, but for the base plan itself. If you are thinking of cancelling your base plan, read our guide on what is an Integrated Shield Plan first to understand what you would be giving up.
Meanwhile, MOH noted that it does not track why policyholders cancel — they may have done so for affordability reasons, to right-size coverage, or for other personal circumstances. For a deeper look at the decision many faced, see our guide on whether to cancel your ISP rider.
MOH also acknowledged in parliament that the full impact on the private healthcare ecosystem — including whether over-servicing actually drops — will take time to show up. The new rider rules are designed to work over the long term.
Frequently Asked Questions
Do I have to switch my ISP rider to the new structure by April 2028?
What is the difference between the legacy ISP rider and the new rider?
My insurer hasn't asked me to switch. Do I still need to act?
How much cheaper is the new ISP rider compared to my current legacy rider?
How many Singaporeans cancelled their ISP riders in 2025?
If I cancel my ISP rider entirely, can I get it back later?
What happens to legacy riders that are not mandated to transition?
Not financial advice. All data sourced from MOH Parliamentary Q&A, 8–9 September 2026 (Notice Paper No. 1236 and Notice Paper No. 1117). Data verified as at 24 September 2026. Speak to a licensed financial adviser before making changes to your health insurance.
Get Free Insurance Advice
Speak with a licensed insurance advisor. No obligation, no cost.
By submitting this form, you agree to our Privacy Policy.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.