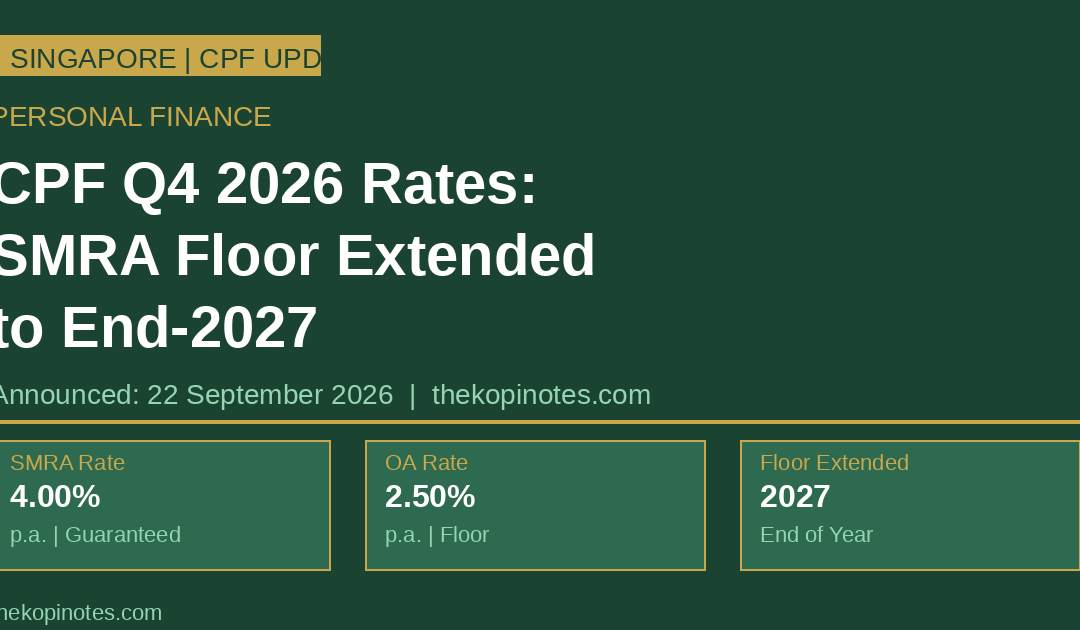
On 22 September 2026, the CPF Board and HDB confirmed that CPF Special, MediSave and Retirement Account (SMRA) interest rates will remain at the 4% floor for Q4 2026 — and extended that floor guarantee all the way to end-2027.
This is an editorial analysis. Not financial advice. Data verified as at 23 September 2026.
CPF Q4 2026 Interest Rates: Official Announcement
| CPF Account | Q4 2026 Rate (p.a.) | Pegged Rate | Key Notes |
|---|---|---|---|
| Ordinary Account (OA) | 2.50% | 0.32% | Based on 3M avg of major bank rates (May-Jul 2026) |
| Special Account (SA) | 4.00% | 3.06% | Floor extended to 31 December 2027 |
| MediSave Account (MA) | 4.00% | 3.06% | Floor extended to 31 December 2027 |
| Retirement Account (RA) | 4.00% | 3.06% | For members aged 55 and above |
| HDB Concessionary Loan | 2.60% | — | Pegged at OA rate + 0.1% |
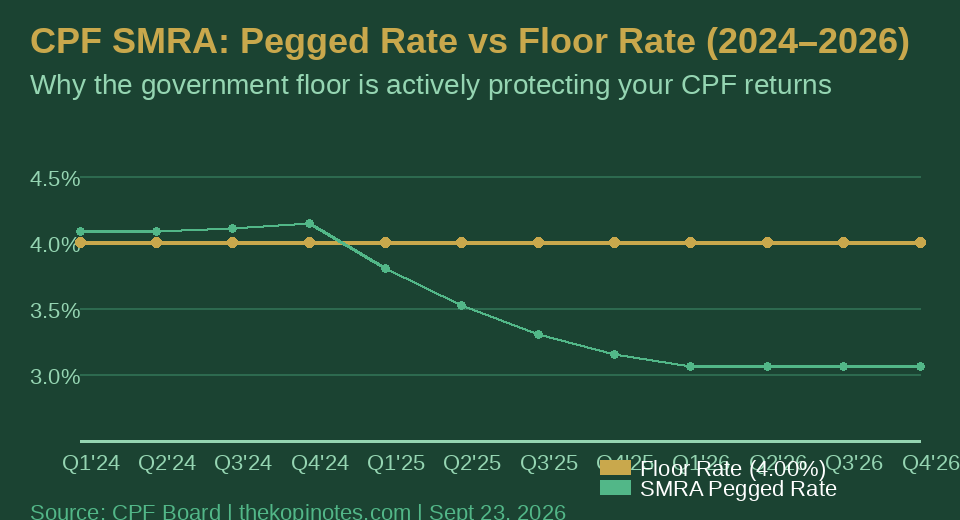
The SMRA rate is pegged to the 12-month average yield of 10-year Singapore Government Securities (SGS) plus 1 percentage point. That figure stands at 3.06% (August 2025 to July 2026) — still below the 4% floor. Hence, the floor applies and members earn the protected 4% rate.
Why the Floor Extension to End-2027 Matters
The extension of the SMRA floor to 31 December 2027 provides CPF members with 15+ months of rate certainty. Just one week before this announcement, the US Federal Reserve raised rates to 3.75%-4.00% at its September 16, 2026 FOMC meeting — the first Fed hike since 2023.
The MAS has already tightened monetary policy twice in 2026, with 45% of forecasters expecting further tightening in October. In this environment, CPF’s guaranteed 4% floor is a standout anchor for retirement savings.
CPF vs Other Safe Instruments in Q4 2026
| Instrument | Current Rate (p.a.) | Liquidity | Government Guarantee |
|---|---|---|---|
| CPF SMRA | 4.00% (floor) | Restricted (retirement use) | Yes — Singapore Government |
| CPF OA | 2.50% (floor) | Restricted (HDB, investments) | Yes — Singapore Government |
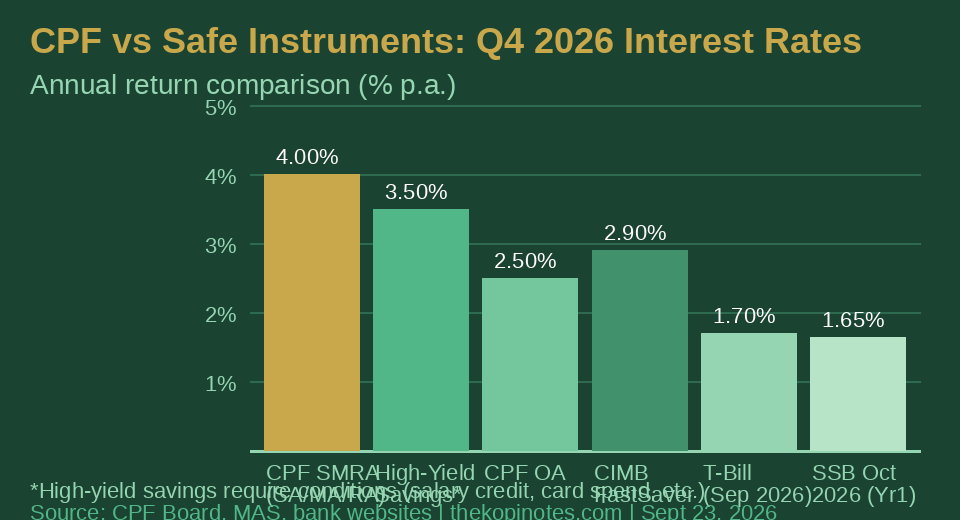
| SSB October 2026 (Year 1) | 1.65% | Monthly redemption | Yes — Singapore Government |
| 6M T-Bill (Sep 10 Auction) | ~1.70% | At maturity (6 months) | Yes — Singapore Government |
| High-Yield Bank Savings | Up to 5.85%* | Daily (conditions apply) | SDIC up to S$75,000 |
*Requires conditions like salary crediting, card spending, insurance/investment purchases.
Singapore T-bill yields have fallen to around 1.70% as of the September 2026 auction cycle. The SSB October 2026 issue offers just 1.65% in Year 1. Against these, CPF SMRA’s guaranteed 4% is clearly superior for retirement money.
Extra Interest: The Compounding Boost Most Members Overlook
- Members below age 55: Extra 1% p.a. on the first S$60,000 of combined CPF balances (capped at S$20,000 for OA).
- Members aged 55 and above: Extra 2% p.a. on the first S$30,000, and extra 1% on the next S$30,000 (OA capped at S$20,000).
3 Smart CPF Moves for Singapore Investors in Q4 2026
1. Top Up Your CPF SA or RA Under the RSTU Scheme. Voluntary cash top-ups earn the 4% guaranteed rate. The 2026 FRS is S$220,400. Top-ups by 31 December qualify for income tax relief of up to S$8,000 for self-top-ups and S$8,000 for eligible family members.
2. Review Your MediSave Voluntary Contributions. The MediSave Account earns 4% and the BHS ceiling is S$79,000 in 2026. Voluntary contributions to MA are tax-deductible up to the annual CPF contribution cap. See our MediSave BHS 2026 guide.
3. Reconsider Your T-Bill Ladder. With T-bills at ~1.70%, money that doesn’t need near-term liquidity earns a better guaranteed 4% inside CPF via RSTU. See our T-bill ladder strategy guide for the trade-off analysis.
Bottom Line for SG Investors
The CPF Q4 2026 announcement confirms that the 4% SMRA floor stays through the end of 2027. With T-bills at 1.70%, SSBs at 1.65% in Year 1, and the Fed hiking again, CPF remains Singapore’s most compelling risk-free vehicle for retirement money. See our CPF 2026 changes guide and our Best Investments in Singapore 2026 guide.
CPF Q4 2026 Interest Rates: FAQ
What are the CPF interest rates for Q4 2026?
The OA rate is 2.50% per annum. The SA, MA, and RA all earn 4.00% per annum, as confirmed by CPF Board and HDB on 22 September 2026.
Has the 4% SMRA floor been extended beyond 2026?
Yes. The CPF Board confirmed on 22 September 2026 that the 4% floor for SMRA savings has been extended until 31 December 2027.
Is CPF better than T-bills or SSBs right now?
For retirement money: yes, significantly. CPF SMRA offers a guaranteed 4% vs the September 2026 T-bill cut-off yield of ~1.70% and SSB October 2026 Year 1 rate of 1.65%.
Can I voluntarily top up my CPF to earn 4%?
Yes. Under the RSTU Scheme, you can make cash top-ups to your SA (if below 55) or RA (if 55 and above) to earn the 4% SMRA rate, up to the 2026 FRS of S$220,400. Top-ups of up to S$8,000 each for yourself and eligible family members qualify for income tax relief.
This article was researched with the help of AI. While we strive to keep all information accurate and up to date, there may be errors. If you notice any discrepancies, please contact us.